

Yangzijiang's largest shareholder sees spin-off helping shipbuilder, offshoot get fair valuations
Tay Peck Gek
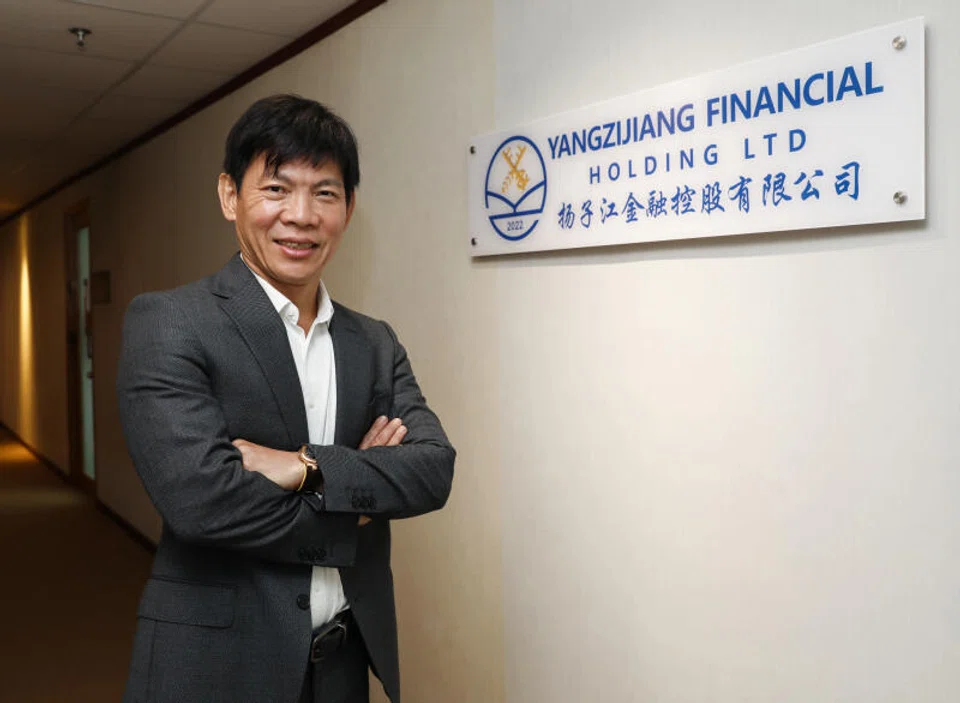
THE spin-off of Yangzijiang Shipbuilding (Holdings)' investment segment might be taking place at a time when the stock market is volatile, but the shipbuilder’s honorary chairman and largest shareholder believes the move will help both entities to eventually achieve their fair valuations.
In an unusual way of listing that does not raise capital through a public offering or private placement, Yangzijiang Financial Holding (YZJFH) - the spun-off investment segment of Yangzijiang Shipbuilding - will debut on the Singapore Exchange mainboard by dividend in specie.
That is, shareholders of the mainboard-listed Yangzijiang Shipbuilding will get the same quantity of shares in YZJFH as they own in the China-based vessel builder.
YZJFH executive chairman Ren Yuanlin explained to The Business Times in Mandarin over Zoom on Monday (Apr 25) that the investment and private assets fund manager currently has no need for additional capital, and therefore, the listing is not raising funds from the market.
“We (Yangzijiang Shipbuilding and the investment segment) split first and (then) develop separately. If there is a need for fundraising, we will then do it. Anyway, fundraising in Singapore is not difficult. However, we don’t have such a need now. We had attracted investors pre-spinning off,” noted Ren, who was formerly executive chairman of Yangzijiang Shipbuilding before handing the reins over to his son Ren Letian.
Ren was referring to Alexandrian Worldwide, a company owned by the management of Yangzijiang Shipbuilding, and EDBI, the investment arm of the Singapore Economic Development Board, as strategic investors.
Although YZJFH and Yangzijiang Shipbuilding are not seeking immediate drastic price appreciation as a result of the spin-off, Ren believes that it will not adversely impact the shipbuilder’s share price either. He added that geopolitical tensions and health risks are existent, regardless of whether YZJFH is spun off or not. He believes, however, that the share prices of YZJFH and Yangzijiang Shipbuilding post spin-off will revert to fair valuation over time.
Yangzijiang Shipbuilding should command a valuation comparable to that of its South Korean, Japanese, Singapore and Taiwanese peers in terms of price-to-book or price-to-earnings ratio, said Ren; but he declined to put a price on the shipbuilding counter.
Given that the listing takes the form of a dividend in specie, there is no listing price for YZJFH to begin trading with on Thursday. The trading price will be determined by the market. YZJFH has a total net asset value of about S$4.3 billion, or S$1.08 on a per-share basis.
YZJFH will list as a Straits Times Index component with the same investable weight as Yangzijiang Shipbuilding, with current constituent ComfortDelGro Corporation said to be at risk of being dropped from the 30-stock blue-chip index. STI constituents will be ranked by market capitalisation on Thursday, and the counter with the smallest value will exit the index on May 5.
While the listing prospectus has spelled out that the dividend payout ratio would be at least 30 per cent, Ren said he plans to recommend a ratio of no less than 40 per cent. He also said that share buybacks - subject to required approval - might be instituted if the counter dips below the industry’s average price-earnings levels, without giving a specific price range.
YZJFH presently has 60 per cent of its portfolio in private credit, 20 per cent in private equity and funds, and another 20 per cent in cash - all in China.
Ren dismissed regulatory risks for its lending to small- and medium-sized enterprises (SMEs) in the private sector in mainland China, saying that YZJFH is not competing with the banks but is serving SMEs with no access to bank loans. Although financing SMEs carries a higher credit risk, YZJFH has a "rigorous" vetting process and only lends to SMEs from areas where the local economies are doing well.
Nonetheless, to diversify risks across geographies and asset classes, as well as increase product offerings, its bondholding will be reduced to 30 per cent, private equity and fundholding will rise to 40 per cent, while offshore investment will go up from zero to 20 per cent by 2023, YZJFH chief executive officer and chief investment officer Vincent Toe Teow Heng said.
Toe added that offshore investments will target Europe, the United States and Asia excluding China.
YZJFH is targeting a return on equity of 8 to 10 per cent. It will generate income from 2 areas: fee income (from fund management and wealth management), and investment returns. Sectors the company will target include high-technology; healthcare; environmental, social and governance (ESG); and cleantech.
YZJFH will on Thursday complete the acquisition of Singapore company GEM Asset Management, which will serve as YZJFH's springboard into the fund management and wealth management field. This will also allow investors to make cross-border investments, such that Chinese investors are able to invest in offshore products and vice versa for foreign investors in China, where capital controls are in place.
YZJFH aims to attract S$1 billion in third-party capital in a year’s time.
TRENDING NOW

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

