

Asean governments face risk of fiscal strain from climate change without policies to attract private capital
This further burdens public finances and diverts funds from other priorities such as healthcare and education
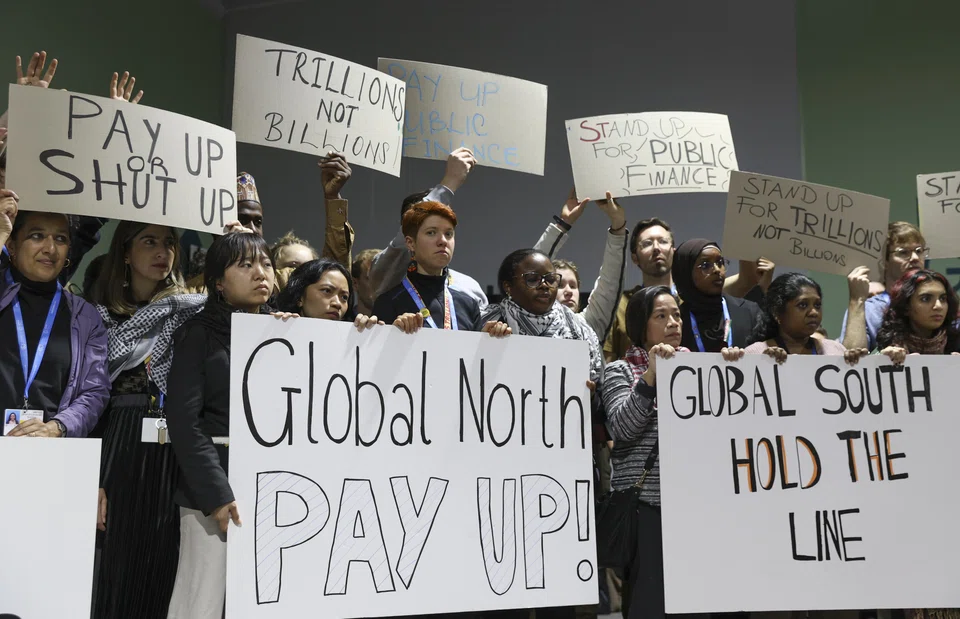
WITH the United Nations’ climate talks failing to secure the US$1 trillion climate finance target needed for developing countries to cut their emissions and cope with natural disasters, emerging markets in South-east Asia are now under greater pressure to develop the right policy framework to catalyse private capital into climate-focused investments.
Without sufficient funds, South-east Asian governments might face increasing financial strain as they will need to allocate more of their own budgets to climate-related expenditures. This further burdens public finances and diverts funds from other priorities such as healthcare and education, said Mike Lim, partner at venture capital firm Trirec.
As it is, they are already struggling to adequately fund climate resilience and adaptation projects needed to mitigate the effects of extreme weather events, the region being one of the most vulnerable to the adverse impacts of climate change. This includes rebuilding critical infrastructure such as coastal defences, early warning systems and resilient housing, as well as other sustainable development projects, observers told The Business Times.
Unfortunately, emerging markets in this region are stuck between a rock and hard place.
On the private capital front, the higher risks involved in investing in South-east Asia – whether actual or perceived – have often either kept investors away, or resulted in expectations of a higher premium on returns.
Given the limitations in public funds, these markets may explore alternative financing strategies – such as issuing sovereign labelled bonds, leveraging public-private partnerships or seeking technical assistance from international organisations, said Melissa Cheok, associate director of environmental, social and governance investment research at ratings agency Sustainable Fitch.
However, these measures may not fully compensate for the shortfall in the climate finance quantum eked out at the recent COP29 summit, and therefore could potentially lead to slower progress in achieving their climate and sustainable development goals.
Close to 200 countries were hammering out a climate finance agreement over two weeks in windowless tents in Baku, Azerbaijan, with battle lines drawn between developing countries often suffering the brunt of climate change impacts despite contributing the least to climate change, and developed countries obligated to provide public funds to these countries due to their historical contribution to global warming.
After threats of a walk-out by some negotiating parties, they eventually settled on a quantum of US$300 billion per year till 2035 – far below the US$1 trillion annually that economists have said is needed – more than 32 hours after the summit overran.
Known as the New Collective Quantified Goal on Climate Finance, this new sum of US$300 billion will supersede the previous target of at least US$100 billion a year, which expires in 2025.
It is part of a wider effort to scale up climate financing to US$1.3 trillion every year until 2035, with the remaining US$1 trillion to be mobilised “from all public and private sources”, though details on how this could be achieved remained unfinished.
Policy support
Raising that remaining US$1 trillion is going to be a challenge, said Antony Warren, founder and chief executive officer of family office Eden Impact.
While the rules governing the international trading of carbon credits – known as Article 6.4 of the Paris Agreement – could help rebuild confidence in carbon markets and channel more private capital into climate-focused investments, policy support from Asean governments remains key to attracting private investors, he added.
Even though private capital has a role to play in the energy transition, it cannot be expected to do it alone, said Melissa Moi, head of sustainable business at the corporate sustainability office at UOB.
“Private participation depends on commerciality. Investment and financing decisions must be financially viable, which can happen only if regulatory policy creates a conducive environment,” she added.
Some basic building blocks include greater transparency through better governance and reporting, policy consistency and stability. This will give investors more confidence, especially in infrastructure projects that have a long-term horizon, as well as some degree of certainty around the future, financiers and observers told BT.
Cutting down bureaucratic hurdles of green projects could also scale them faster, and make them more attractive to private investment.
“In Asia, one impediment to scaling up projects has been the propensity to haggle over contracts, which takes time. In Asean, for example, energy regulations vary across markets, often leading to power purchase agreement delays,” said Mike Ng, chief sustainability officer of OCBC.
Standardising contractual arrangements across the region could help green projects take off more quickly, he added.
Ensuring the commercial viability of new green climate technologies and solutions by creating market demand through policies and regulations is also another piece to the puzzle. That is because nascent green technologies are typically too costly to implement and lack demand, said Ng.
One example is Singapore’s mandate for flights leaving Changi Airport to include sustainable aviation fuel in their fuel mix from 2026.
Aligning the Asean taxonomy on sustainable finance with other regional ones to develop commonalities on the definition of green economic activities could reduce concerns about greenwashing, said Tiza Mafira, director at Climate Policy Initiative.
Other forms of policy reforms could be potentially more challenging to implement, such as imposing a carbon tax regime for the region, as suggested by Ng. “The carbon tax will put a price on carbon and steer regional investments towards low-carbon alternatives in existing as well as new technologies,” he added.
Of course, the biggest sacred cow in South-east Asia is fossil fuel subsidies.
With public funds already scarce, there is a need to optimise every dollar by shifting it away from fossil fuel subsidies, said Mafira. The money should be redirected towards derisking and incentivising decarbonisation projects (such as the early closure of coal plants), as well as developing key enabling infrastructure (such as electricity grid optimisation).
However, that has yet to take place in many South-east Asian governments as it is a political hot potato.
Indonesia did not touch on its fossil fuel subsidy reform when it announced its grand plans to accelerate its climate ambitions during COP29 and a week later at the G20 summit at Brazil.
Nonetheless, observers said that Indonesia’s move to bring forward its net zero target by a decade to 2050 and close all of its fossil fuel plants by 2040 is a positive step.
While such initiatives can instill confidence in investors about the region’s dedication to climate action, much will hinge on whether supportive policies are implemented and actionable strategies are put in place to facilitate their execution, said Cheok.
Lim said that investors will still watch out for whether there is transparent and efficient implementations of such policies, given previous examples of bureaucratic delays and policy reversals in the past in the region.
One week after Indonesia unveiled its new climate targets, it said that it will review plans to export clean electricity as the government prioritises national interests and sustainability in allocating natural energy resources.
Blended finance
Besides policy support, greater innovation in financial instruments combined with blended finance mechanisms will move the needle most when attracting climate investments, said Clare Shakya, global managing director of climate of environmental non-profit The Nature Conservancy.
Blended finance is a capital-raising approach that leans on investors with higher risk appetites, such as development funds and philanthropists or governments, to provide concessional or catalytic capital to pull in more commercial investors.
A lower cost of capital, achieved through such structures, can improve the bankability of projects that would otherwise not be able to secure private capital. This is especially the case for emerging markets in South-east Asia, where a higher cost of capital has been a hurdle to the deployment of private capital, said Helge Muenkel, chief sustainability officer of DBS Bank.
To this end, Singapore said that it will commit US$500 million as concessional capital to support a blended-finance initiative, known as the Financing Asia’s Transition Partnership (Fast-P), at COP29. It also launched a third investment fund under Fast-P, which will focus on decarbonising hard-to-abate sectors, with BlackRock as its fund manager.
Observers said that Singapore’s initiative is commendable. But to fully mobilise private capital, it is also essential to have strong institutional frameworks and a pipeline of bankable projects, said Cheok.
“In Asia, one impediment to scaling up projects has been the propensity to haggle over contracts, which takes time.”
OCBC chief sustainability officer Mike Ng
TRENDING NOW

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

