

Costs of energy transition likely to go up over short term due to Iran war, says OCBC CSO
The lender expects persistent inflationary pressures as central banks keep interest rates higher for longer
[SINGAPORE] Companies implementing their low-carbon transition plans are likely to face higher costs over the short term due to the Iran war.
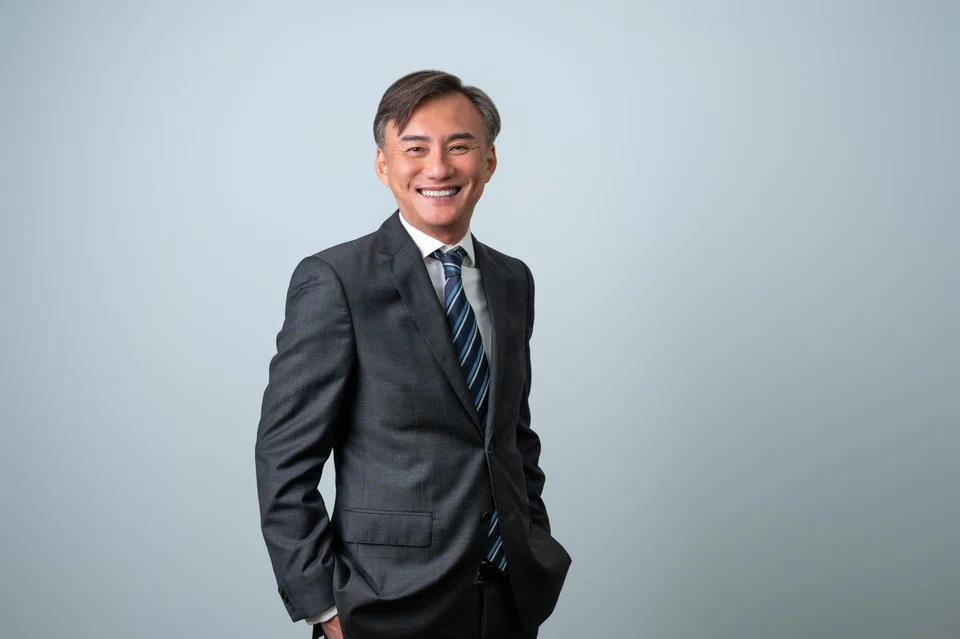
Hence, they need to be more strategic when prioritising their decarbonisation investments and capital expenditure, even as they manage the uncertainties and volatility of the current geopolitical environment, said OCBC chief sustainability officer Mike Ng.
While sustainability and the energy transition are increasingly being viewed as critical to strengthening energy security and resilience – after having taken a backseat following the return of US President Donald Trump to power last year – the Iran war has nonetheless created short-term headwinds for the low-carbon transition.
As companies and governments grapple with shocks to global energy prices, OCBC is expecting persistent inflationary pressures as central banks are likely to keep interest rates higher for longer.
A higher cost of financing would disproportionately affect the deployment of renewable energy, as such infrastructure projects require heavy upfront capital expenditure.
Unlike fossil fuel projects where costs are spread over decades of fuel purchase in the form of operating expenditure, almost all of the required capital is needed upfront when developing renewable energy projects.
Ng said in an interview with The Business Times: “So when you look at renewable energy, the financial viability is sensitive to the cost of financing. So when interest rates stay elevated, it does put pressure on returns.
“So while the laws of physics make renewable energy free once built, the laws of finance are making it more expensive to get off the ground in a high-interest-rate environment.”
In addition to the projected higher costs of financing, the costs of materials are also likely to go up with supply chains being disrupted amid the ongoing Middle East conflict, which was triggered in February this year when the US and Israel launched an attack on Iran.
Long-term winners
Despite the higher costs over the short term, companies that execute their energy transition plans strategically will be the winners over the longer term.
The volatility of fossil fuel supply chains, as well as its concentration in certain geographic locations – as highlighted by the Iran war – has made energy security and sustainability increasingly converging priorities, said Ng.
Making the transition to renewable energy would help with diversification by localising energy sources, as well as by distributing these assets over a wider geographic area.
“You cannot embargo the sun and you cannot block the wind at a maritime strait… In the region, if you have a gas plant or a coal plant, it’s very concentrated and you are very exposed in terms of security,” said Ng.
“But for renewables, if you want to destroy the infrastructure, it’s much more difficult because of the geographic distribution as solar farms and wind farms can be spread out over thousands of kilometres.”
While renewable energy has higher upfront costs in the form of capital expenditure, cost curves will come down with scale, unlike oil and gas.
As renewable energy projects are essentially manufacturing processes, they enjoy economies of scale, where costs can come down as more panels are built.
Oil and gas projects, on the other hand, involve extraction processes, and are also limited by finite resources.
“So very often, the best reserves of oil and gas are extracted first, forcing companies to move to deeper and more complex environments where the costs are higher,” said Ng.
Striking the right balance
This means companies need to strike the right balance between managing higher short-term costs and continuing to invest in long-term decarbonisation by carefully sequencing and prioritising the right investments.
“Higher costs will mean companies will now have to be more disciplined, but delaying transition investments entirely can also create bigger risks down the road, whether you’re looking at regulations, stranded assets or loss of competitiveness,” said Ng.
Besides navigating the challenges between short-term costs and long-term value, companies would also have to grapple with the tension between efficiency and resilience.
While companies once focused on optimising costs through “just-in-time” business models, relying on lean supply chains and low inventory levels, recent years have underscored the importance of embedding resilience into business models – whether through energy security, supply chain diversification or greater operational flexibility.
This resiliency mindset is not exactly new – many companies have embarked on this shift when the Covid-19 pandemic hit in 2020.
“Having this redundancy may mean some duplication or even upfront investment, but it does reduce long-term uncertainty and vulnerability. So it definitely looks less efficient on paper but is more robust in the world we are in now, which is volatile,” said Ng.
“So the companies that we think will do well and outperform are those that will move from ‘just-in-time’ thinking to ‘just-in-case’ thinking.”
With companies facing pressures on multiple fronts – including energy price shocks, the rise of artificial intelligence, and an increasingly unpredictable macroeconomic and geopolitical environment – he also noted that firms need to move towards scenario-based planning rather than relying solely on linear planning.
“Instead of relying on a single forecast, companies now need to plan across multiple scenarios, whether you look at energy price shocks, policy shifts or technology disruption, and build flexibility into their strategies,” said Ng.
“And even after having plans A, B and C, companies need to be comfortable with the discomfort that whatever plans we have, those plans can get outdated very quickly, because the underlying assumptions and the conditions can and will change.”
Diversification strategies
Beyond the impact on companies’ balance sheets and their response strategies, the Iran war has also revealed the vulnerabilities of Asia’s reliance on imported fossil fuel.
In South-east Asia, which predominantly consists of emerging markets, the impact has been more acute. The Philippines had to declare a state of emergency, while Indonesia and Vietnam implemented energy rationing measures.
There would likely be a structural shift towards electrification among Asean countries to reduce their reliance on imported energy.
Governments would more proactively push to broaden their energy mix. This includes accelerating the deployment of renewables but also other energy alternatives, such as nuclear, low-carbon hydrogen, and biofuel, in the case of Indonesia.
There will also be greater emphasis on reducing dependence on a single source or supply route, including renewable energy.
“The region will remain a major energy importer in the near term, but its long-term strategy will increasingly be about reducing the risk of their dependence, not necessarily eliminating imports entirely, but making the system more diversified, more flexible, more resilient,” said Ng.
Asean power grid
One major pathway to increase the resiliency of the region’s energy system is through the Asean power grid, which has been in discussion over at least two decades.
Having an interconnected power grid across South-east Asia directly addresses the vulnerabilities exposed by the Iran war.
By connecting national grids, countries are not only able to diversify their energy sources. It also helps smooth out the variability of renewable energy generation and demand, allowing countries to export surplus energy during periods of excess, or import when local resources are inefficient to meet the demand.
As renewable resources in the region are unevenly distributed, having an interconnected grid allows the resources to be shared efficiently, which helps reduce overall system and accelerate the deployment of renewable energy in the region.
“The Asean power grid is not just a decarbonisation project, it’s also an energy security project. That said, the challenges have always been on execution, regulatory alignment, getting financing and cross-border coordination,” said Ng.
“But with the risk now more visible, there is a stronger case for governments and for investors to move with greater urgency. So in a more uncertain world – like what we are seeing now – energy security will increasingly depend not just on self-sufficiency, but also on smart interdependence,” he added.
The Asean power grid can also help mitigate a key risk often associated with renewable energy investments in the region – the higher perceived investment risk of deploying such projects across markets that may not provide the necessary regulatory support.
Some of these concerns are alleviated as Singapore is an offtaker for most of these cross-border low-carbon power projects.
Ng believes that it’s important for smaller cross-border import projects within the region to come to fruition before a fully integrated Asean-wide system comes to pass, as these would serve as proof points that cross-border pricing works and that technical integration is manageable.
There are already smaller-scale examples in operation, including the Laos-Thailand-Malaysia-Singapore power integration project.
“I think in Asean, there is still a trust deficit among member states, and we need to build that trust through some of these prototype projects. So my view is that the grid will likely emerge bottom-up and not top-down,” he said.
“No single country can optimise renewables on their own, and I think the unlock will likely come from smaller sub-regional projects. So rather than a big bang solution, we will see the grid emerge piece by piece and eventually connect into something much bigger.”






