

Financing for energy transition in Asean gains momentum at COP28
[DUBAI] Plans to corral capital to finance South-east Asia’s transition to a low-carbon economy is underway at the annual United Nations climate change conference - the latest development being the first early retirement of a coal plant in Indonesia.
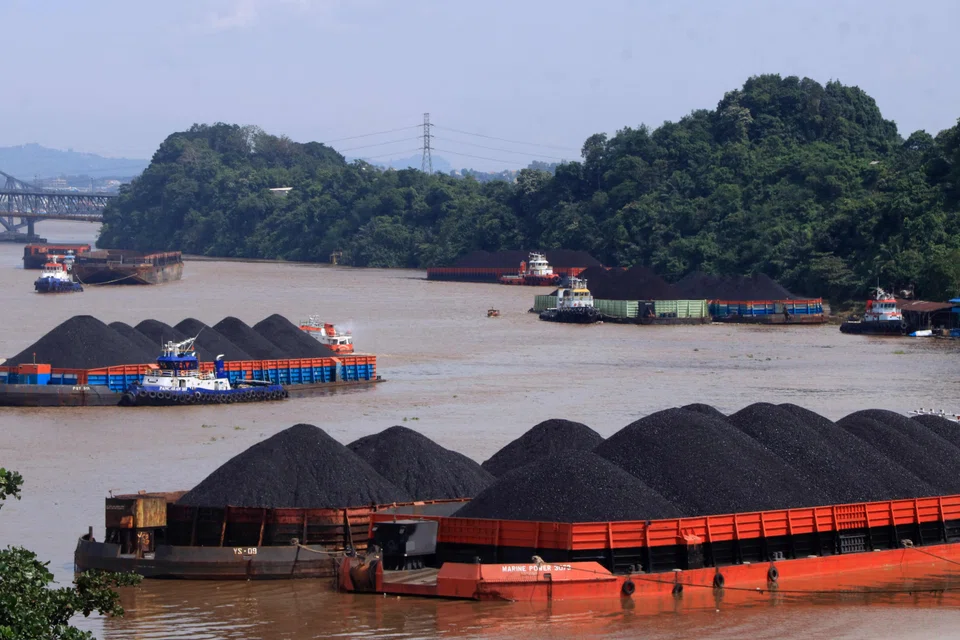
On Sunday (Dec 3) at the Indonesia pavilion at COP28, Indonesia’s Finance Minister Sri Mulyani announced that the 660-megawatt Cirebon-1 plant will likely cease operations in December 2035 – seven years earlier than its original retirement date of July 2042.
This deal comes one year after South-east Asia’s largest economy inked a US$20 billion Just Energy Transition Partnership (JETP) with a group of developed nations made up mostly from the Group of Seven countries and private-sector banks.
It also marks the first transaction under the Asian Development Bank (ADB) energy transition mechanism programme. The multilateral development bank had signed a memorandum of understanding a year ago with plant owner Cirebon Electric Power to explore whether it was possible to close the plant early.
Just a short five-minute walk away at the Singapore pavilion, the city-state’s central bank announced a slew of initiatives aimed at developing transition finance to accelerate decarbonisation in Asia on Sunday.
This includes the final version of the Singapore taxonomy, a blended finance platform seeking to mobilise at least US$5 billion of capital and the formation of a coalition for transition credits, a new category of carbon credits generated when coal-fired power plants are retired early and replaced with cleaner energy sources.
The central bank of Malaysia also announced on the same day the development of a risk assessment guide, in consultation with the Taskforce for Nature-related Financial Disclosures, on how Malaysian financial institutions and businesses can identify their nature-related dependencies, risks and opportunities.
Bank Negara Malaysia will also work with the World Bank to develop innovative financial instruments to support private investments in nature, including enabling regulations to support nature-positive outcomes and piloting new financial structures.
And just two days ago, Vietnam released its financing framework to implement its plans under its own JETP, which the country also signed with the same group of developed nations over a year ago.
The flurry of initiatives suggests that there is increasing momentum towards clean energy transition among member states of the Association of South-east Asian Nations (Asean).
But questions remain still on whether these are enough to catalyse more private sector capital to close the international financing gaps for these countries, many of which are less-resourced emerging markets, said Philip Gass, the director for energy programme at think tank International Institute for Sustainable Development.
“There is a need to ensure that the focus is on tools like grants and mechanisms that do not create financial stress, rather than loans that could risk locking in debt in the country for future generations,” Gass said.
It was no surprise that the amount of grant funding in both the Indonesia and Vietnam JETPs was miniscule to the total size of the deal.
For the Indonesia JETP, the amount of grant funding, as laid out in its investment plan launched shortly before COP28, is only US$153.8 million excluding technical assistance – just 0.8 per cent of the total size of the US$20 billion climate deal.
While the amount of grant funding for the Vietnam JETP seems higher at US$321.5 million, it includes technical assistance.
A higher amount of grant funding not only means that these countries will have lesser to repay, it would also help to de-risk energy transition projects in these markets and enable greater participation from private-sector capital.
As for coal phase-out, the early retirement of Cirebon-1 is a good first step for Indonesia, but questions remain on the scalability of such transactions.
The non-binding agreement between ADB, Cirebon Electric Power, state-owned utility company PLN and the Indonesia Investment Authority involves shortening the power purchase agreement for Cirebon-1 by seven years, with plans to finalise the transaction in the first half of 2024.
Elaborating on the financing mechanism of the early phase-out of Cirebon-1, David Elzinga, team leader for the energy division of the energy transition mechanism in the South-east Asia department at ADB, said that the coal plant has a long tail of profit with no debt servicing until 2042.
What the energy structure mechanism did was to change the capital structure by increasing the debt-to-equity ratio over the shorter period of operations. This involved taking this projected level of equity return until 2042, applying a discount based on their expected rate of return and paying it as a dividend upfront to the plant owners, Elzinga said in an interview with The Business Times.
The funding is a blend of grants, concessional loans and commercial rate loans. Grants and concessional loans will help to bring down the cost of capital for the bulk of financing which would be commercial loans.
The debt servicing will then be covered by the revenue generated from coal generation over the remaining years of operation until its brought-forward retirement year of 2035. So financiers involved in this deal would have to be prepared to get their returns from coal power generation for the next decade.
Elzinga said private-sector banks have expressed interest in participating in this transaction, although he kept mum on the banks that have done so. He also declined to reveal the size of the dividend paid to Cirebon Electric Power.
However, not all coal plants in the region have a long tail of equity return until its original retirement date, where the capital structure can be changed to increase its debt-to-equity ratio when the years remaining for operation are shortened.
When asked whether Cirebon-1 transactions can be repeated, Elzinga said that what ADB and its Indonesian partners are trying to demonstrate through this first deal that such transactions can work.
The long-term goal is to minimise the amount of concessional capital needed and finance it through transition credits.
“We’re doing that work and learning, and then sharing what we’re doing with others so that that can be applied,” he added.
Gass noted that early retirement needs to be scalable over the long term, and that coal transition programmes should be considered for the entire sector, instead of individual plants.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

What role can Japan play in Asean’s future?

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Asean’s challenge is to become resilient against global geopolitics: former Indonesia trade minister

