

Issue 151: Adapting to GRESB’s evolution; Asia’s steelmakers on hot seat
This week in ESG: Updates to leading real estate benchmark; steel giants still milling around on decarbonisation
Sustainability ratings
A real estate benchmark digs deeper
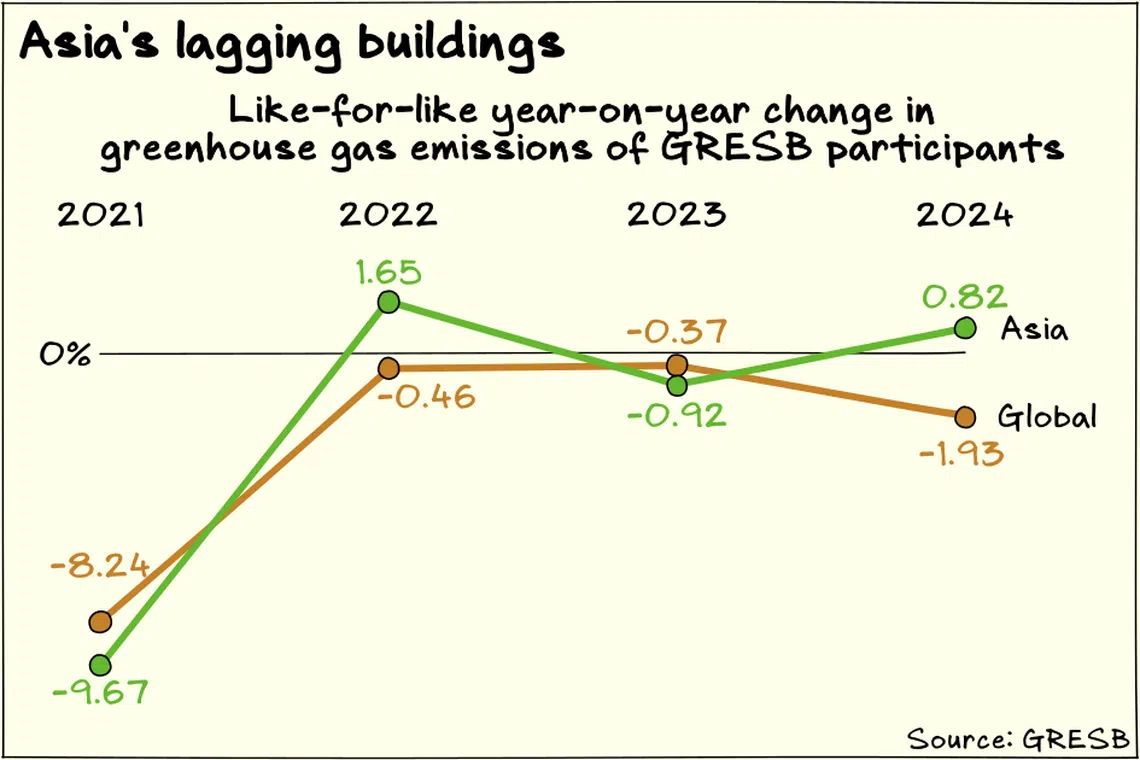
The leading real estate sustainability benchmark is looking deeper into participating companies’ performance claims to try and discern impactful progress from window dressing.
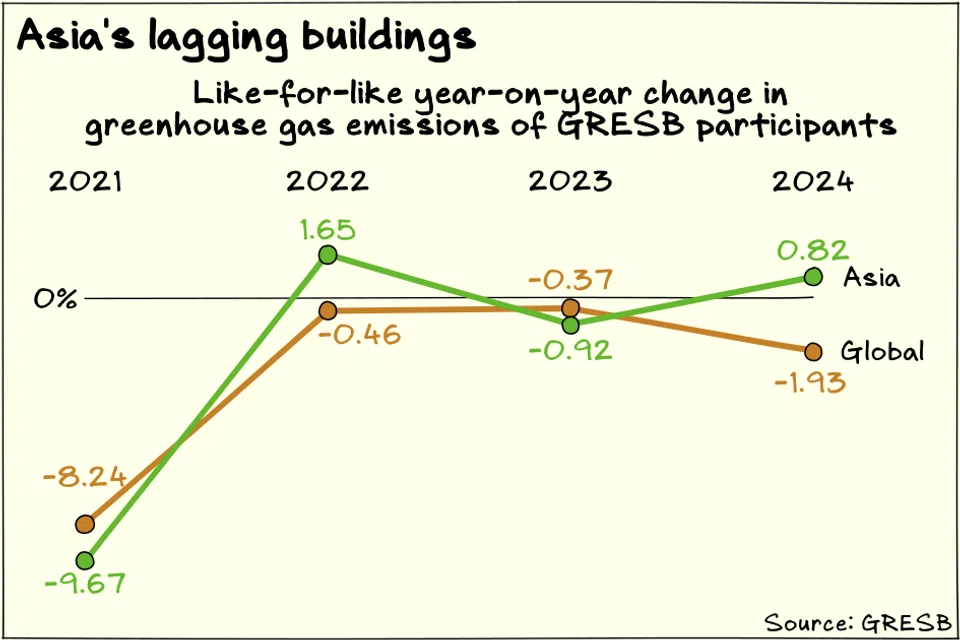
Listed property companies, real estate investment trusts (Reits) and business trusts that want to maintain or improve their standings in the GRESB ratings will need to be more disciplined about how they buy renewable power, and start to address embodied carbon.
Sustainability has become an important aspect of branding for leading Reits and business trusts, for good reason.
The growth of sustainability reporting has created demand for green properties and green financing needs from corporate tenants, lenders and investors. Furthermore, buildings that are more energy efficient and use more renewable energy tend to be more cost-efficient over the long term. Investment trusts have figured out that being sustainable is the economically wise thing to do.
Little wonder that trusts like Stoneweg European Reit (SERT) aren’t shy about flaunting their sustainability performance when it’s good.
But what’s good? For many Reits and real estate-related business trusts – and the lenders and investors that cover them – the leading arbiter is GRESB, a sustainability standard setter and scorer focused on real assets. GRESB’s annual scoring of companies participating in its assessment is widely used by markets, including about 150 investment members.
GRESB’s recently published climate action plan highlighted two aspects of its purpose. The first is that it wants to drive real-world decarbonisation. The second is that it’s still aligned with net-zero goals.
The implication is that, despite political and economic headwinds, GRESB isn’t lowering standards. Also, the benchmark’s evolutionary direction is towards prioritising real-world impact over headline numbers.
A number of previously announced changes to the GRESB standard will affect participation in 2025:
- Rewarding efficiency: The previous scoring methodology awarded points for improving the energy efficiency of an asset. However, this inadvertently penalised buildings that are already highly efficient, since improvements in such cases can be very difficult. The new methodology therefore awards points for assets that meet an energy efficiency threshold.
- Recognising quality of renewable energy procurement: The 2025 GRESB standard requires more detailed disclosure about procured renewable energy to capture how renewable energy is purchased, whether market-based claims are substantiated, and whether the renewable energy is produced close to the buildings and at the same time as the energy is consumed. The objective is to discern validity and additionality – in other words, whether renewable energy was actually purchased, and whether that purchase leads to actual development of renewable energy capacity.
- Improving reporting on embodied carbon: More than a third of the built environment’s emissions come from building materials and construction processes, which is commonly referred to as the embodied carbon of buildings. Embodied carbon doesn’t consist only of the “upfront” carbon generated during construction. It also includes wear and tear during the use stage of a building, and demolition and waste at the end of its life. The updated standard requires participants to report on targets, measurement and disclosure practices related to embodied carbon, although these will not affect their scores. The disclosures will be used to inform the development of future embodied carbon standards.
- Tightening validation and evidence requirements: The standard now requires additional disclosures on net-zero targets to explain the goal-setting process. Participants must also identify the kinds of Scope 3 emissions – greenhouse gases indirectly produced through the supply chain – that are material to them and declare whether they have a process to determine materiality. This addresses concerns about participants reporting Scope 3 emissions for which convenient data is available, rather than the emissions that matter to their assets.
The changes to the assessment of renewable energy procurement will affect most commercial developers and landlords since the density of office buildings and malls typically makes it impossible to meet energy demands purely from on-site renewable solutions like rooftop solar.
Property owners that need to buy renewable energy will have to be more deliberate in how they do it. For example, CapitaLand India Trust’s integrated annual and sustainability report describes a hierarchy of fossil fuel energy alternatives. The first way to replace fossil fuel energy is to use on-site renewables. When that is not possible, the trust will look to secure off-site renewable energy through power-purchase agreements. When that is also insufficient, the trust will use renewable energy certificates.
Companies will also have to begin laying the groundwork for reporting on embodied carbon. While the current assessment’s requirements on embodied carbon will not affect scores at this time, the trajectory of intention is to eventually incorporate embodied carbon into the assessment.
The changes to the GRESB standard won’t be trivial for a company that wants to ace the assessment. But that’s why it might pay for a real estate company to stay ahead of the changes, since doing so could meaningfully widen the gap with rivals and improve prominence to investors and lenders.
Acing the GRESB benchmark will take work, but to the victor goes the spoils.
Net zero
Galvanising decarbonisation in Asian steel
Asia’s steelmakers aren’t hot on decarbonising their businesses, and that’s everyone’s problem.
There are many reasons why the continent’s steelmakers – some of the largest are based in China and India – are cold on green steel.
One is that upfront costs of converting to cleaner production technologies – such as electric arc furnaces powered by renewable energy sources – can be quite high. Even if a steelmaker is willing to make the investment, passing on the costs to buyers is tough because buyers in the region aren’t happy to pay too much for their steel.
There are also physical limitations. Good-quality scrap steel, a critical feedstock for low-carbon production methods, is in short supply.
As a result, most steel mills in the region still rely on coking coal. The plodding pace of the steel industry is trampling on decarbonisation plans for many others.
For instance, Singapore banks DBS and OCBC are both behind on their net-zero targets for their financed emissions from the steel sector. DBS, in fact, has gotten even further away from its 2030 goal in 2024 than in the baseline year of 2021.
In 2023, the Asia Investor Group on Climate Change organised a discussion between investors and steelmakers. The roundtable’s three main takeaways might offer a path forward:
- Investors wanted more transparency and disclosures on the status of decarbonising technologies so that they could allocate capital more efficiently.
- Industry wanted stronger policy signals so that they could invest with greater confidence.
- Participants wanted greater nearby availability of renewable energy and green hydrogen.
Other ESG reads
- MAS to review corporate governance code
- Proportion of female directors at top 100 SGX companies surpasses 25% target in 2024
- Indonesia’s latest green energy plan still makes room for coal
- Solar, wind energy could power a third of Asean data centres in 2030: report
- Asean power grid could unlock 25 GW of renewable capacity, lowering Singapore’s electricity costs: Rystad Energy
- China’s EV manufacturers face their ‘Evergrande moment’
TRENDING NOW

Three ex-employees of Envy group join Ng Yu Zhi in bankruptcy

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

