

S-E Asia climate investment opportunities still sound, but speed bumps abound
Janice Lim &
Wong Pei Ting
THE risks and opportunities for financial institutions and companies remain intact in the wake of the Paris climate pact’s first progress report as South-east Asia’s ability to raise its climate ambitions remains uncertain, analysts told The Business Times.
Legacy issues, bureaucratic red tape and poor access to climate financing from both public and private sectors are among the chief obstacles that could hinder stronger mitigation of global warming in the region, the analysts said.
Charlie Knaggs, regional decarbonisation partner at sustainability consultancy ERM, said the outlook for companies related to energy transition would depend more on the maturity of their technology. For example, investors are more confident with renewable energy solutions such as wind and solar than with hydrogen, which has yet to achieve meaningful scale.
Geoff Howie, market strategist at Singapore Exchange (SGX), said corporations that move ahead of the mitigation curve have the opportunity to build market share, but they will encounter costs as they take time to make the necessary technology enhancements and also achieve production scale. Hence, it would be critical to watch a company’s capital management and gradual material steps.
Those that have demonstrated progress may already be reaping the rewards. As at Sep 8, the three strongest constituents on the Straits Times Index this year are Sembcorp Industries , Keppel Corp and Yangzijiang Shipbuilding , which averaged 46.5 per cent in total returns. These companies have all pivoted to more sustainable infrastructure or more fuel efficient solutions.
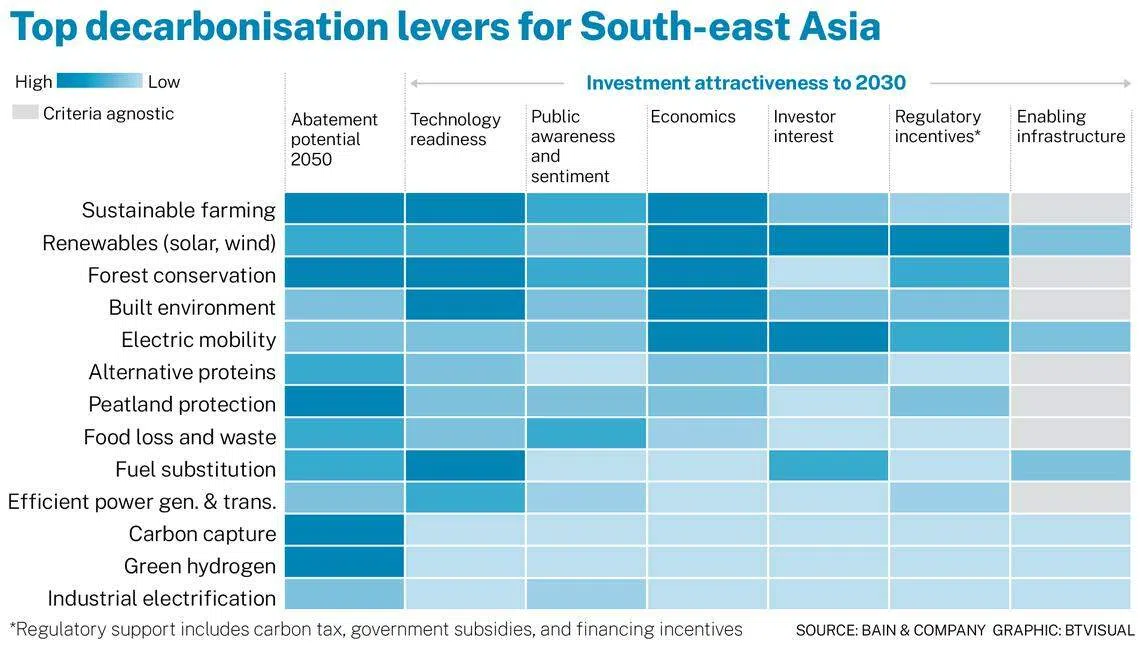
Bain & Co’s Jenny Davis-Peccoud said mitigation does not always require companies to pursue expensive and “wacky new technologies”.
Straightforward solutions, such as energy-efficient appliances and fertiliser-saving practices, should also be seen as a win for the bottom line, she noted. Depending on what sector you look at, it could be that 50 per cent or more of solutions are return-on-investment positive within a three- to five-year time horizon, she added.
Knaggs said that even if companies have to take on higher costs now, it would pale in comparison with projections of up to US$23 trillion in annual losses by 2100, if the world fails to correct its path in bringing down global emissions.
“The amount of funding required is immense. But it’s dwarfed by the costs if we don’t get this right,” he said.
Implementation challenges
Getting change at a system-wide level is a far tougher task than one company making the transition, however. One legacy problem is the long-term nature of energy planning. In Indonesia, for instance, coal-fired power plants are still being built as these investment decisions were made 10 years ago.
Fabby Tumiwa, executive director of Indonesian think-tank Institute of Essential Services Reform, said: “You need to plan to secure your future energy demand. If you look at how things were 10 years ago, nobody was talking about (the 2015-adopted) Paris Agreement… Cancelling all these plans instantly is not feasible.”
Likewise, when Asean set a target in 2015 to increase the proportion of renewable energy to 23 per cent by 2025 in its power mix, there was a lack of consideration of the need to set targets aligned to the Paris Agreement.
Governments can also take too long to make plans, Knaggs said. For example, the Vietnamese government’s national energy master plan for the decade that ends in 2030 was finalised only in July after several delays.
“A whole-of-system planning is really important. But when those sorts of plans sit around for a long time, they can really strangle investment because no one wants to really invest until they understand what the master plan looks like, what will be the prevalent technologies, and so on,” Knaggs said.
Implementation is further complicated by disagreements on how to allocate economic risks and benefits. Tumiwa noted that investors in Indonesian energy projects often find it hard to achieve an acceptable rate of return for their investments if they meet all the demands of power distributor PLN, which perceives its terms to be justified given that it is absorbing risk.
“Many investors feel that PLN tries to squeeze them and hurt their bottom-line finance of the project,” Tumiwa said. “And because it’s very difficult to meet PLN demands because PLN is a single buyer and so it has a monopoly, you take it or leave it. So it makes investors uneasy.”
Climate financing
Given the challenges, Yuki Yasui, executive director of the Asia-Pacific chapter of the Glasgow Financial Alliance for Net Zero, recognised that it will be tough to ensure every sector gets the investments it needs to decarbonise. Nevertheless, she believes it is possible with innovation and enhanced collaboration between public and private sectors.
To raise the use of blended finance to enable greater private-sector financing of green projects, Knaggs suggested that governments in emerging economies set up development investment corporations. This could de-risk projects for private sectors, or enable them to co-invest at market rates.
Sheryl Fofaria, head of social impact and philanthropy in South-east Asia at UBS, said countries and multilateral institutions need to provide critical support and investment certainty through public-private partnerships.
One example is the Monetary Authority of Singapore-led Asia Climate Solutions Design Grant programme, which helps identify blended finance solutions that mobilise private capital to sectors critical for climate transition and resilience in developing markets in Asia.
Bankers see no lack of capital seeking climate-related opportunities.
However, emerging economies, like those in South-east Asia, find it hardest to access private capital, even though green and transition finance are most needed in these markets, DBS chief sustainability officer Helge Muenkel pointed out.
Blended finance aside, the region needs clearer policies for transition activities, deeper public-private collaboration, and better management and optimisation of trade-offs to ensure a just transition, he said.
OCBC group chief sustainability officer Mike Ng said governments of jurisdictions where energy transition projects are to be implemented can lower private sector risks by improving regulatory and legal frameworks. Multilateral development banks can also offer financing and protection against emerging market risks, he added.
To UOB’s chief sustainability officer Eric Lim, a conducive environment for private sector finance includes clear country transition pathways, as well as alignment of supportive national and regulatory policies focused on sectors identified as the largest levers to decarbonisation.
“The presence of guidelines, guardrails and incentives will catalyse the development of high quality corporate transition plans, and enable greater confidence among financiers to deploy private funding,” he said.






