

Singapore banks can’t afford to miss out on coal phase-out despite immense challenges
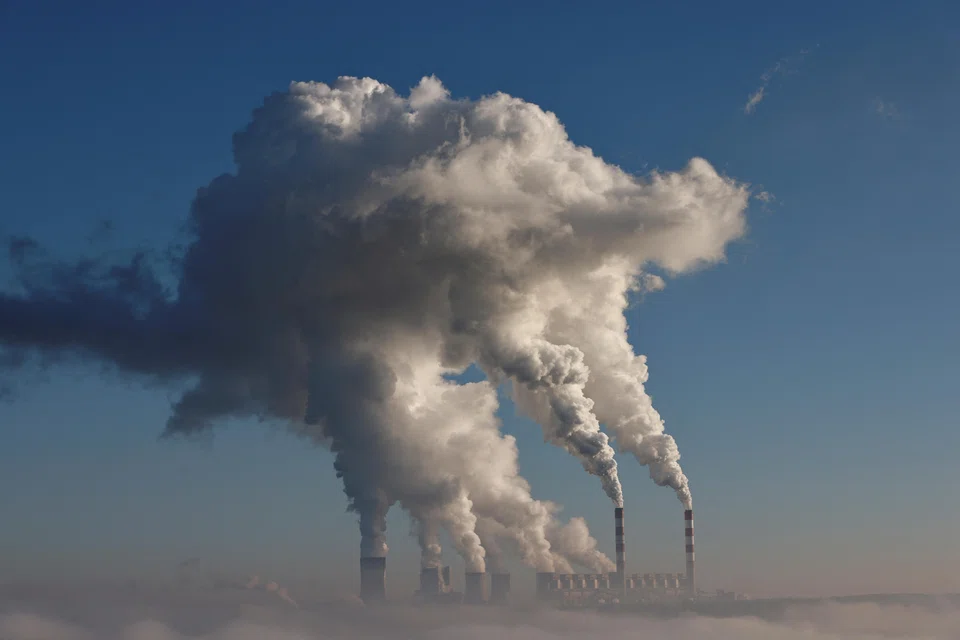
THE hot topic in South-east Asian sustainable finance these days is the early retirement of viable coal power plants, known in industry shorthand as coal phase-out.
Supportive money and regulation have coalesced around coal phase-out at an incredibly rapid pace over the past year, highlighting the immense environmental and economic promise of coal phase-out. Singapore’s three local banks might seem primed to take advantage of this trend, given the country’s status as a regional financing hub and the banks’ prominence in the regional project financing space. However, the reality is that a Gordian knot of complex issues still stands in their way.
The financial and energy sectors now recognise that it is not possible to achieve key climate goals without phasing out existing coal-fired plants. The need is especially great in South-east Asia, where the majority of energy in the region’s largest economies is still produced from coal.
There has therefore been a drive to enable the financing of coal phase-out projects. Just Energy Transition Partnerships (JETP) with Indonesia and Vietnam were set up in late 2022 to address this challenge by corralling multilateral public and private sector capital. The Asian Development Bank (ADB) also launched its Energy Transition Mechanism in June 2022 for similar purposes.
Crucially for the industry, regulators – including the Monetary Authority of Singapore – and industry standard setters are in the middle of establishing the key criteria for credible early coal phase-out projects. These criteria are being written into regional and national taxonomies – classification systems that define the economic activities eligible for sustainable financing – which provide essential guidance to lenders and investors.
The regional Asean Taxonomy already includes coal phase-out. Singapore is seeking public feedback on inclusion for its Singapore-Asia Taxonomy, as is the Asia-Pacific chapter of the Glasgow Financial Alliance for Net Zero (GFanz), an influential industry bloc.
The Singapore banks seem to sit in a sweet spot to take advantage of this upwelling of support for coal phase-out. Besides operating in South-east Asia’s financing hub, DBS, OCBC and UOB are also leading players in the regional project financing space.
Yet, there are signs that the banks have not been able to pounce so readily. For instance, none of the three local banks are part of the initial grouping of financial institutions involved in the JETPs for Indonesia and Vietnam.
Some hurdles are self-created. In 2019, all three local banks made public commitments to exit thermal coal financing. Those pledges were made at a time when there was growing international pressure on banks to help curb global warming by cutting financing for fossil fuels.
To finance early coal phase-out deals now, all three banks will have to review their existing coal policies to accommodate coal phase-out.
Beyond that, not all the obstacles are so easily within their control. For one, there are concerns of reputational risks, especially in the context of South-east Asia.
Getting involved in coal phase-out will lead to a short-term increase in the financed emissions for the three banks, which have set net-zero decarbonisation targets for 2030 and 2050.
While there have been calls to amend carbon accounting rules for banks to recognise financed emissions from coal transition as a positive activity as a way to get around this, some bankers have pointed out that they are still subject to the court of public opinion, at the end of the day.
Moral hazard also looms large among banks’ many considerations, as there is also a risk that their financing might inadvertently extend the lifespan of coal despite safeguards in the rules. William Attwell, director of climate research at Sustainable Fitch, estimates that coal power capacity within the region is currently around 210 gigawatts (GW) and is set to rise to 270 GW by 2030 if new plants in the project pipeline go ahead.
Banks might do all the necessary due diligence beforehand, but there are always governance issues around regulatory and political uncertainty that comes with investing in emerging markets, Attwell noted.
Then there is the big question of economic viability, which is still a hotly debated topic in discussions about early coal phase-out.
According to non-profit think tank Anthropocene Fixed Income Institute, there has been only one such project in the Philippines and three in Indonesia, including the Cirebon-1 coal plant in West Java with ADB. The other two Indonesian projects are not part of the Indonesia JETP.
In a recent report by Sustainable Fitch, the lack of consensus on what constitutes transition among the G7 countries, as well as the risk that financial institutions could prioritise profit over impact, are some of the implementation obstacles for Indonesia’s JETP.
But there is also no shortage of attempts at finding solutions to the myriad problems of economic viability. For example, one option being explored is the bundling of early coal phase-out projects alongside investments into renewable energy infrastructure to replace the capacity lost from decommissioning coal.
On balance, Singapore’s banks would do better to be part of the problem-solving part of the market than the part that is waiting for the solutions to be made.
For a start, the three banks risk losing precious market share if they cede this space to their competitors. Based on data from Refinitiv, all three banks were among the top 10 arrangers of project financing deals in South-east Asia over the first six months of 2023. The data includes all project financing transactions, including those that are not related to energy transition.
OCBC Bank was in fifth position, with its US$298 million of deals representing 5 per cent of the market. DBS came right behind with 4 per cent of the market on proceeds of US$238 million. UOB came in 10th, with proceeds of US$156 million accounting for less than 3 per cent of the market.
While the market for coal phase-out is still in flux, it is also a market with tremendous potential, and the three banks will be in a position of strength. The fruits may take some time to harvest, but they are worth taking the step forward and being a trendsetter in this emerging area of transition financing, instead of waiting for all the missing pieces of the puzzle to be found.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Can Mark Shaw bring Singapore back to Orchard Road and the movies?

Ex-Sembcorp Marine CEO Wong Weng Sun acquitted of charges in Brazil corruption case

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

