All eyes on Grab's financials ahead of US$34b SPAC deal
Industry observers wait with bated breath for information on the unit economics of Grab's core ride-hailing and food-delivery businesses
Singapore
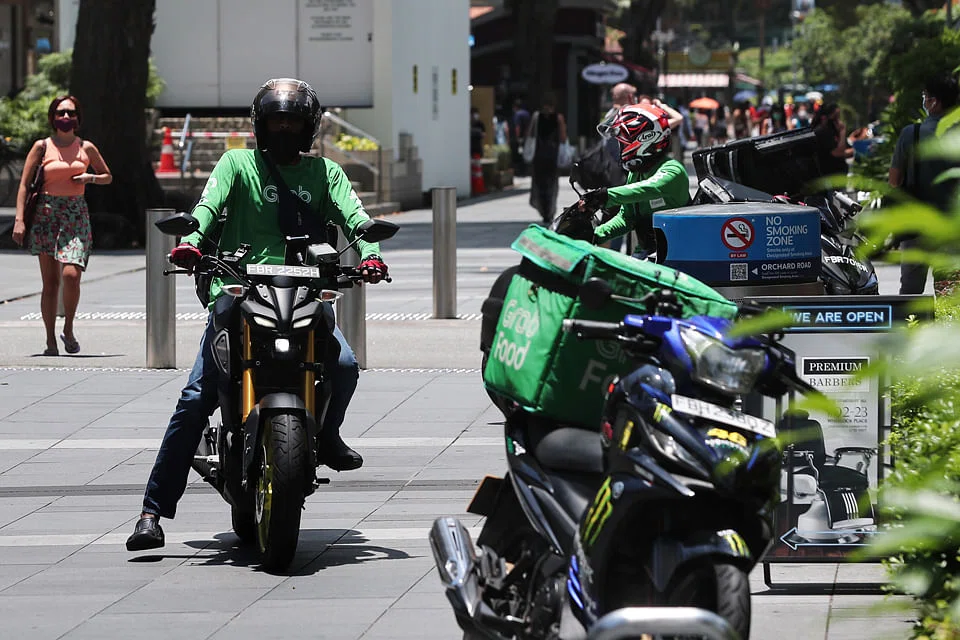
THE market is abuzz as Grab is expected to unveil a US$34 billion SPAC (special-purpose acquisition company) merger this week, paving the way for a public listing.
The move will also finally reveal the exact financial health of the company, which could set the tone for other South-east Asian tech listings.
Industry observers say that they will pay close attention to the unit economics of Grab's core ride-hailing and food-delivery businesses. They expect that Grab will tap the funds raised to continue to compete aggressively, although it may need to streamline its multiple verticals to better appeal to retail investors.
On April 10, Bloomberg reported that Grab is aiming to announce a merger with a US SPAC, Altimeter Growth Corp, as soon as this week. This could value Grab at over US$34 billion, in what could be the largest SPAC deal to date.
Reuters later reported that the merger would be announced on Tuesday, with sources putting the valuation at nearly US$40 billion.
The company is also said to be looking to raise about US$4 billion in a PIPE (private investment in public equity) deal, with the backing of Temasek and T. Rowe Price Group. BlackRock is also said to be in discussions with Grab, according to Bloomberg. Reuters reported that Fidelity International and Janus Henderson are participating in the deal.
Grab's SPAC merger could be less about a "big bang" listing, and more about raising another round of capital, said a lawyer who declined to be named. This could also bring liquidity for existing investors and the chance for retail investors to become investors in Grab, he added.
Grab's listing would finally "provide much needed intel for tech founders and investors in South-east Asia", said Shauraya Bhutani, a director at tech advisory firm North Ridge Partners.
"Given the lack of listed tech companies and opaque, arbitrary nature of private markets, the region has been operating with one eye shut when it comes to benchmarking valuations and business models against global peers," he said.
For now, few details about Grab's financial figures are known - except that it was reportedly last valued at more than US$16 billion. Total group net revenue grew about 70 per cent year on year in 2020; a Moody's report put Grab's cash reserves at around US$5.3 billion as at January this year.
According to the Bloomberg report, Grab's SPAC deal could give it an enterprise value of about 8.5 times its revenue.
Mr Bhutani believes that "while not cheap by most yardsticks, it is a fairly sober valuation" that Grab is gunning for. He cites how Chinese on-demand services giant Meituan is trading at 13 times revenue, and Uber, at about 10 times revenue. (see amendment note)
Sam Lee, partner and co-founder at financial services firm Paloe, similarly thinks that the targeted valuation is "in line" with tech peers pursuing a business across multiple verticals, such as Sea.
Market watchers say that they are particularly looking out for the growth thesis behind Grab - how exactly its core businesses fared during the Covid-19 pandemic, and what the future prognosis is.
Mr Bhutani of North Ridge said: "I am most interested in the unit economics of the ride-hailing and food-delivery verticals - are these models sustainable in South-east Asia or are they endless "loss leaders", which would mean Grab has to rely on other verticals such as financial services to be profitable."
He is also looking out for the exact revenue mix between food delivery, financial services and ride hailing. The US markets have generally given a higher valuation to the first two verticals, as in the case of DoorDash and Square, he said. In contrast, reception towards ride hailing has been tepid, as has been the case with Uber.
Market watchers also expect that Grab will tap its fresh firepower to defend its territory against other tech giants such as Sea, as well as Gojek and Tokopedia, which are pursuing a merger.
It also has to protect its turf from new entrants such as AirAsia and Shopee, who have made their respective forays into food delivery.
Acquiring smaller players could help drive up Grab's market share in South-east Asia, said Robson Lee, Singapore-based partner at US law firm Gibson Dunn. "This would be a faster way to leapfrog growth to capture market share, versus building up and developing tech in-house."
But the group would have to paint a disciplined growth story to investors. A clear and comprehensible path to profitability is what enables companies to continue raising money from retail investors, said Kerry Goh, chief executive officer of Kamet Capital Partners.
In Sea's case, gaming arm Garena is a stable cash-generating business, while e-commerce arm Shopee is a growth driver for which financial services can be built upon.
"This sort of focus gives the business a rock-solid foundation and path," said Mr Goh, who noted that Grab lacks a highly profitable core business to finance its other growth verticals.
Profitability is "critical" for Grab to become sustainable and to withstand challenges from newcomers to the market, noted Su Lian Jye, principal analyst at global tech market advisory firm ABI research.
While investor reception towards Grab's business prospects is yet to be seen, some reckon that the company is blessed with a first-mover advantage.
Said Mr Bhutani of North Ridge: "A Grab listing will provide much-wanted exposure to South-east Asian tech to a wide range of global investors, institutional and retail. We know that Gojek, Tokopedia and Traveloka have their own plans to go public, but with Grab front-running them, it will get a lion's share of the investor appetite."
- Garage is BT's startup vertical. Read more news, analyses and opinions at bt.sg/garage
READ MORE:
- Grab's US$40b SPAC talks signal race against Gojek-Tokopedia
- Grab joins five other regional startups gunning for IPO
- The specs of SPACs
Amendment note: The article has been amended to reflect the change in Meituan's name.