

InstaReM begins major shift towards SME market
Consumer-focused remittance startup to launch SME platform and rent its tech infrastructure to other businesses
Claudia Chong
Singapore
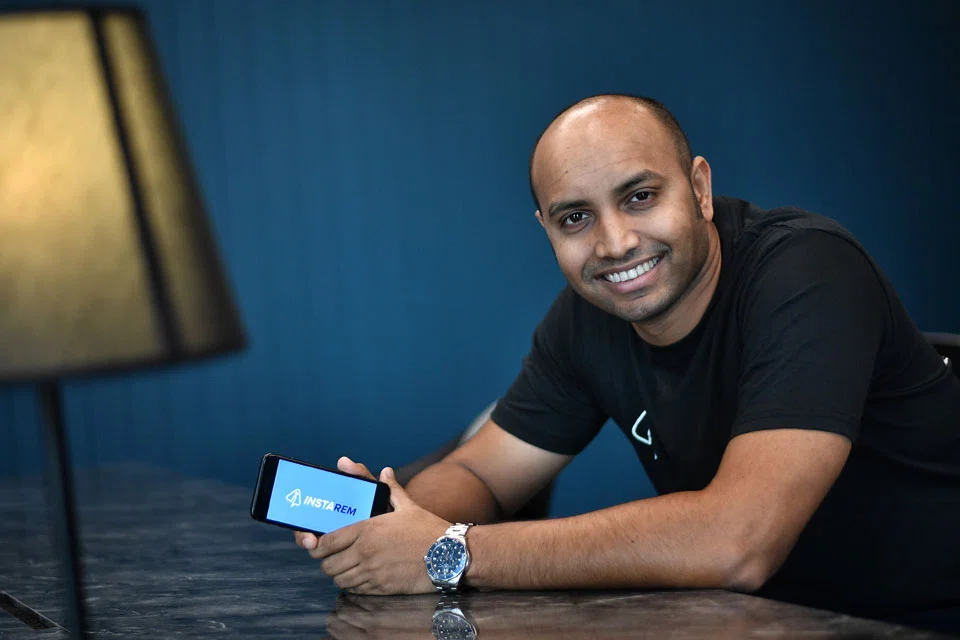
FOR the next stage of its evolution, consumer-focused remittance startup InstaReM is going after the potentially lucrative small and medium enterprise (SME) market.
And InstaReM is pulling out all the stops for the pursuit. It is rolling out an SME platform by year-end to help businesses manage accounts, and will open up its technology infrastructure for companies to use, in addition to previously announced plans to set up a digital wholesale bank in Singapore. It will even change the company name to reflect its new strategy, chief executive Prajit Nanu told The Business Times.
Mr Nanu argued that traditional banks are adept at serving SMEs locally, but their offerings fail to carry over once the businesses start to expand across borders. At the root of the problem are the lenders' core banking systems that support transactions and retrieve customers' banking data, and stringent requirements attached to existing products for small businesses.
"Both of these aspects are not flexible," he said. For example, InstaReM needed a corporate credit card and had a few million dollars as a deposit with a local bank. They were asked to create a new fixed deposit linked to the new credit card according to the rules of the existing product.
"It's extremely painful," Mr Nanu said. "If you want a customised product, banks will give you what they have as a stack. So the opportunity we see is to enable SMEs to go outside of Singapore as well as help them to create a technology-related process. Today, everything is extremely manual."
InstaReM is targeting what Mr Nanu described as one of the biggest pain points for SMEs growing abroad: collecting payments in multiple markets.
Local businesses that currently receive payments in foreign currencies from overseas customers have to set up multicurrency accounts with their local banks to avoid foreign exchange costs. They also have to manually reconcile payments against invoices.
InstaReM's solution is a platform that allows businesses to upload invoices and customers to pay using their choice of payment method. Once payment is received, the platform can automatically reconcile the collection with the correct invoice.
The company is also building a network of virtual bank accounts to allow customers to pay via a local bank transfer. It can already operate virtual accounts in currencies such as the US dollar, pound and Hong Kong dollar.
All these will take place at no cost to the SME, Mr Nanu said. The SME platform will also offer a range of functions including streamlining payments and automating business projections.
A second pillar of the new strategy is to rent out InstaReM's technology and infrastructure to other businesses.
The startup is gearing up to open the doors of its developer lab in October, in a 2,000 square foot space in Hong Leong Building. Through the lab, SMEs and startups will be able to use InstaReM's existing infrastructure to do things such as build a remittance arm or a payments business, without needing to secure their own licences or build their network from scratch.
"The idea is that you can scale to multiple markets, and the way to do it is to use our platform," said Mr Nanu.
The startup partnered New York-listed commerce tech solutions firm First Data for the capability to issue cards for a number of use cases, such as employee travel expenses, payroll and vendor payments. Earlier this month, InstaReM launched an application programming interface (API)-based platform for companies to issue their own branded cards.
Because InstaReM's tech systems are already compliant and licensed, and the startup has already built its own network of banks, payment processors and vendors, all businesses have to do is develop their own consumer-facing front-end technology. InstaReM then executes the transactions involved.
Access to all of InstaReM's systems will cost S$99; the startup then charges a fee for each time a system is used. For instance, in the case of card issuance, fees are charged for every time the company issues a card, performs know-your-customer checks on a user, and collects money from the acquiring system.
InstaReM will also take a cut of the interchange revenue, which will be pegged to the volume of transactions. As volume increases, the percentage cut goes down.
The firm, which announced in March that it raised US$41 million in Series C funds, is also looking for established financial institutions to partner for lending as it sets out to build a marketplace-based lending platform. The marketplace will allow businesses to compare lending products and rates.
This new business direction is a notable shift for InstaReM, which has carved a name for itself in the consumer remittance world by offering zero-margin mid-market rates, with typical fees ranging from as low as 0.25 per cent to one per cent.
But the opportunities in the business-to-business (B2B) space are too large to ignore. According to McKinsey, cross-border transaction value for accounts payable by SMEs was US$6-7 trillion in 2017. It is poised to grow by about 5 per cent per year from 2017 to 2021. Transaction value for cross-border marketplace payouts to SMEs was US$5- 8 trillion in 2017, and set to grow at 5-10 per cent per year until 2021.
InstaReM is projected to handle about US$5 billion in transactions this year, of which about 40 per cent will be directly and indirectly accounted for by SMEs. As its product suite expands, it expects SMEs to account for about US$5-7 billion in annual transactions by 2022.
The Singapore digital wholesale banking move will be a testbed for the startup, said Mr Nanu. If it works out, InstaReM plans to set its sights on Malaysia next, where regulators are closely studying virtual banking.
Mr Nanu said that being regulated as a bank, with certain guidelines and financial requirements, is an important step for the company. "We want businesses to start transacting with us on a day-to-day basis. For that, you need trust and credibility, which a virtual bank provides."
InstaReM is backed by investors including Vertex Growth Fund, Rocket Internet and MDI Ventures, the venture arm of Indonesia's Telkom. It has raised US$59.5 million so far. The company is projected to turn a profit by the first quarter of 2020 before heading for an initial public offering in 2021.
To top it all off, InstaReM will undergo a rebranding to better reflect the new strategic direction, including adopting a new name, which will be revealed at a later date.
The new name is not InstaBanK, Mr Nanu assured BT.
READ MORE: Temasek-backed Nium to expand in US ahead of potential listing
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Singapore judge raises doubts iron ore trader Radiant World is owed US$1 billion

