

Singapore Budget 2018: A quiet but seismic shift in Singapore's approach to borrowing
Govt mulls providing guarantees for long-term borrowings made by statutory boards and govt-owned firms to build critical national infrastructure
Singapore
THE Singapore government's conservative approach to spending is well known - it has not borrowed to finance its expenditures since the 1980s.
But Budget 2018 seemed to signal a potentially seismic shift in this way of thinking. As Singapore's infrastructure needs grow, the option to use debt to finance big-ticket expenditures is back in the limelight.
In his Budget speech, Finance Minister Heng Swee Keat said that the government is considering providing guarantees for long-term borrowings made by statutory boards and government-owned companies to build critical national infrastructure.
Statutory boards and government-owned companies already use bonds to finance infrastructure projects. For example, statutory boards such as the Housing Board, Land Transport Authority and PUB have issued bonds to finance public housing, rail and water infrastructure.
This spreads the cost of major investments over more years and helps boost Singapore's bond market, Mr Heng said. But such borrowings will likely be done on a bigger scale in the coming years.
In an interview with The Straits Times a day after the Budget, Mr Heng said that Singapore's upcoming infrastructure spending needs are at levels not seen in more than 30 years.
"In the earlier years of our development, we borrowed from a variety of sources, including multilateral development banks such as the World Bank, Asian Development Bank and so on, to fund some of these major long-term infrastructure developments," he said.
"But as our economy grew and the tax collection was strong, we stopped borrowing some time in the mid-1980s for our major infrastructure projects. Now, we are coming back to another major spike in our infrastructure needs."
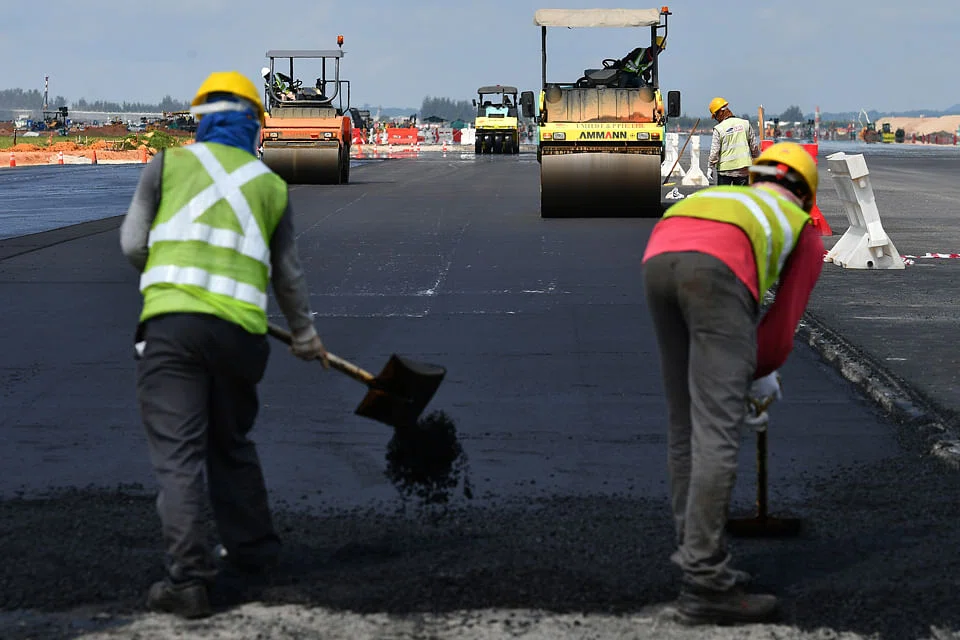
These include projects such as Changi Airport Terminal 5, the Kuala Lumpur-Singapore High Speed Rail and the Cross Island Line.
The government is also considering the use of Singapore's national reserves to guarantee such borrowings. But this would be done on a case-by-case basis, Mr Heng said.
Any such use requires the government to seek the approval of the President and the Council of Presidential Advisers (CPA).
"We are not (tapping into) the past reserves in any way but we're using the reserves to provide a guarantee. The question is, what sort of safeguards would need to be put in place. That will have to be discussed very carefully with the President and the CPA," he added.
Fairer financing option
Infrastructure investments tend to be "lumpy", requiring hefty upfront investments for benefits that will be enjoyed only many years later.
Borrowing distributes the share of funding more equitably across generations instead of having the current generation foot most of the bill.
This opens an alternative source of funding for costly infrastructure projects, in lieu of relying on tax revenues or dipping into the reserves.
Associate Professor Simon Poh from the NUS Business School's department of accounting noted that as it stands, taxes as well as net investment returns contributions are only enough to fund recurrent increases in health care, security and other social spending.
Maybank Kim Eng economist Chua Hak Bin said that the move "appears to represent a slight shift in the government's approach". "The shift may be because historically the government always has had sizeable fiscal surpluses to fund infrastructure needs," he noted.
Besides spreading the burden of financing major projects more equitably across generations, revenue from the completed infrastructure - whether airports or high speed rail - can also be used to service and repay the debt. "This is preferable to taxing the current generation to pay for the full cost of the infrastructure spending," Dr Chua added.
The announcement has already set bond market analysts and investors abuzz. "The market is definitely excited about this, and looking forward to the new issues," said UOB head of markets strategy Heng Koon How and rates strategist Victor Yong in a research note.
"Over the years, there has been consistent demand from life insurance companies and asset management companies for high quality Singapore-dollar denominated local bonds for them to invest in . . . so as to match their longer-term Singapore dollar liabilities."
Mr Heng said in his Budget speech that a government guarantee on these borrowings will enhance the confidence of creditors.
In addition, a guarantee "is another way to use the strength of our reserves to back our infrastructure projects, without directly drawing on the reserves", he said, adding: "The reserves can then remain invested to generate returns."
The possibility of using the reserves to guarantee these borrowings raises questions about the impact on Singapore's sovereign credit rating, as well as the government's ability to make good on these guarantees in the longer run.
After all, Singapore is one of the few economies in the world that enjoy a "triple-A" credit rating across all three major rating agencies - Standard and Poor's, Moody's and Fitch Ratings.
Minimal impact
But credit ratings analysts said that the impact will be minimal. In fact, such a move means that the government could have more scope to access the capital markets without actually adding debt to its balance sheet.
"Given its conservative approach to fiscal management, the government is unlikely to provide guarantees for debts or projects that would likely materialise on its balance sheet," said Christian de Guzman, Moody's Investors Service vice-president of sovereign ratings.
"Put in another way, such guaranteed debts pose only low and contingent risks to the government's fiscal position."
Tan Kim Eng, a senior director for sovereign ratings at S&P Global Ratings, said that debts guaranteed by the government might be treated as the government's own debt in some cases.
"This may happen if we believe that the agencies or companies that borrow these debts are unlikely to generate sufficient cash flows to repay the debt. Consequently, there is a high chance that the government will have to repay it one way or another."
Mr Tan said that the government guarantees will probably be granted to "projects and entities that are likely to repay the debts concerned with their future cash flows".
"Regardless, given the Singapore government's strong credit metrics, we are unlikely to see any rating impact arising from the government's move to provide such guarantees even if we were to treat them as government debts," he added.
This would not be the first time that the government guarantees debt used to finance infrastructure projects. It guarantees debt instruments issued by Clifford Capital, a project financing firm funded by Temasek and other financial institutions, whose mandate is to promote the role of Singapore-based companies in infrastructure projects within the country and abroad.
But the government itself does not borrow to fund its expenditures. Instead, securities are issued for reasons unrelated to the government's fiscal needs.
One type of debt regularly issued is Singapore Government Securities, which are used to develop the domestic debt market.
The other is the Special Singapore Government Securities, bonds issued to the Central Provident Fund (CPF). The bonds issued in this case are to pay the CPF interest rates that CPF members get on their savings.
The Finance Ministry says on its website: "All borrowing proceeds are therefore invested. The investment returns are more than sufficient to cover the debt servicing costs."
Under the Constitution, the government cannot spend the monies raised from both sets of securities.
Stephen Schwartz, the head of Asia-Pacific sovereigns at Fitch Ratings, said that Mr Heng's announcement "does not . . . have near-term implications for Singapore's sovereign credit rating, given the underlying strength of its public finances".
"Ultimately, any rating impact would depend on the specific mechanisms, safeguards and size of government guarantees. But we do not currently expect that such financing initiatives would on their own undermine Singapore's 'AAA' creditworthiness," he added.
Details about the bonds - including the potential size of these offerings and the format that they will take - are still scarce. But the announcement has already raised some eyebrows, given Singapore's reputation for fiscal conservatism.
The move is not a departure from this mindset. Rather, it is an acknowledgement that as the country's spending needs grow, policymakers will have to relook some sacred cows - including long-held attitudes towards debt.
After all, such borrowings are a standard part of a government's fiscal arsenal in most other parts of the world. The challenges of raising revenues for growing needs is not unique to Singapore.
The government has always maintained a prudent approach towards the country's finances, which means that it will not grant guarantees lightly. The projects financed using debt guaranteed by the government should be large, multi-year investments expected to yield long-term returns.
As long as this principle is adhered to, this move will be positive for the country's fiscal health.
For more Budget 2018 stories visit bt.sg/budget18
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
China’s Pinglu Canal likely to benefit Singapore, other South-east Asia ports in the long term
Suntec Reit to increase Singapore focus, sell three Australia properties

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

