

Be a smart traveller
Five tips to help you manage your finances while on vacation.
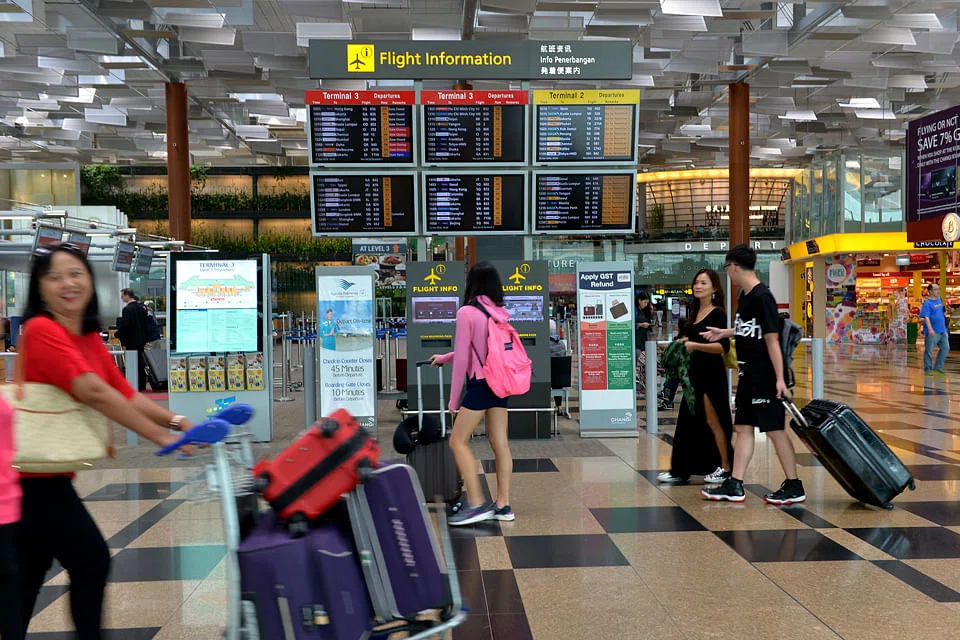
WHEN I was much younger and wanted to buy a very expensive toy, my grandma told me gently: "Money does not grow on trees". I retorted: "Wouldn't it be great if everyone had a money tree, then everyone will be able to buy all the toys they want?"
"Of course not," she said, to my great surprise. "Some people will take care to grow their tree, but many others will neglect theirs."
Indeed, our wealth is like a money tree. The goal of personal finance is not only to grow our tree through investments, but also to ensure that our tree is fundamentally strong enough to tide us through rainy days - through savings - while ultimately being protected from thunderstorms through insurance.
Then, we can enjoy the fruits of our labour.
The concept of personal finance can be applied to everyday life, whether we are working, schooling or even holidaying.
That is right, even while on holiday! Here, we outline five simple yet practical skills on managing your vacation finances.
One: Set a budget
Setting an amount that you are willing to spend for the entire trip will help manage your expectations, especially if you are paying with credit cards.
Many studies show that consumers tend to overspend when paying by credit as compared to cash.
The trip budget encompasses the costs for transportation, accommodation, meals and all activities, and can help you decide the places to go and the length of your holiday.
You can refer to travel forums and blogs in determining the budget.
Breaking down the budget on a day-to-day basis can help you track your spending effectively. This can be something as simple as committing to an average spending per day, or to plan a detailed itinerary, with a budget, of personal shopping at retail boutiques, transportation and entrance fees to places of interest.
Budgeting is most effective in curbing excessive spending when you can mentally compute and compare whether you should proceed with on-the-spur purchases.
If you can, appoint a budget controller within your travelling party who is willing to tally up the expenses spent on the trip.
When travelling with friends, everyone can contribute equally to a "money pot". Use this shared pool of money to pay common expenses such as meals and tours at places of interest.
The "pot" also reduces the exposure of cash to the public, especially in places where theft and robbery are more prevalent. Do not be complacent when travelling, for pickpocketing might be common in some developed cities too.
Two: Cashback and loyalty points
Generally, transportation works out to be one of the biggest cost items for a holiday. Fortunately for us, the Internet has made it a lot easier for us to compare fares.
There are even some websites that specialise in fare comparison, bringing greater cost savings to us consumers. On top of that, you can make use of cashback functions present in some credit cards, or through the use of websites.
Cashback websites are relatively new in Singapore but they are gaining popularity among online shoppers. These cashback websites tie up with online retailers to offer more cash savings, which can be significant if you are paying for your family.
You should note that the cashback is processed only after your trip is completed, and that cashback can only be cashed out after a minimum amount is attained.
To enjoy greater savings, you can sign up for relevant loyalty programmes.
A good example is a frequent flyer programme. It is important to note that different flight fares equate to different frequent flyer miles, sometimes known as booking class.
This means that if air tickets are bought at a hugely discounted fare, there is a chance that frequent flyer miles might not accrue.
Nevertheless, being part of a loyalty programme could provide subscription to member-exclusive fares, flight upgrades, and redemption of free air tickets.
The accumulation of frequent flyer miles can also be accelerated with the use of credit card points.
Three: Hedge against unexpected events
Travel insurance is often excluded from our itineraries since they add costs to our budget. But how sure are you that the trip is going to be smooth sailing?
On a backpacking trip with three of my friends to Myanmar, my friend was stricken with diarrhoea so serious that he could not participate in the planned activities.
He had to visit a doctor and was told that if his condition got worse, he would require immediate medical attention that was only available in more urbanised areas of the country, and probably had to shorten his trip. Thankfully we purchased travel insurance for ourselves and managed to claim the expense.
A different friend of mine travelled to Bali and her return trip was disrupted due to volcanic ash clouds which caused the airport to close. Fortunately for her, she managed to claim a sum of money to cover her expenses incurred as a result of the inconvenience.
The bottom line is you never know when you might need the insurance. For frequent travellers, travel insurance could already be free on credit cards. Purchasing an annual plan could provide better coverage at a cheaper premium for frequent travellers.
For the occasional traveller, single-trip plans can be purchased through the Internet, mobile apps and even at ATMs.
The terms and conditions laid out in the policy would explain what is insured for and what is not covered. They should be noted before you buy the policy, especially if you plan to engage in high-risk activities which might be excluded from ordinary plans such as scuba diving or skydiving.
You should buy travel insurance once the trip is confirmed and not wait till the last minute. Some plans would cover disruptions to your trip prior to departure, such as the serious illness or injury of your family member.
Four: Currency exchange
Aside from finding a money changer that offers the best exchange rate, it is important to know the additional charges that are due on both debit and credit cards when you transact overseas.
One of them is the exchange rate difference.
When you spend in foreign currencies on your card, most banks convert the amount to US dollars before converting them to Singapore dollars. These exchange rate fees could add up quickly if you are not careful.
Another charge is the international transaction fee. This is on top of the exchange rate difference for processing the payment transaction overseas.
Not all cards are charged the same way; some may charge a certain percentage of the transaction, some may be a flat rate. Do check with your card issuer if you are unsure of the charges involved.
Withdrawing local currency at overseas ATMs can be another life-saver should you need local currency quickly, but only if the cards' magnetic strip has been activated for overseas use. Most Singapore banks turn off this function by default to reduce security risks.
Do note the transaction fees involved from withdrawing local currency, especially when you are withdrawing from a different bank from your card issuer. Banks often waive off charges for their own ATMs.
Do activate cards for overseas usage if you envisage the need might arise.
Five: Enjoy tax refunds
Smart travellers know that tourist tax refunds can help save money. It is imperative to know the terms and conditions laid out for transactions to be qualified as tax-free.
The procedures of tax returns differ among countries. Some could be as simple as collecting receipts. Others may require refund forms per transaction. If you are careless and miss out on any step, it may cause you to lose your tax return privilege.
Some airports may have long queues at their tax refund counters, so be on the lookout for alternate places to claim tax refunds.
Generally, you will receive your tax refunds in cash in the local currency. However, if you do not wish to receive cash, you may be able to choose to credit the tax refunds to your credit card based on the prevailing exchange rate.
If you have leftover local currency, you may choose to keep it or exchange it back to your home currency.
Some currencies are more volatile than others. If you hold your leftover local currency till the next trip a few months or years down the road, it might be worth less than what you first exchanged it for.
Conclusion
As the year draws to an end, many of us are looking to have a holiday as a break from our normal routine.
Recall the last time you felt excited researching for a trip, and joyfully strolled down the aerobridge as you boarded the plane.
But as soon as you returned from the trip, you started to feel the pinch in your wallet, because you just recalled that you spent way above what you expected for the trip.
Of course, these pinches could be less painful if all trip expenses were within budget.
Remember these five tips, for they will help you cherish and nourish your money tree!
Like us on Facebook at Citi-SMU Financial Literacy Programme to get more tips on financial literacy.
GET STARTED NOW
Be a young investor
Do you aspire to be a successful young investor? Are you keen on taking the first step towards achieving that? The BT-Citibank Young Investors' Forum is no typical page extracted from a financial textbook. This forum will present step-by-step guides on how to start investing, feature stories of peers who have made some headway with their investments, and provide answers to your burning questions on investing. First, we need you to invest - not your money, but your time - in reading The Business Times every Monday. You need not be an armchair reader either - write in to btyif@sph.com.sg now!
TRENDING NOW

Philippine power giant First Gen rebuffs foreign offers, plans up to US$2.6 billion in expansion
Vietnam’s data-centre investment rush faces reality check on power and site constraints
Singapore should prepare for prolonged haze until November, says Grace Fu
Is stagflation returning? That mostly depends on the Iran war

