

Asean CPO stocks battered as palm oil price tanks; further decline expected in H2
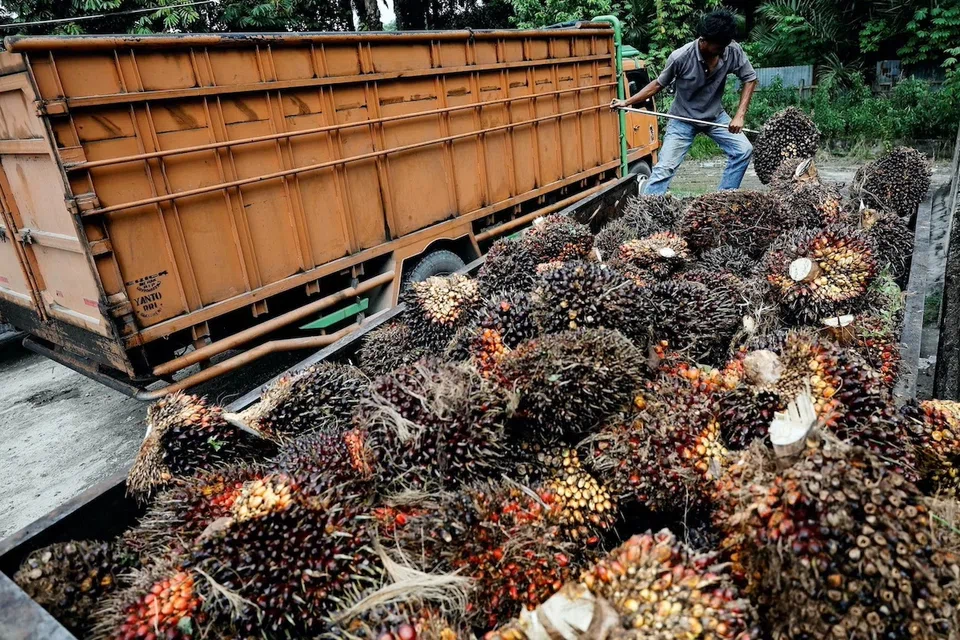
CRUDE palm oil (CPO) stocks in South-east Asia are now going through a sell-off in the wake of a drop in the commodity’s prices, after having enjoyed a stellar run amid what analysts term a “perfect storm” of factors like tightened supplies, Indonesia’s export ban and the Russia-Ukraine conflict.
In the Singapore, Malaysia and Indonesia markets, listed palm oil counters have seen their share prices fall across the board since Apr 29, alongside a decline in CPO futures. As at market close on Tuesday (Jul 6), the 22 CPO stocks listed on the 3 exchanges were in the red.
The price of CPO futures contracts on the Bursa Malaysia Derivatives market has fallen 41 per cent over the same period. Some contributing factors include concerns over slower global economic growth and expectations of higher palm oil output in Indonesia.
CGS-CIMB analysts in a Jul 5 report noted that the bulk of spot CPO price declines took place from Jun 10, when Indonesia provided more clarity on the export process as it replaced the export ban with the domestic market obligation (DMO).
The analysts estimate that export policy changes throughout H1 this year may push up Indonesia’s palm oil stocks to as high as 8 million to 8.5 million tonnes at end-June, up from 6.1 million tonnes at end-April and 3.6 million tonnes at end-2021.
They added: “We are of the view that to clear the excess stockpile, Indonesia’s palm producers will need to entice buyers by lowering CPO prices - causing local and international CPO prices to fall significantly in recent weeks.
“We think CPO prices could stay weak during the adjustment period and trade at larger discounts over competing edible oils until Indonesia’s palm oil stocks fall to the 4 million to 5 million tonnes level. Meanwhile, we expect Malaysia’s palm oil stocks to rise due to competition from Indonesia palm oil.”
There have also been reports that some palm oil millers in Malaysia have temporarily halted production on the back of the plunge in CPO prices.
“There have been news reports that some Malaysian millers intend to stop purchasing fresh fruits from farmers and halt milling operations. We think that these stoppages are likely to be temporary as prices remain high relative to historical levels,” said Akash Gupta, director at Fitch Ratings’ Asia-Pacific corporates team.
Among the 3 countries, Malaysia’s CPO stocks saw the worst damage. Ta Ann Holdings’ share price took a hit of slightly more than 40 per cent. Another 4 counters - namely Sarawak Plantation, Boustead Plantations, Genting Plantations and Kuala Lumpur Kepong - each saw their share price fall more than 30 per cent since Apr 29.
In Singapore, pure CPO plays such as Bumitama Agri , First Resources and Kencana Agri are among the biggest decliners, booking share price losses in the range of 23.1 per cent to 29 per cent over the period.
Diversified agribusiness giant Wilmar International’s share price was more buffered, falling 9.7 per cent. Indonesia-based oil palm producer Global Palm Resources also saw its share price slide 4.8 per cent.
In Indonesia, Maybank analyst Ong Chee Ting described the situation as “worrisome” as the country’s domestic net CPO average selling price was quoted at 8,000 rupiah per kilogram, or about RM2,374 per tonne on Jun 24.
This price is “fast approaching the breakeven costs of some companies”, he said.
Among the Indonesia-listed CPO stocks, Astra Agro Lestari saw its share price drop 24.8 per cent since Apr 29, while Dharma Satya Nusantara shed 21 per cent. Sinar Mas Agro Resources and Technology, meanwhile, lost just 5.4 per cent.
Although current CPO prices mean that good margins can be made, Ong said Malaysia-based growers are likely to benefit more, while Indonesia-based growers will be hurt by the burdensome export taxes, DMOs and the slow issuance of export permits.
“The recent sharp decline in CPO price can be rather disruptive to business. There is also a rising risk of default by buyers, or buyers seeking to defer some shipments of higher priced palm oil locked in earlier,” he added.
Looking ahead, investors should brace for a bigger decline in prices. Fitch’s Gupta is expecting Malaysian benchmark CPO prices to decline below US$1,000 in H2, driven by higher palm oil output in Indonesia.
Global vegetable oil output is also expected to jump in 2022 to 2023, which will pressure CPO prices, he said.
Maybank’s Ong said the La Nina weather pattern has brought ample rainfall to Malaysia and Indonesia over the past 2 years, which provides a conducive environment for palm oil crop recovery in 2022.
“In response to global high prices of oilseeds and disrupted trade due to protectionist measures and Russia-Ukraine war, we expect planting acreage to be boosted the world over,” he said.
“With favourable weather, we should anticipate record harvest of oilseeds over the next 12 months.”
For now, Maybank prefers “integrated players with relatively lower cost of production”. These companies typically exhibit greater earnings resilience compared to pure growers given the latter’s earnings are more sensitive to CPO price movement, Ong said.
Such companies include Kuala Lumpur Kepong and IOI Corp. The brokerage also has a “buy” call on Singapore-listed Bumitama Agri.
Apart from KL Kepong, CGS-CIMB also has Wilmar as a top pick for the sector.






