Asean palm oil listcos battle revenue, profit dips on sliding CPO prices
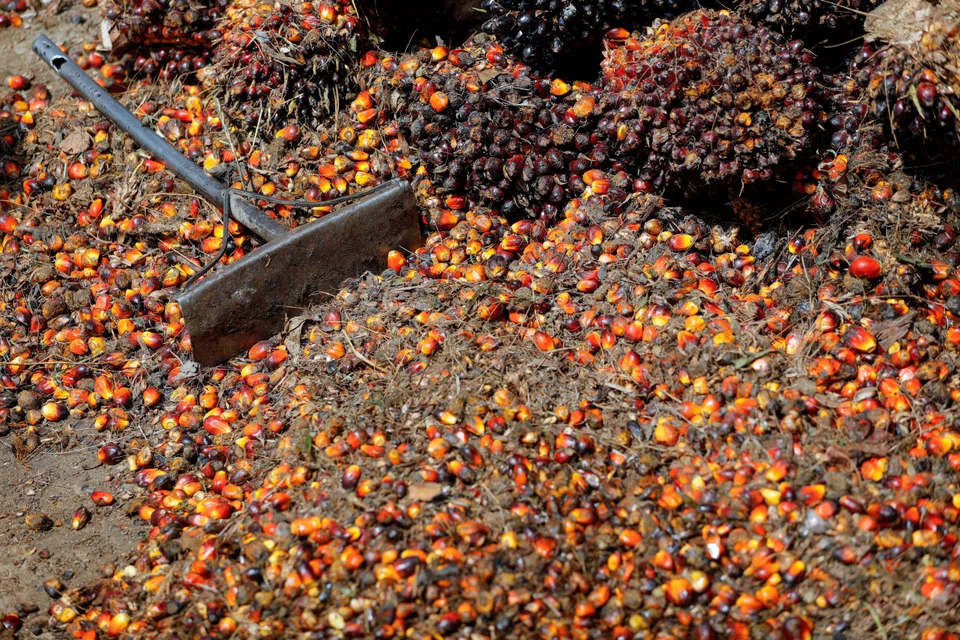
REGIONAL palm oil players took a hit from weakening crude palm oil (CPO) prices in the first quarter of the year ended March, with several reporting a decline in revenue and net profit figures. Market watchers warned that these troubles could continue in the second half of the year, amid weaker industry dynamics.
Palm oil futures have fallen year to date, softening after a prolonged period of strength last year.
BMI, a unit of Fitch Solutions, noted that CPO prices averaged RM3,872 (S$1,135) per tonne this year as at May 19, nearly 20 per cent lower than they were at end-2022.
After rising 2.6 per cent on a month-on-month basis in February, average palm oil futures prices have declined in each successive month. The commodity fell 2.6 per cent in March and 5.3 per cent in April; this month thus far, it has fallen 3.9 per cent, BMI noted.
Singapore-listed palm oil producers that released a business update for the fiscal quarter ended March did not escape unscathed. Pure palm oil players Bumitama Agri , First Resources and all booked lower revenue on the back of lower average selling prices and the moderation in CPO price. The companies’ figures were also hit by lower output and higher production costs.
Companies also cited factors such as ongoing geopolitical tensions and uncertain weather conditions as reasons for the poorer showing.
Integrated agribusiness giant Wilmar International , which also has operations in sugar, edible oils and consumer products, was also hit. The company was relatively buffered in terms of revenue though, reporting only a 3.8 per cent year-on-year decline, as its business segments all reported a higher volume of sales.
Although the group said its palm oil refining margin was “poor”, its sugar milling and merchandising unit did well with higher sugar prices. Oilseed crushing did better due to “higher volume and good coverage of raw materials”, while the food products unit booked an overall increase in volume of sales from higher medium-pack and bulk-product sales, particularly in China.
It was a similar story across the region, with Malaysia-listed counters KL Kepong and Boustead Plantations reporting declines in revenue and profit for Q1 ended February. Sarawak Oil Palms, too, posted declines in both top and bottom lines for Q1 ended March, due to lower realised selling prices of palm products coupled with higher production costs.
Over in Indonesia, Dharma Satya Nusantara reported growth in revenue and earnings for Q1 ended March, but its gross profit margin for the palm oil segment shrank to 26 per cent from 29.9 per cent. Fresh fruit bunch (FFB) production for the quarter rose 27.9 per cent to 528,400 tonnes amid an increase in production from its nucleus and plasma plantations.
London Sumatra and Sinar Mas Agro Resources and Technology reported upticks in revenue, but higher costs of production crimped their profit figures; Astra Agro Lestari reported declines in both revenue and profit figures.
An RHB analyst said there were still “some positive movements” in share prices of CPO players despite the weakening commodity prices. This was evident particularly in some of the Malaysia-listed big cap planters, but less so for the mid-cap planters listed in Malaysia, as well as planters listed in Singapore and Indonesia.
“The movement was on the back of fears of El Nino coming and expectations that CPO prices (and share prices) could see some re-rating, similar to what was seen in the rubber glove companies,” said the analyst.
The analyst noted that share price movements were, however, not uniform. Diversified players seemed to pique the interest of investors more than smaller players could, “given the expectation that integrated players are less susceptible to CPO price downturns in terms of earnings impact”.
More troubles are expected for the palm oil sector, with analysts noting that the risk of El Nino is rising.
RHB’s analyst also mentioned improved supply on the back of the end of the La Nina phenomenon in South America, good crop planting progress in the US, the extension of the Russia-Ukraine grain deal, as well as expectations of a better crop year for Malaysian planters on the back of the ending of labour shortage woes.
“Demand also seems to be lacking at the moment, with some major importers still holding high inventory levels,” said the analyst.
Typically, confirmation of the El Nino would bring about a spike in CPO prices as the market braces itself for supply disruptions. RHB’s calculations, however, indicate that even a 20 per cent spike in CPO prices would bring the commodity’s price to just over RM4,000 per tonne.
“This would mean average prices for 2023 would still be in the RM3,800 to RM4,000 per tonne range, which is where consensus projections are already. This means there may not be that much upside for average prices and earnings upgrades (this year),” said the analyst.
BMI analysts said palm oil prices are likely to see further downsides in the immediate term, mainly from the demand side. The analysts said prices will be pressured by continued soft import demand from mainland China and India.
There is also a continued decline in the price of alternative edible oils such as soybean oil, which will keep a lid on palm oil consumption and prices, they added.
In the longer term, BMI expects palm oil prices to soften between 2025 and 2027. Over that period, they are expecting average annual prices to slide from RM3,000 to RM2,200 per tonne, since global palm oil production surplus is slated to widen.
RHB has kept its “neutral” stance on the sector. Its top picks are Singapore-listed Wilmar and Golden Agri, and Malaysia-listed IOI and KL Kepong.
Maybank, meanwhile, has also kept its “neutral” call on the regional plantations sector, saying that El Nino’s impact on CPO price could be “more subdued” this time round.
“We believe immediate macro concerns are bigger headwinds now, and ESG (environmental, social and governance) concerns may resurface if the haze returns,” said analyst Ong Chee Ting. The research house’s preferred picks are KL Kepong, First Resources and Bumitama Agri.