


Could Jakarta’s moving goalposts corrode investor faith in nickel?
The Indonesian government’s big push for downstreaming is delivering results, but it comes with trade-offs
[SINGAPORE] Let’s face it. Indonesia’s “long game” to reclaim control of its natural resources is easy to defend.
The commodities-blessed country wants to move beyond supplying feedstock and build an industrial base to capture more value at home.
The rub lies elsewhere.
When pushed aggressively, however, that same strategy risks backfiring and dulling Indonesia’s shine with foreign investors, who value predictability over shifting national priorities.
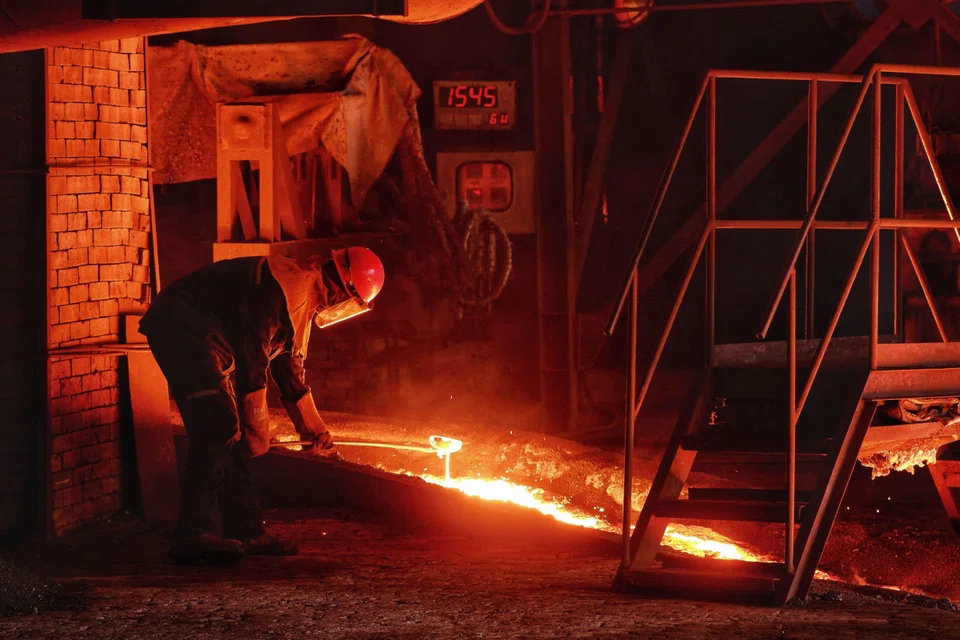
Nowhere is this trade-off more evident than in nickel, where the world’s largest producer of this critical metal for modern batteries – used in electric vehicles (EVs) and electronics – has repeatedly adjusted policy to steer domestic goals.
Nickel also reflects a broader pattern of Jakarta’s resource management – or rather, intervention.
The result is a widening debate among economists, investors and policymakers on whether Jakarta’s proactive strategy will secure long-term gains or erode confidence in the near term.
On the one hand, the government’s big push for downstreaming is paying off. On the other hand, this success has spawned new challenges.
Although the raw nickel ore export ban took full effect in 2020, Indonesia’s strategy was a decade in the making. Between 2013 and 2022, nickel-related industries grew, lifting export revenues from about US$6 billion in raw ore to around US$30 billion in higher-value products, based on official data and industry estimates.
The policy cemented Indonesia’s position as what one analyst called an “uncontested force reshaping global nickel markets” and the EV supply chain.
Foreign capital followed: Chinese firms alone have invested more than US$14 billion into Indonesia’s nickel smelters and refining facilities over the past decade.
But a surge in lower-grade nickel output from Indonesia helped flood the market. With softer demand and broader market forces at play, global prices fell nearly 50 per cent from their peaks.
Now, Jakarta is scrambling to rein things in by blocking new smelters producing nickel pig iron and ferronickel, in favour of higher-value processing.
The recalibration is also extending upstream. Jakarta has signalled plans to tighten its 2025 nickel mining quota, even as the final figures remain fluid.
For investors who committed billions under earlier rules, the abrupt shifts may not just be exasperating, but financially damaging.
The fundamental question is whether Indonesia can change its rule book after the concrete has been poured. The answer is critical not only for drawing future capital flows, but for Indonesia’s own ambitions for durable, long-term growth.
Elsewhere, the story has a similar ring. Palm oil producers have seen millions of hectares seized or frozen over land disputes and to combat illegal operations. The scale and manner of this crackdown have piled on regulatory risks for investors.
Bauxite and copper miners face a familiar ultimatum: process domestically or lose export access.
Some capital will live with that risk. As long as margins stay fat, profit-seeking investors may treat Indonesia as a high-risk, high-return market where contracts flex around industrial policy goals. But the steadier, rule-of-law-minded investors – the kind that anchor long-term growth – may be less easily persuaded.
Indonesia can strike a better balance – if it so desires. Clearer rules and fewer retroactive moves can go a long way to prove that its resource nationalism is a strategy built on predictability, not improvisation.






