Digital bank operators seek to unlock the value of Malaysia’s underserved market
Tan Ai Leng
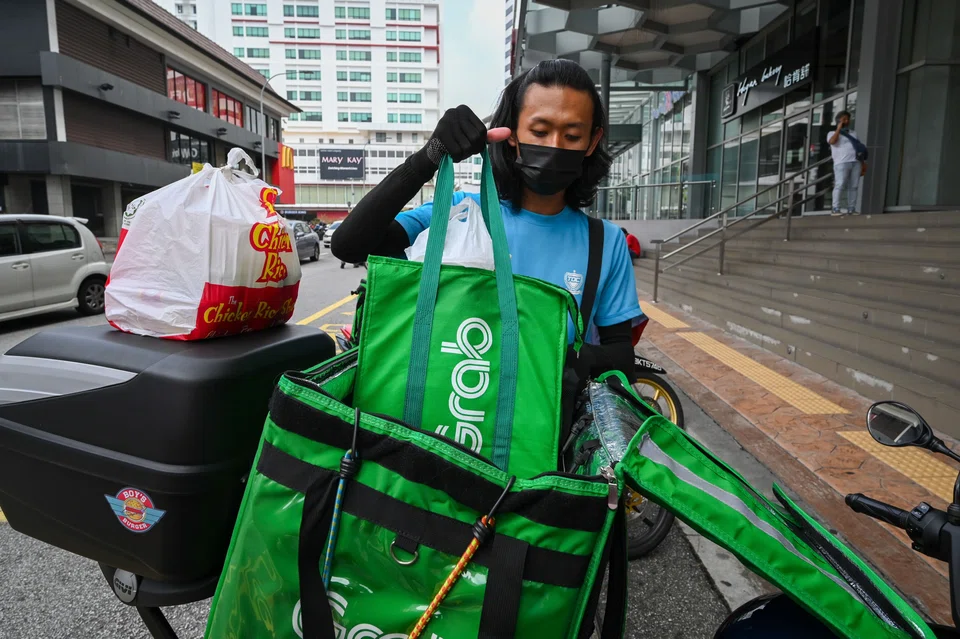
AZLAN Zulkifli felt relieved upon learning that his car loan application was finally approved with the help of a used-car dealer.
Before this, the 34-year-old e-hailing driver’s loan application had been rejected twice by the mainstream banks.
“The banks which approved my housing loan and credit cards previously, when I still had a job with a hotel, have rejected my application mainly because I do not have monthly salary income documents,” said Azlan, who now earns around RM3,500 (S$1,100) a month.
Even if he managed to get a car loan from a non-bank financier, he would have had to pay a higher interest rate of 7 per cent, as compared to 3-5 per cent rates offered by conventional banks.
Azlan is one of some 4 million gig workers in Malaysia, who are categorised as an underserved group in the country with a population of 32.37 million.
Naysan Munusamy, co-founder of MoneyMatch, said not only gig workers, but also small and medium enterprises (SMEs) as well as micro enterprises, which do not have proper accounting records, are facing difficulties in securing a loan to finance their businesses.
“Lack of data is the main issue that’s hindering (conventional) banks from making good lending decisions to SMEs, which is one of the biggest segments in Malaysia’s economy,” he told The Business Times.
As at end-2021, there were some 1.15 million SMEs, making up about 97 per cent of the total number of business establishments in Malaysia. They contributed close to 40 per cent, or RM51 billion, to the country’s gross domestic product last year.
Sheyantha Abeykoon, group chief executive officer of Boost, the fintech arm of Axiata Group, concurred that there are vast unmet financing needs in Malaysia.
“Based on industry findings, an estimated 55 per cent of our country’s adult population is unbanked or underbanked, while just 39 per cent of Malaysians are able to get a loan from their bank,” he added.
Other financing difficulties faced by small businesses include higher collateral requests by traditional financial institutions, requests for additional guarantor, and delays in loan approval or disbursement.
Hence, in the medium term, digital banks are expected to complement traditional financial institutions by filling in the gap and catering to the underserved segments, rather than disrupting the banking sector, he said.
On May 1, Malaysia’s central bank issued five digital bank licences to five consortia including two Singapore-based consortia — Grab-Singtel and Kuok Brothers, and another led by Sea Limited and YTL Digital Capital.
Other consortia include the Boost-RHB Bank tieup; a consortium of Aeon Financial Service, Aeon Credit Service and US-listed fintech firm MoneyLion; and the KAF Investment Bank-led consortium formed by Carsome, MoneyMatch and online financial aggregator Jinerxu.
Eric Cheng, co-founder and chief executive officer of Carsome, said the creation of digital banks could improve financial inclusivity as they can use alternative data points for credit scoring.
“This in turn widens the target segments who can benefit from almost-instant access credit without being bound by conventional restrictions,” he added.
MoneyLion’s spokesperson noted that while the Covid-19 pandemic has driven the digital transformation of the banking business, digital banks have the advantage of building technology and culture from the ground up, without the inertia of legacy technology. This makes it easier to deliver superior capabilities at scale and with lower costs.
“The Malaysian government is looking to develop a robust digital economy and digital banks will be central to the country’s economic future. Investors see digital banks as attractive growth-oriented investment opportunities,” said the spokesperson.
MoneyLion also foresees significant adoption of digital banking services among Malaysians, given the appeal of easier access to financial services, especially for the underserved segments and SMEs.
MoneyMatch’s Naysan added that another advantage of digital banks is quick processing time and attractive rates. “This (cheaper rates) is possible as digital banks are not required to have physical presence, hence the savings on physical operations and overhead costs enable digital bank operators to offer better rates to consumers,” he said.
Asked about their plans and product offerings, the digital bank players said they are still on the drawing board, adding that there are still quite a number of “checkboxes to be ticked”.
“We were given 12 to 24 months to comply with the regulatory requirements, but for the KAF consortium, we are aiming to start rolling out our products next year,” said Naysan.
The digital bank operators also highlighted that the chosen consortia are formed by players from various sectors and this would allow them to access a wide range of markets and avoid direct competition with conventional banks.
Pei Si Lai, chief executive officer designate of the Grab-led consortium, said her team is aiming at harnessing their combined strengths — deep understanding of the Malaysian market, tech expertise, ecosystems, and customer experience — to create a new, digital-first model of banking that is transparent, accessible and tailored to their target segments.
“We will be leveraging synergies across the Malaysia and Singapore digital banks — the scalable tech stack which is being built for the Singapore digital bank will enable us to roll out digital banking services in Malaysia and across the region more efficiently,” she added.
Malaysia is the fifth economy in the Asia-Pacific that joined the digital bank bandwagon after Hong Kong, Taiwan, Singapore and the Philippines. Singapore issued four digital bank licences in December 2020, with the Grab-Singtel joint venture and Sea Limited among the winners.
As for the KAF Investment Bank consortium, Carsome’s Cheng pointed to their combined strengths of an experienced investment bank with core bank capabilities, and automotive (Carsome) and financial technology (MoneyMatch and Jinerxu) capabilities; their future offerings, he said, will be focussed on solving the pain points of underserved groups.
RHB Banking Group’s managing director and chief executive officer Mohd Rashid Mohamad also has similar visions. As a conventional bank operator, RHB believes their partnership with Boost will complement each other in reimagining their journey towards addressing the needs of the underserved and unserved segments of the community, through simpler and affordable products and services, he said.