


Indonesia’s banks breathe easier after rate cuts, but cracks in retail credit remain
Liquidity relief boosts lending, though weak consumer loans and policy risks weigh on sentiment
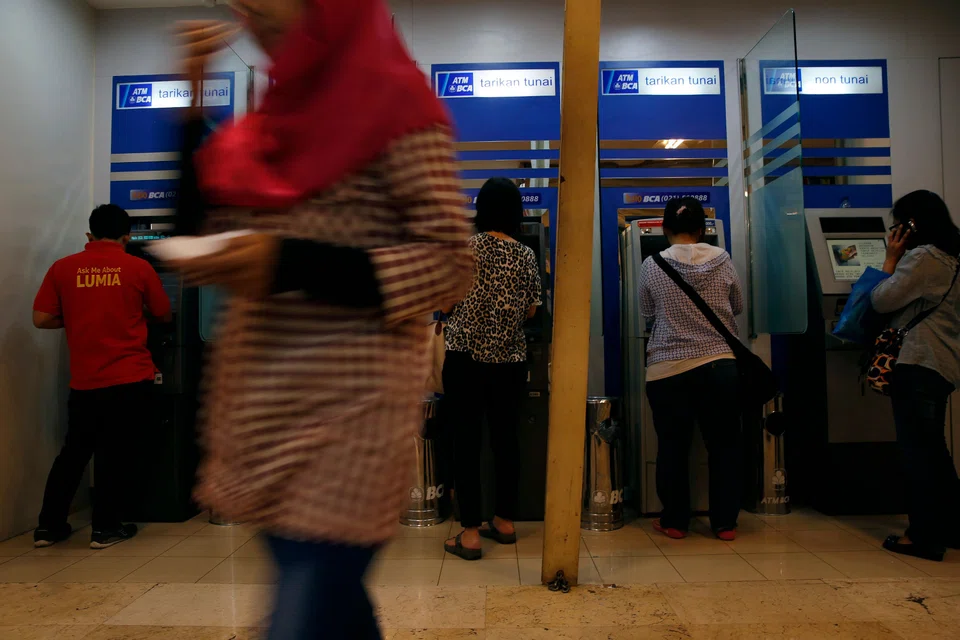
[JAKARTA] After five interest rate cuts and a government liquidity boost, Indonesia’s biggest banks are breathing easier, though not enough to mask deeper cracks in consumer lending and asset quality.
Based on the sector’s nine-month showing, amid a turbulent operating climate marked by rising credit risks, sluggish retail demand and uneven profitability, state lenders are feeling the pinch from higher provisions. Meanwhile, private banks have held firmer ground owing to stronger fee income and lower-cost funding.
Jayden Vantarakis, head of Asean equity research at Macquarie Capital, said Indonesian banks are benefiting from lower funding costs as monetary easing begins to take effect, which should help lift net interest margins (NIMs).
However, he cautioned that rising bad loans in the consumer segment – particularly in mortgages – remain a key risk. “We favour banks with greater exposure to large corporates, where risk-adjusted returns are better,” he said.
The sector remains under pressure from global and policy uncertainty, as well as weak household spending, which are a drag on loan demand and credit quality.
Trioksa Siahaan, head of research at the Indonesian Banking Development Institute, said banks are also contending with high operating cost ratios, elevated funding costs as they strive to maintain liquidity, and growing fraud risks from both internal and external sources.
“Shifting government policies that could reshape banks’ business strategies add another layer of uncertainty,” he said.
State banks under pressure
Giant state-controlled lenders reported softer profits despite improving loan growth. The culprits: higher provisions and operating costs, which weighed on performance.
Bank Mandiri reported a 10 per cent drop in net profit to 37.7 trillion rupiah (S$2.9 billion) for the January-to-September period; operating expenses surged 25 per cent and provisioning costs climbed.
CreditSights analysts Lim Ze Hao and Pramod Shenoi said Mandiri’s heavy exposure to large corporations helped cushion retail softness.
A government liquidity injection of 55 trillion rupiah in September to boost economic activity helped revive lending appetite, lifting loan growth to 11 per cent from a year earlier after several quarters of tepid expansion.
Bank Negara Indonesia (BNI) faced similar challenges. Net profit fell 7.3 per cent to 15.1 trillion rupiah as the lender’s NIM narrowed to 3.8 per cent, dragged by falling loan yields and tight competition.
Though liquidity conditions improved towards the end of the third quarter, asset quality in BNI’s retail book continued to deteriorate, particularly in mortgage and credit card portfolios.
CreditSights noted that while wholesale asset quality remained stable, “the broader economic weakness continues to disproportionately affect lower-income households, SME (small and medium-sized enterprise) workers, and the self-employed”.
The analysts expect BNI’s margins to improve in the final quarter as the effects of lower deposit rates and government liquidity support are fully realised.
Bank Rakyat Indonesia (BRI), the country’s dominant micro-lender, reported a 10 per cent profit decline to 41 trillion rupiah on the back of higher provisions and slower loan expansion. Still, the bank maintained one of the industry’s highest NIMs at 7.7 per cent, underpinned by its microfinance strength.
Meanwhile, Bank Tabungan Negara (BTN), the state-owned lender specialising in housing finance, recorded an 11 per cent increase in profit to 2.3 trillion rupiah. This was driven by higher income from non-subsidised mortgages and better liquidity conditions.
The lender is expected to gain further momentum from President Prabowo Subianto’s plan to accelerate the construction of three million housing units, which could stimulate demand for home loans.
Anticipating potential risks in credit quality within the mortgage segment, BTN has adopted a more cautious stance by raising its loan-loss provisions by 230 per cent year on year to 4.5 trillion rupiah, to strengthen its buffers.
Private banks hold the line
In contrast, privately run Bank Central Asia (BCA) maintained solid performance, with net profit rising 6 per cent to 43.4 trillion rupiah, supported by a 13 per cent increase in non-interest income and a stable NIM.
“BCA remains one of the most efficient and well-capitalised banks in the region, maintaining strong liquidity,” said Miftahul Khaer, research analyst at Kiwoom Sekuritas.
Indonesia’s Islamic banking sector fared well in the third quarter, led by Bank Syariah Indonesia (BSI).
Net profit rose 9 per cent year on year to 5.6 trillion rupiah, supported by a 16 per cent increase in total financing and solid growth in its gold pawning and consumer segments.
Earlier this year, the bank became Indonesia’s first licensed bullion bank and has since seen a sharp rise in gold transactions, fuelled by the global rally in gold prices.
Macquarie analysts described BSI’s performance as “encouraging”, noting that its ongoing diversification beyond consumer financing into trade and corporate segments has helped reduce concentration risks. The bank is also well-positioned to benefit from growing demand for Islamic finance and continued government support for the halal industry.
Liquidity relief, but risks persist
Easing funding pressures across the banking sector have given analysts reason for cautious optimism as the industry heads into 2026.
The country’s overall loan growth reached 7.7 per cent year on year in September – the fastest pace since June – supported by improved liquidity and government fiscal stimulus.
The central bank expects overall lending to finish 2025 near the lower end of its 8 to 11 per cent target range, before accelerating next year as lower rates feed through more broadly.
Yet, challenges remain. Analysts point to fragile household demand, a still-uneven recovery in small business lending, and emerging governance risks following the transfer of state-owned banks under Danantara, a new sovereign wealth entity.
Edi Chandren, investment analyst lead at Stockbit Sekuritas, said most major banks – except BCA – are likely to see a decline in profits this year before recovering in 2026.
“The third-quarter 2025 results mark the lowest point, and we expect to see a gradual recovery starting in the fourth quarter,” he said.






