



Indonesia’s MSCI moment of truth looms over global index standing
The decision will determine whether it remains an emerging market or gets downgraded to a frontier market
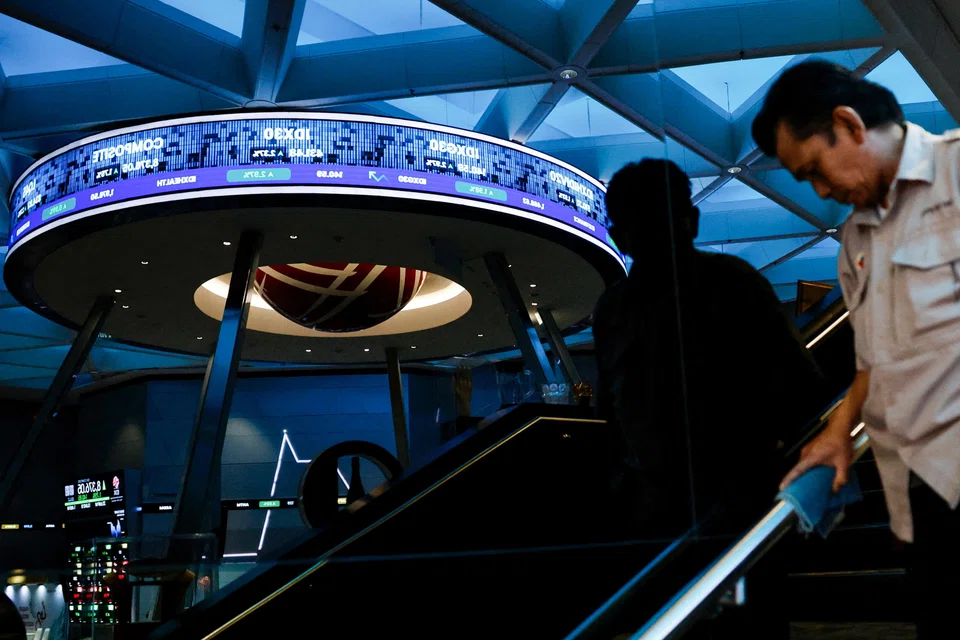
[JAKARTA] It is crunch time for Indonesia’s stock market.
Global benchmark provider MSCI is set to publish its annual market classification review early on Wednesday (Jun 24).
The closely watched decision will determine whether South-east Asia’s largest economy keeps its emerging-market status or risks a downgrade to a frontier-market classification alongside smaller nations such as Sri Lanka and Bangladesh.
The review comes five months after MSCI warned that Indonesia’s status was at risk, citing concerns over market accessibility and investability.
Investors and analysts interviewed by The Business Times see several possible scenarios, with views split on whether Indonesia will retain the emerging market classification it has held for 37 years.
For Harry Su, managing director of research at Samuel Sekuritas Indonesia, a downgrade is unlikely.
He noted that Indonesia continues to meet MSCI’s core requirements on market size, liquidity and economic development, while ongoing reforms have addressed some of the index provider’s concerns over market accessibility.
He also pointed to recent regulatory initiatives aimed at strengthening market transparency, including stricter shareholder disclosure rules, enhanced surveillance of suspicious trading activity and a road map to raise free-float requirements.
Even so, Cameron Systermans, head of multi-asset Asia at Tokyo-based investment consulting firm Mercer, warned that a downgrade to frontier-market status cannot be ruled out, as Indonesia’s reforms will take time to bear fruit.
“The tangible impact of these reforms would take time to materialise, and clear documentation of implementation timelines and independent validation of progress would need time as well,” he said.
In a worst-case scenario, a downgrade to frontier-market status could deal a significant blow to Indonesia’s capital market. Goldman Sachs estimated in January that the move could spark more than U$13 billion in outflows.
Systermans said that an MSCI downgrade would likely trigger passive outflows from index-tracking funds, although much of the adjustment by active investors may have already taken place after MSCI first flagged concerns over Indonesia’s investability in January.
Yet, there appears to be broader consensus on Indonesia’s long-term investment potential.
Ricky Ho, chief investment officer of Singapore-based Four Capital, which manages about US$750 million in assets, said Indonesia has many traits that befit an emerging market: a large economy, a relatively developed stock exchange, ample market capitalisation and a broad base of domestic institutional investors.
“Those fundamentals continue to support Indonesia’s place in the emerging market universe,” he added.
Delicate time
Indonesia has held MSCI’s emerging-market status MSCI since 1989, and remains one of South-east Asia’s largest equity markets. Any reclassification would see the country grouped with frontier markets.
Such a decision could also influence other benchmark providers. FTSE Russell last month delayed its review of Indonesia until at least September, citing the continued scrutiny of the country’s market reforms.
The review comes at a delicate time for Indonesian equities, which have ranked among the world’s worst-performing major markets this year.
Uncertainty has lingered since MSCI warned of a possible downgrade first in January, triggering a multibillion-dollar sell-off and prompting regulators to introduce reforms aimed at improving market transparency.
The Jakarta Composite Index has fallen more than 28 per cent in the year thus far, as persistent foreign outflows and uncertainty over President Prabowo Subianto’s policies weigh on investor sentiment.
Fresh scrutiny
Just days before its closely watched classification review, MSCI on Friday raised fresh questions over Indonesia’s market accessibility, downgrading its information flow criterion to negative.
It pointed to concerns over free-float transparency and coordinated trading activity, arguing that opaque ownership structures can distort price formation and limit investors’ ability to gauge the true free float of listed companies.
It also highlighted the limited availability of corporate disclosures in English, which it said could hinder access to information for international investors.
Su from Samuel Sekuritas said that MSCI’s latest warning could lead investors to demand a higher risk premium if they are unable to accurately assess a company’s true free float, identify its ultimate beneficial owners, or determine whether trading activity reflects genuine market demand.
Ho from Four Capital said in the future global investors may become more selective, demand larger liquidity discounts and allocate incremental capital elsewhere.
“The concern is less about existing capital leaving and more about new capital choosing not to enter,” he added.
While MSCI flagged concerns over information flow, Indonesia retained strong scores across most other market accessibility criteria, including foreign ownership rules, capital mobility, investor registration and trading infrastructure.
That has led some investors to conclude that the risk of an immediate reclassification may be low.
“The review highlights areas that require further improvement, but in our view it does not make a compelling case for a reclassification to frontier-market status at this stage,” said Mohit Mirpuri, senior partner for wealth management at SGMC Capital.
In response to MSCI’s latest assessment, Indonesia’s market regulator said it viewed the findings as constructive feedback that aligns with ongoing efforts to strengthen the country’s capital market framework.
Hasan Fawzi, a senior official at Indonesia’s Financial Services Authority, said that the regulator will continue to engage with MSCI and global investors to ensure that ongoing market reforms are clearly communicated and understood by the international investment community.
Authorities recently appointed capital market veteran Jeffrey Hendrik to lead the Indonesia Stock Exchange, a move seen as part of broader efforts to strengthen investor confidence.
He will be formally appointed, alongside six other executives, at a shareholders’ meeting on Jun 29.
Challenge ahead
Even if Indonesia retains its emerging-market status, analysts said that MSCI’s latest findings point to areas of market transparency and governance that will require further improvement over time.
Mirpuri said investors have already priced in much of the uncertainty surrounding Indonesia’s market outlook, as reflected in higher equity risk premiums and weaker valuations this year.
“The key now is whether continued reforms and greater transparency can convince investors that the market is moving in the right direction and allow that risk premium to narrow over time,” he said.
A decision by MSCI to retain Indonesia’s emerging-market status could help ease some of those concerns.
Wilbert Arifin, an analyst at Mirae Asset Sekuritas, said that such an outcome would remove one of the biggest overhangs weighing on local equities this year.
“A clean outcome would lift the single largest overhang on the market,” he added. “We expect sentiment to improve, paving the way for a more durable rebound.”






