Indonesia’s PasarPolis aims to democratise insurance
[JAKARTA] With Indonesia’s micro-lending industry seeing fast-paced growth in recent years, fintech companies from around the world have been flocking to Indonesia in a bid to tap the vast unbanked market.
Specifically, it is micro-insurance that is seen as the next big growth sector within Indonesia’s rapidly expanding fintech sector, with micro-policies ranging from as little as US$1 per transaction that have flooded the market on the back of the boom in e-commerce.
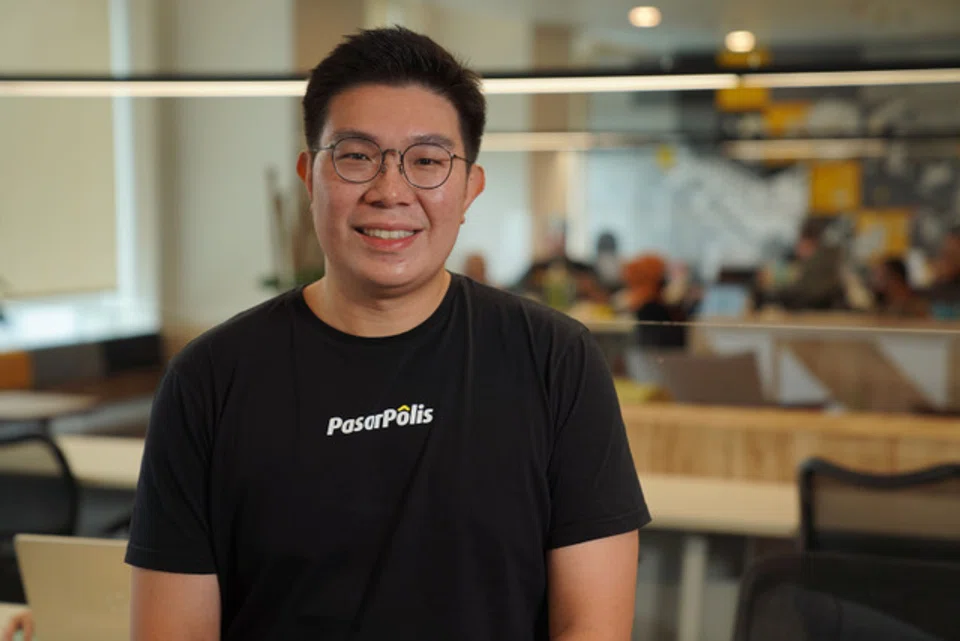
Cleosent Randing, the founder and chief executive officer of Indonesian insurance startup PasarPolis, reckons that the next big growth sector after fintech will be digital insurance.
As of 2021, the company has served one billion policies, and its focus is on making insurance companies more accessible in Indonesia – South-east Asia’s largest economy – and the rest of the region.
The 35-year-old Randing first made his name in Indonesia when he established Valuklik, a digital marketing and analytics advertising firm that was acquired by Dentsu in 2017. In 2015, he founded PasarPolis with the goal of making insurance “affordable, simple and bite-sized”.
In a recent interview with The Business Times in Jakarta, Randing said that if he could reduce the cost of insurance and make it “friction-free”, he would go a long way towards attracting the country’s 70 million-plus millennials. Currently, the insurance penetration in Indonesia is under 3 per cent.
“We want to build a complete ecosystem with our own products which have fewer benefits but meet the needs of the market,” he said. “We want to create insurance products that are affordable, with claims paid out fast.”
Over the years, the company has invested heavily in technology to develop and market insurance products aimed at the consumer lifestyle sector. This strategy involved embedding insurance into the purchase and delivery of products sold online. PasarPolis also sells micro-insurance to Gojek’s 800,000 delivery riders.
Its success in the micro-insurance space has not gone unnoticed. PasarPolis is jointly invested by three Indonesian unicorns – Gojek, Tokopedia and Traveloka. In September 2020, the company marked the largest Series B funding for an insurtech firm in South-east Asia with US$54 million raised by a group of investors including Xiaomi and Go-Ventures.
In early 2021, PasarPolis added the International Finance Corporation – a member of the World Bank Group – as a strategic investor.
As PasarPolis continues to make inroads into the insurance sector, the company is eyeing the second-hand car market as its next growth area, said chief of strategy and product Teo Wei Xiong.
“We moved from lifestyle to devices, and we are now looking at auto-insurance where the asset value is higher but the process is the same,” said the Singaporean, who began his career in the aviation industry.
Currently, insurance for used cars is sold mostly through car dealers, but such insurance is not mandatory in Indonesia.
“We see a huge opportunity,” he said. “When it’s voluntary, you need to make it cheap and easy by scaling it down to the risk that the customer needs to cover. We are looking at policies with a premium of between US$300 and US$500 a year.”
Indonesia currently has 20 million cars on the road with about 80 per cent – or 16 million – being more than four years old.
“For every new car sold, there are three to four used cars transacted so this is a huge market,” said Teo.
Some market analysts have noted, however, that things may not be so smooth sailing for PasarPolis in the coming years. They have flagged two main challenges – whether there is a need for the company to change its model as a licensed distributor, and if it is able to make the shift from products tailored to the online economy to more traditional insurance offerings.
Asked if the company plans to raise more money or follow in the footsteps of other Indonesian tech firms by going public, Randing noted that a listing is possible but much would depend on the timing.
“In the last 12 months, the valuation game has changed as capital costs have gone up,” he said. “There is still a lot of capital out there but investors are looking hard at the growth potential, the tech that is being employed and the team behind the company before making an investment.”
For insurtech companies, the growth potential is high given the low penetration, said Teo, adding that the big difference between the insurance sector and the lending sector is profitability.
“We have been profitable from the gross profit standpoint and we have been investing in our backend system that allows us to issue policies mush faster,” he added. “We start with that principle and the longer-term outlook for us is insurance for all.”