

Malaysia’s industrial property market shifts beyond the data centre boom
Fewer transactions mask resilient demand as investments shift to strategic, high-value assets
[KUALA LUMPUR] The blockbuster wave of data centre investments that propelled Malaysia’s industrial property market over the past two years may be fading, but the sector itself is far from losing steam.
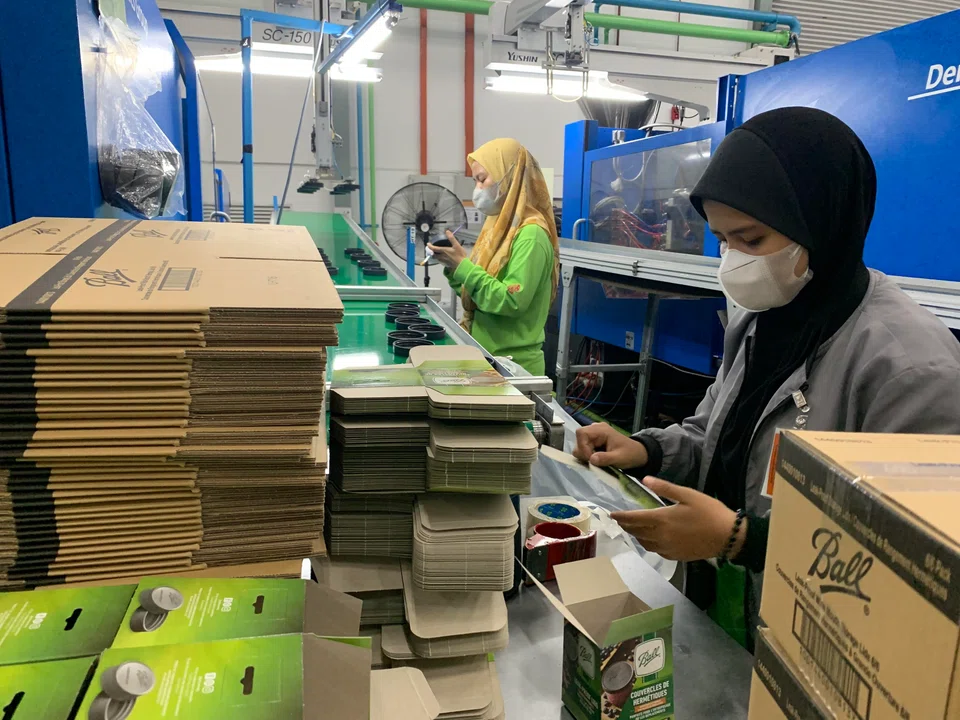
Instead, demand is shifting towards a broader mix of advanced manufacturing, logistics and artificial intelligence-related industries that continue to underpin industrial land values.
Industrial property transactions declined 20.8 per cent quarter on quarter to 1,889 deals in the first three months of 2026, while transaction value fell around 28 per cent to RM7.3 billion (US$1.8 billion), according to the National Property Information Centre.
On a year-on-year basis, transaction volume and value eased 5.6 per cent and 2.1 per cent, respectively.
Market observers said the weaker figures largely reflected softer demand from small and medium-sized enterprises (SMEs) and fewer data centre-related land acquisitions following tighter approval policies, rather than a broad slowdown in Malaysia’s industrial property market.
“The market isn’t slowing as much as it is becoming more selective,” said Allan Sim, senior executive director of land and industrial solutions at Knight Frank Malaysia.
He noted that the decline in transaction volume was largely confined to smaller industrial properties such as terrace and semi-detached factories, which are typically occupied by local SMEs.
“This slowdown reflects a more cautious approach by domestic businesses amid economic uncertainty, rather than a broad market decline,” he said.
While transactions involving smaller factories have moderated, strategic industrial land continues to command strong demand.
This is particularly in locations capable of supporting capital-intensive industries such as AI, advanced manufacturing and logistics, he added.
In Johor, vacant industrial land transactions jumped from 72 deals in the first quarter of 2025 to 128 a year later, signalling sustained demand for large-scale developments, said Sim.
Penang’s, meanwhile, increased from 19 deals in the first quarter of 2025 to 36 a year later.
Its total transaction value for Q1 2026 trebled year on year to RM204.6 million, underscoring intense institutional interest in its supply-constrained high-tech corridors.
The fading data centre factor
Industrial property was once defined largely by factories and warehouses. Today, however, industrial land has become one of Malaysia’s most strategic assets.
Over the past two years, hyperscale operators, technology firms and infrastructure investors have raced to secure sites with sufficient power capacity, water supply and fibre connectivity to support large-scale data centres.
Yulia Nikulicheva, head of research and consultancy at JLL Malaysia, said the market witnessed substantial transaction volumes as investors and operators acquired land for data centre projects.
“With the data centre market still emerging and demand growing exponentially, sellers have commanded significant premiums on land designated for these developments,” she said.
However, she said first-quarter transaction trends were heavily influenced by a policy shift introduced in late 2025.
This was when the Malaysian government, particularly Johor, adopted a more selective approach to data centre approvals by prioritising AI-focused and advanced technology projects.
“This strategic recalibration led to fewer land acquisitions for data centres, serving as a primary driver behind the quarter’s decline in both transaction volume and value,” she said.
The moderation should therefore not be interpreted as a collapse in industrial property demand, Nikulicheva said.
While data centre investments have eased after a wave of blockbuster land deals, the broader industrial market remains resilient.
Dylan Tan, CEO of industrial property developer and park operator AME Elite Consortium, said manufacturing and logistics companies continue to pursue long-term supply chain diversification, although geopolitical uncertainty and shifting trade policies have lengthened investment decision cycles.
“Data centre transactions are always very lumpy. You might see multiple billion-ringgit approvals packed into one quarter, followed by a relatively quiet quarter,” he said.
Tan remains confident about the sector’s fundamentals, noting that industrial property demand naturally grows alongside the economy.
“As long as Malaysia continues attracting investment into manufacturing and logistics, companies will keep expanding their footprint,” he said.
Malaysia’s industrial powerhouses
Malaysia’s top five industrial markets – Selangor, Johor, Perak, Sarawak and Penang – continue to attract investment through distinct but increasingly complementary strengths.
Rather than competing directly, the states are carving out specialised roles within Malaysia’s industrial economy, from semiconductors and logistics to renewable energy and advanced manufacturing.
Knight Frank’s Sim said Selangor and Johor remain the country’s two most established industrial markets, supported by infrastructure, connectivity and mature industrial ecosystems, while Perak, Penang and Sarawak each offer differentiated value propositions that sustain long-term investor interest.
JLL’s Nikulicheva said Johor has become Malaysia’s fastest-growing industrial frontier, benefiting from the Johor-Singapore Special Economic Zone (JS-SEZ), spillover investment from Singapore, logistics expansion, advanced manufacturing and continued interest from data centre developers.
Although Johor recorded only 356 industrial transactions during the first quarter compared with Selangor’s 638, its transaction value reached almost RM2.5 billion, nearly matching Selangor’s RM2.85 billion.
The figures suggest investors are increasingly targeting fewer but significantly larger industrial sites, reflecting demand from capital-intensive industries such as AI infrastructure, semiconductor manufacturing and logistics.
Vacant industrial land transaction value in Johor more than doubled over the past year to RM1.6 billion as companies secured sites for large-scale industrial developments.
Selangor, meanwhile, remains Malaysia’s largest and most diversified industrial market.
Its mature ecosystem, anchored by Port Klang, extensive highways, multinational manufacturers, logistics operators and the country’s largest labour pool, continues to attract investments across industries.
The industries range from electronics and aerospace to food manufacturing and third-party logistics.
Penang continues to reinforce its position as Malaysia’s semiconductor powerhouse.
Demand remains concentrated in industrial corridors such as Perai and Bukit Minyak, supported by multinational electronics manufacturers, a highly skilled workforce and limited land supply.
Elsewhere, Perak is emerging as a lower-cost alternative for manufacturers seeking larger industrial sites between Penang and the Klang Valley.
Projects including Silver Valley Technology Park and Kerian Integrated Green Industrial Park are positioning the state to capture future investment in advanced manufacturing and green industries.
Sarawak, meanwhile, is carving out a niche few states can match.
Its abundant hydroelectric resources and relatively low-cost renewable electricity are attracting energy-intensive industries such as aluminium, ferroalloys and, increasingly, green hydrogen projects.
Together, these developments suggest Malaysia is evolving from a single industrial corridor into a network of specialised manufacturing and logistics hubs.
Industrial land: the new premium asset
Industrial land is increasingly being valued less for its size than for its infrastructure.
Access to reliable electricity, water, fibre connectivity, ports and highways has become the defining factor behind pricing, particularly for AI-driven industries.
Knight Frank and JLL said Johor, Selangor and Penang continue to lead industrial land appreciation, each driven by different catalysts.
In Johor, industrial corridors such as Kulai, Senai and Plentong have experienced sharp price growth, fuelled by Singapore spillover demand, the JS-SEZ and technology investments.
High-profile projects including Haitian Group’s RM3 billion industrial park and SICK AG’s RM1 billion manufacturing facility underscore the state’s transition towards higher-value manufacturing.
Selangor’s appreciation remains more structural, supported by land scarcity and redevelopment of ageing industrial estates into modern facilities.
Meanwhile, Penang continues to benefit from its entrenched semiconductor ecosystem and chronic shortage of industrial land, sustaining upward pressure on prices.
Despite lower transaction volumes, Pahang and Negeri Sembilan recorded relatively high transaction values driven by different market dynamics.
Pahang benefited from large industrial land deals centred on the Gebeng heavy industrial corridor, supported by the East Coast Rail Link and Kuantan Port expansion.
Negeri Sembilan’s growth has been driven by SMEs seeking more affordable industrial space close to the Klang Valley under Malaysia Vision Valley 2.0.
Risks remain
Despite the positive structural outlook, Knight Frank cautioned that industrial demand remains closely tied to foreign direct investment.
This makes the sector vulnerable to geopolitical tensions, shifting global trade policies and weaker international economic conditions.
Policy consistency will also be crucial. Nikulicheva said the first-quarter slowdown showed how quickly investment activity could respond to regulatory changes, particularly policies affecting data centre approvals.
Supply conditions also vary widely between states. For instance, Negeri Sembilan faces a relatively large incoming supply pipeline that could prove challenging if economic growth weakens or major industrial projects fail to attract tenants.
Penang, meanwhile, faces the opposite problem. Its limited supply of industrial land is expected to keep prices and rents rising, although that may eventually erode its competitiveness for export-oriented manufacturers.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing
Looking beyond looming CEO succession, should UOB potentially pursue a transformative merger?

Could stablecoins be the future of money?
Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

