



Office Reits in the Philippines get a boost as spotty Internet limits work-from-home
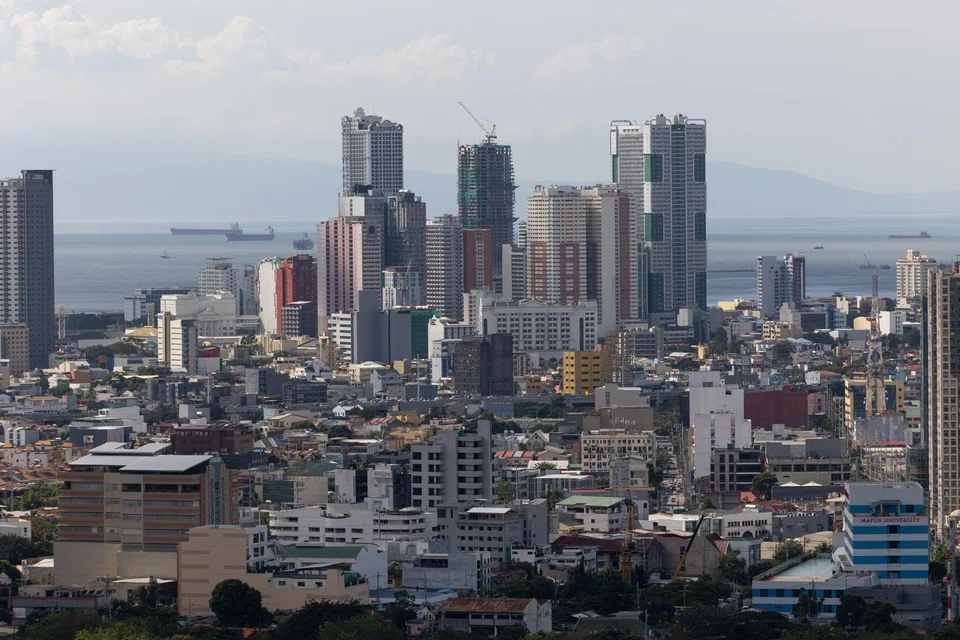
POORER Internet infrastructure in the Philippines is proving to be a boon for office landlords in the archipelago.
While managers of some real estate investment trusts (Reits) with office assets are fretting over low physical occupancy rates due to work-from-home trends, market watchers say employees in the Philippines are returning to the office at a healthy rate.
“Amid negative news flow surrounding remote work and the POGO (Philippine offshore gaming operators) sector, actual impact to office occupancy and rental rates has been minimal,” said Maybank analyst Miguel Sevidal.
Nearly all of the Philippines’ seven real estate investment trusts (Reits) are focused on office and commercial assets.
The exception is Citicore Energy Reit, which focuses on the renewable energy sector. Its portfolio comprises a solar asset and land leased out to solar operators.
“We maintain the view that the hybrid work set-up will not have a meaningful impact on office occupancy due to internet infrastructure-related barriers,” Sevidal said.
This situation puts the Philippines Reits in a position of strength relative to some of the Singapore-listed real estate investment trusts (S-Reits) with US office properties.
Physical occupancy at US office assets is below 50 per cent on average, as employees – presumably with stable Internet connectivity at home – embrace the flexibility of work-from-home arrangements.
The resistance towards returning to the office has led one of the three US office S-Reits, Manulife US Reit (MUST), to conduct a strategic review to assess “opportunities” amid persistent headwinds in the US office sector.
Units of the three US office S-Reits – MUST, Keppel Pacific Oak US Reit (KORE), and Prime US Reit – have fallen by between 39 per cent and 58 per cent over the last year.
S-Reits with office assets in Singapore, which benefited last year from higher rental growth at Grade A buildings in the core central business district, are also expected to face challenges this year.
“We expect slowing economic growth to weigh on the office sector,” said DBS analysts Rachel Tan and Derek Tan.
In particular, the pair say the IT and financial services sectors – the two key drivers of Singapore’s office market – could be impacted by challenging global economic conditions.
JPMorgan analysts Mervin Song, Terence Khi and Cusson Leung point out that Singapore office Reits are trading at the tightest capitalisation rates among its peers, at about 3.5 per cent, and are therefore “most vulnerable” to higher interest rates.
“We anticipate the greatest risk to office property values in the event of cap rate expansion next year, with gearing to increase by 2.5 percentage points and net asset value (NAV) to fall 10 per cent for every 25 basis point rise in cap rates,” the analysts said.
“Additionally, with a potential slowdown from a US recession and tech job losses, we expect Singapore office demand to stall,” they added.
JPMorgan remains “underweight” on Keppel Reit and Suntec Reit , which have a sizeable portion of their respective portfolios in Singapore-based office assets.
On the other hand, Maybank’s Sevidal is upbeat on the outlook for the Philippines office Reits.
“We maintain our positive view on Philippine-listed real estate investment trusts (PH-Reits) in FY2023 as we expect consistent earnings growth, underpinned by a stable office market; and a less reactive interest rate environment, which should shift investment appetite to higher yielding Reits,” he said.
According to Sevidal, PH-Reits currently offer estimated dividend yields of between 7.2 and 8.6 per cent for FY2023, as well as potential total returns of 28 to 75 per cent.
“We like Reits well-positioned against incoming new office supply in Metro Manila and with exposure to the growing provincial office sector,” Sevidal said, adding that his top picks for the sector are Ayala Land Reit (AReit) and Megaworld Reit (MReit).
“The sponsors of AReit and MReit have the largest office asset bases for infusion at 1.1 million square metres (sq m) and 887,000 sq m, respectively,” he said. “While we expect office assets to remain the primary acquisition targets due to longer lease terms, we may see retail asset injections following the reinstatement of pre-pandemic rents.”
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

What role can Japan play in Asean’s future?

From folding clothes to factory work: Why China is sending humanoid robots to school

