



Ringgit sinks to seven-month low despite record bond inflows as Fed fears dominate
But analysts think the weakness is a correction rather than the beginning of a depreciation trend
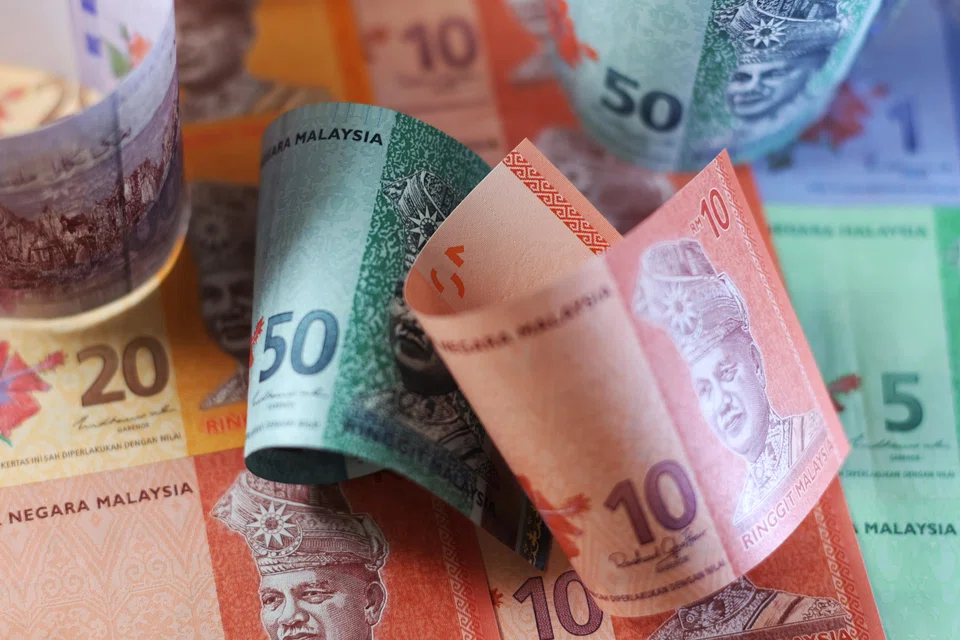
[KUALA LUMPUR] The ringgit’s slide to its weakest level since November came despite record foreign bond inflows, highlighting the growing influence of US Federal Reserve policy expectations on Malaysia’s improving economic fundamentals.
The currency has depreciated 1.7 per cent over the past week, hitting 4.1349 against the US dollar on Wednesday (Jun 24). It has retreated significantly from its peak of 3.8847 on Feb 27, after which the outbreak of the US-Iran war triggered a flight to safety.
This also moves it further away from the psychologically important RM4 level, and marks its weakest level since November 2025, according to MBSB Research.
The decline came despite a string of supportive domestic developments, including stronger-than-expected trade data, stable inflation and a surge in foreign demand for Malaysian debt securities.
Foreign holdings of Malaysian government and corporate bonds rose by nearly RM7.5 billion (S$2.4 billion) between Jun 8 and 15. This was a turnaround from the RM900 million outflow in the previous corresponding period, and lifted total foreign holdings to a record RM311 billion.
The divergence underscores a reality where, despite supportive domestic economic fundamentals, the ringgit’s near-term direction is increasingly dictated by the Fed, global risk sentiment and capital flows.
Bank Negara Malaysia’s Financial Markets Committee (FMC) issued a statement on Wednesday, noting that the recent movements in the ringgit and regional currencies have continued to be driven largely by global developments.
“While geopolitical uncertainties have partially eased following an interim peace deal signed by the US and Iran, global financial markets have remained focused on the prospects of higher policy rates in the US amid elevated inflation risks,” said FMC.
It added that foreign investors have adopted a neutral stance towards Malaysian assets ahead of the upcoming state elections, contributing to a market correction in June after the ringgit’s strong performance earlier in the year.
The committee also pointed to increased hedging activity amid a stronger US dollar and equity rebalancing linked to the latest MSCI index review, which saw six Malaysian stocks removed from the benchmark index.
FMC added that the onshore foreign-exchange market remained healthy, with average daily turnover rising to US$21.3 billion this year from US$19.8 billion in 2025.
Entering correction stage
Analysts broadly agree that the recent weakness represents a correction rather than the beginning of a prolonged depreciation trend.
Christopher Wong, a forex strategist at OCBC, said that many of the ringgit’s earlier positives – including resilient external balances, reform momentum and portfolio inflows – had already been reflected in market pricing.
“The pullback in June was largely driven by the broader external backdrop, including hawkish Fed repricing, firmer US yields, intermittent US dollar strength and softer regional risk sentiment,” he noted.
While domestic political developments may have added a modest risk premium, Wong said that he does not believe the ringgit’s underlying story has turned negative.
Analysts generally expect the ringgit to remain pressured by a stronger greenback and uncertainty over the Fed’s policy path.
Wong forecasts USD/MYR to be at 4.15 by end-2026.
Meanwhile, Jeff Ng, head of Asia macro strategy at Sumitomo Mitsui Banking Corp (SMBC), is reviewing his previous 3.85 target and now sees the currency potentially ending the year at above RM4 per US dollar.
Against the Singapore dollar, the ringgit has depreciated 0.5 per cent over the past week to 3.1863 on Wednesday. Ng expects SGD/MYR to rise towards 3.25 in the near term, signalling further ringgit weakness.
Singdollar dominates as ringgit steadies
The ringgit’s recent weakness has also mirrored broader movements across the region as investors reassess the outlook for US monetary policy.
OCBC’s Wong expects Asean currency performance to remain differentiated in the second half of the year.
He sees the Singdollar remaining among the region’s stronger performers due to its defensive characteristics and the Monetary Authority of Singapore’s relatively tight policy stance.
The Indonesian rupiah could receive support from attractive yields and policy measures, he added.
At the other end of the spectrum, the Thai baht and Philippine peso may face greater challenges amid softer growth conditions and domestic vulnerabilities.
“The ringgit sits somewhere in the middle of the regional pack,” said Wong.
“We are not bearish on the ringgit, but we have shifted to a more neutral-to-slightly-cautious near-term stance.”
SMBC’s Ng pointed out that the factors that previously supported the ringgit have begun to go the other way.
“The ringgit performed well during expectations of a dovish Fed and rising commodity prices. Now both factors are reversing,” he said.
He noted that while easing tensions between the US and Iran could lower energy prices, the Fed has adopted a more hawkish tone than what markets anticipated earlier this year.
At the start of 2026, investors had expected as many as two or three US rate cuts. Ng now sees the possibility of the Fed raising rates instead, one or two times later this year.
Dominant driver
Economists broadly agree that global forces are now the dominant driver of the ringgit.
Dr Mohd Afzanizam Abdul Rashid, chief economist at Bank Muamalat Malaysia, said that US interest rates remain the most important factor influencing the currency.
He noted that markets are adjusting to the communication style of new Fed chair Kevin Warsh, whose limited forward guidance has heightened uncertainty over the future path of monetary policy.
Beyond the Fed, Dr Afzanizam identified oil prices and domestic policy continuity as key risks.
“As the country enters an election season, investors will be closely watching the commitment of political parties towards economic reforms and fiscal consolidation,” he said.
Dr Geoffrey Williams, founder of Williams Business Consultancy, also sees US dollar strength as the biggest risk to the ringgit, forecasting it to trade between RM4.20 and RM4.40 against the greenback for the rest of 2026.
He ranked uncertainty surrounding the timing and outcome of Malaysia’s next general election as the second-largest risk, saying investors are seeking greater clarity on future policy direction amid shifting political alliances.
However, Dr Williams noted that the country’s economic fundamentals remain supportive and should help limit downside pressure on the currency.
Meanwhile, Bank Negara Malaysia said that it would intensify efforts to support the ringgit by encouraging government-linked entities and corporates to repatriate and convert overseas earnings.
Nevertheless, analysts believe domestic measures are unlikely to outweigh the impact of US monetary policy and global capital flows.
“The ringgit’s direction will be determined more by the strength of the US dollar than by domestic factors,” added Dr Williams.
TRENDING NOW

Incidence of civil servants buying property near unannounced MRT stations ‘a concern’, but may not establish misconduct: PSD

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Income Insurance appoints former Manulife Singapore top man as new CEO

HDB reviewing ‘jumbo’ flat scheme after Telok Blangah unit listed for sale at S$2.18m

