



Sunway-IJM takeover bid collapse: IJM wins but faces pressure to deliver value
Asset monetisation, spin-off plans in focus as IJM races to deliver value within tight timelines
[KUALA LUMPUR] Malaysia’s IJM Corp has dodged a RM11 billion (S$3.5 billion) takeover by Sunway, handing the group a reprieve but setting a significantly higher bar to prove its standalone value.
The construction and property group may have emerged as the winner after Sunway’s conditional voluntary offer lapsed on Apr 6, falling short of the 50 per cent acceptance threshold with only 33.4 per cent of shareholders tendering their shares.
The outcome brings to an end Sunway’s attempt to merge two of Malaysia’s largest developers into a powerhouse with an estimated market value of around RM50 billion.
Analysts broadly agree on one crucial point: IJM has successfully defended its turf against a blue-chip conglomerate four times its size, with Sunway’s RM34.4 billion market capitalisation dwarfing IJM’s RM8.4 billion.
Yet, rather than closing a chapter, the failed bid has reset expectations and intensified scrutiny on IJM’s ability to unlock value on its own.
Failed bid does not mean lack of support
Tradeview Capital portfolio manager Neoh Jia Man noted that the rejection of Sunway’s RM3.15 per share offer does not necessarily reflect a lack of market support.
Pointing to the fact that the bid still secured more than a third of IJM’s shares, Neoh described the result as "meaningful", particularly since government-linked investment companies (GLICs), which control over 43 per cent of the company, were widely expected to hold their positions.
“Stripping out these GLIC stakes, the level of acceptance suggests that the offer did, in fact, resonate with a substantial portion of minority shareholders,” he told The Business Times.
Instead, the decisive factor appears to have been the GLICs themselves, which effectively acted as a blocking stake.
Neoh noted that reluctance from major shareholders likely points to a preference for long-term, organic growth over a quick exit.
“Given the independent adviser’s valuation of RM5.84 to RM6.48 per share, the RM3.15 offer was arguably too low. As a result, GLICs likely dismissed the bid as an opportunistic play that failed to account for the group's intrinsic value,” he added.
Sunway’s pitch falls short
For Sunway, the failed bid marks the collapse of an ambitious attempt to create Malaysia’s largest construction and property conglomerate.
Sunway founder and chairman Jeffrey Cheah had earlier positioned the merger as a move to build a national champion, arguing that the combined group would deliver stronger performance and enhanced returns for shareholders.
Sunway also leaned on its execution track record, highlighting that it had generated total shareholder returns of about 387 per cent over the past decade – far outpacing IJM, whose shares declined roughly 9 per cent over the same period.
Against this backdrop, the group argued it could unlock greater value from IJM’s assets through its scale, operating experience and integration capabilities.
Yet those arguments ultimately failed to convince IJM’s key shareholders.
A vote of confidence
The rejection preserves shareholders’ exposure to IJM’s long-term asset monetisation pipeline, with value expected to be realised progressively, said analysts.
With Sunway’s case for value creation no longer in play, the onus shifts squarely onto IJM’s management to execute.
If successful, the move could reposition IJM into a high-multiple proxy for Malaysia’s construction sector, specifically within the booming data centre segment, said MBSB Research.
Hong Leong Investment Bank analyst Brian Chin said a spin-off listing of the construction arm would require the group to demonstrate solid margin execution, deepen its exposure to data centres and sustain a robust orderbook replenishment outlook.
“The takeover attempt has created a strong sense of urgency for IJM’s management and board to expedite these initiatives,” said Chin, highlighting the proposed listing of its construction arm and toll road assets.
“With property sales likely to remain sluggish, a greater focus on monetising idle land and pursuing faster-turnaround projects will be key to enhancing its return on equity,” he added.
Data centre momentum builds
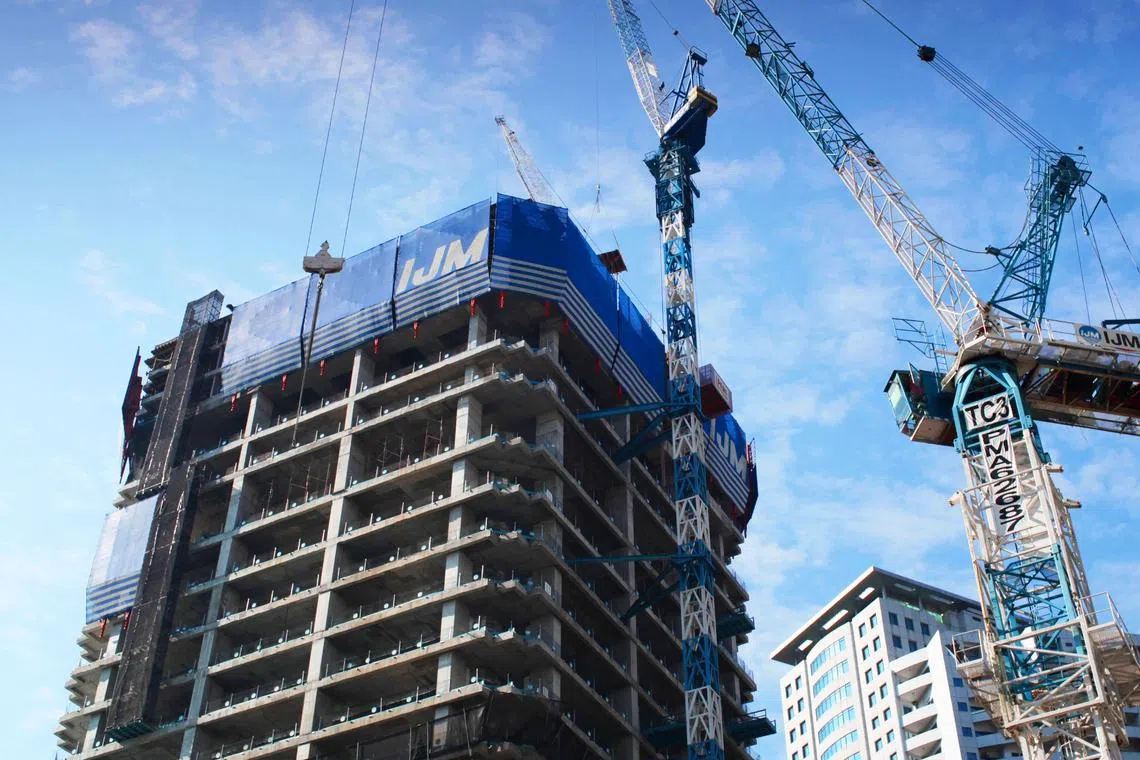
MBSB Research highlighted the group’s RM658 million data centre contract from Sime Darby for Phase 2 of a project in Elmina Business Park, Selangor, bringing total contracts for the development to over RM1.9 billion.
The win lifts IJM’s orderbook to RM8.2 billion in 2026 so far, and reinforces the resilience of its data centre pipeline.
With legacy low-margin projects nearing completion, IJM’s profitability is expected to improve in the coming quarters, said MBSB.
The research firm noted that further upside could come from additional data centre projects in the Klang Valley and Johor, as well as potential participation in major infrastructure works such as the Penang Mutiara Line LRT project, potentially worth around RM6 billion.
Monetisation now in focus
Beyond construction, the spotlight is also on IJM’s broader restructuring plans.
These include monetising mature toll road assets, exiting its India operations within the next two to three years, and streamlining its asset-heavy portfolio – all aimed at improving return on equity and narrowing its valuation gap.
UOB Kay Hian analysts Jack Lai and Ng Jo Yee said progress on these initiatives could drive a rerating, pointing to IJM’s two-year value-creation plan. A central pillar of this strategy is the carve-out of the construction business, allowing it to trade as a dedicated pure-play entity.
“Now that the acquisition has fallen through, IJM’s monetisation efforts have returned to the spotlight,” said Lai and Ng.
However, they cautioned on execution risks, particularly in listing assets at attractive valuations within a tight timeframe.
Short-term volatility likely
While the longer-term outlook remains constructive, analysts caution that IJM’s share price could face near-term pressure.
The company still faces a overhang from a Malaysian Anti-Corruption Commission (MACC) investigation into IJM, which although largely isolated to individuals, contributed to waning support for the deal and added a layer of reputational risk.
“While we understand the MACC investigation was largely isolated to individuals and had minimal bearing on the decision by GLICs, we still view this outcome as unsurprising given support had started to wane following the disruptions,” said Lai and Ng.
UOB Kay Hian estimates the stock could see a downside of up to 13 per cent if valuations revert to previous lows, amid lingering concerns over earnings delivery and broader market uncertainties.
IJM closed unchanged at RM2.28 on Wednesday (Apr 8). This was still 19 per cent lower than its Jan 18 closing price of RM2.82, the highest level in the past six months.
The counter hit the six-month high after the initial announcement of Sunway’s acquisition bid on Jan 12.
Meanwhile, Sunway shares climbed 1.4 per cent to RM5.07 on Apr 8. Despite that, the stock is still trading roughly 15 per cent below its Feb 26 peak of RM5.95 – the stock’s highest level in the last six months.
Valuation estimates remain mixed for IJM. Hong Leong Investment Bank maintained a “buy” call with a target price of RM3.20, while MBSB Research pegged fair value at RM3.29.
Both remain well below IJM’s independent adviser valuation range of RM5.84 to RM6.48 per share – underscoring the gap between current market expectations and longer-term upside assumptions.
TRENDING NOW

Simba admits exceeding spectrum limits amid failed M1 deal; full-year profits surge 277%

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
What’s on the agenda when Xi and Trump meet in Washington

Ex-execs of CW Group, Allied Tech charged with offences linked to lawyer’s S$76 million misappropriation

