



Thailand unicorns remain elusive as banks’ dominance stifles fintechs
Having invested heavily in digitalisation, the 6 major banks could be limiting competition and innovation in startups
[BANGKOK] While unicorns worldwide struggle with funding challenges and waning investor interest, Thailand’s fintech sector has managed to sidestep the drought – though not for the reasons one might expect. The country has no fintech unicorns and few foreign venture capital (VC) firms operating within its borders.
“In Thailand, the reason we don’t have fintech unicorns is because if you would like to do a startup, you need venture capital, and we have so few VCs and private equity funds here,” Chonladet Khemarattana, president of the Thai Fintech Association, told The Business Times.
He added: “All the VCs are actually CVCs (corporate venture capitalists).”
Chonladet is a prime example of how the local fintech scene works – or doesn’t. He started a fintech called Robowealth a few years ago, pioneering robo-advisory services, but sold a majority stake in the startup to Beacon Ventures, the VC arm of Kasikorn Bank, one of Thailand’s leading banks.
“In this country, the pattern is to innovate and collaborate,” Chonladet said.
While selling out to a local bank can offer fintechs access to valuable data and capital, it may also stifle their potential to evolve into unicorns. As Chonladet pointed out, many fintechs in Thailand are designed more to support banks with targeted projects than to scale into independent, high-growth ventures.
Things might be different if there were a greater presence of foreign VCs and private equity funds to tap into.
It’s a widely shared sentiment. “Venture capital is part of the finance for SMEs (small and medium-sized enterprises) to grow a startup, and Thailand does not have enough venture capital moving into the country,” said Cristian Quijada Torres, a senior private sector development specialist at the World Bank.
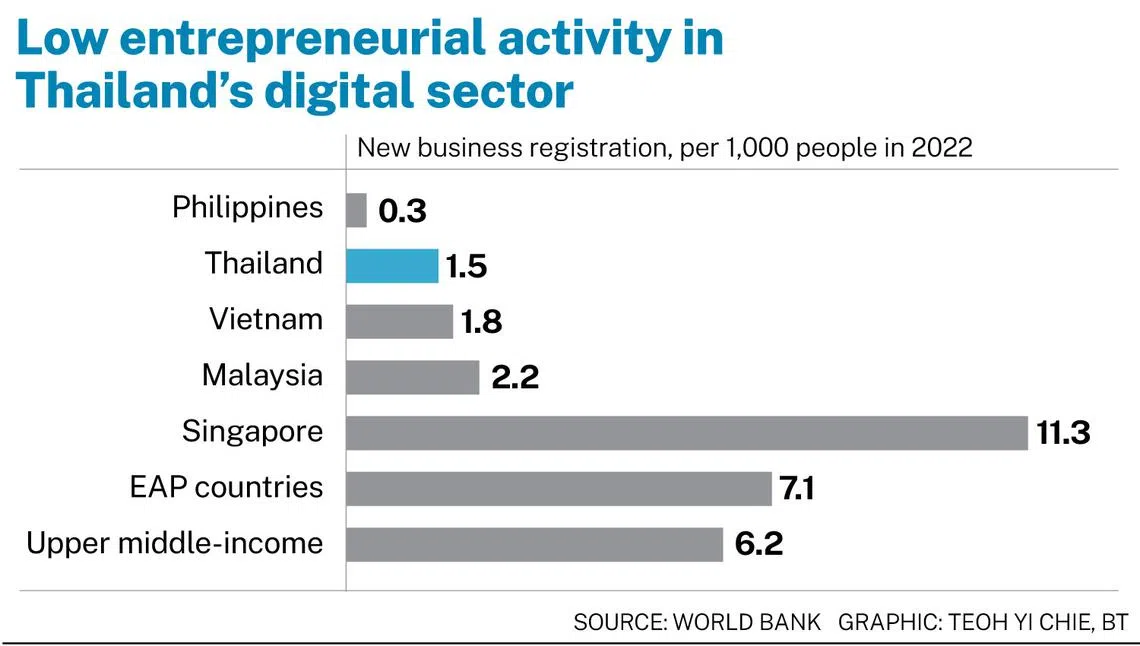
“In terms of the innovation category, Thailand doesn’t do too well compared with its peers,” said Torres, addressing a recent forum on innovation, SMEs and startups. “Thailand needs to increase the number of (SMEs) engaged in innovation, stimulate new fires... needs more venture capital, more incubators and more accelerators.”
Part of the challenge is the lack of a competitive environment in the Thai economy, where innovation is dominated by corporate bigwigs.
The country’s six big banks – Bangkok Bank, Kasikorn, Krungthai, Siam Commercial Bank (SCB), Krungsri and TMBThanachart – dominate the commercial banking sector, controlling 82 per cent of commercial banks’ loans and deposits.
In recent years, these sector stalwarts in the country have invested heavily in digitalising their operations while waiving fees on cyber transactions from money transfers, and utilities to other bill payments.
This – although arguably good for customers – has clipped the wings of new fintech startups, in terms of the value add they can offer customers, say analysts.
Virtual banking
Analysts do not expect the stranglehold by big banks in the digital banking space to be seriously disrupted when three new virtual bank licences are issued sometime in the middle of this year.
For one thing, three of the five contenders for the licences are consortiums led by big Thai banks – Bangkok Bank, Krungthai and SCB – with the other two having family connections to the Charoen Pokphand conglomerate, which owns Ascend Money, Thailand’s largest fintech.
Virtual banks have lower overhead costs – avoiding expenses such as brick-and-mortar branches and bank teller salaries – and should, in theory, be well-positioned to address the lending needs of Thailand’s underbanked SMEs. These businesses make up almost all or 99 per cent of all companies, account for nearly 70 per cent of employment, and contribute around 35 per cent of gross domestic product, according to World Bank data.
Analysts doubt that virtual banks will do much better than their brick-and-mortar brethren in addressing SME needs.
“The market is already pretty saturated in terms of both products and clients, so there’s not that much room for disruption,” said Parson Singha, senior director for financial institutions at Fitch Ratings Thailand.
Thailand’s household debt is already equal to around 89 per cent of GDP – the highest is the region.
“For SME lending, I think it’s more about wider macro issues,” said Singha. “Since Covid, asset quality at SMEs has been weak. It’s very high risk for any new company, fintech or not, to suddenly give out loans to SMEs.”
Another recent innovation of the Bank of Thailand is to push for “open data”, forcing banks and institutions to make data available to outside players at a reasonable fee.
This development should be good for fintechs and other startups.
“At the moment, if you don’t have access to data, you are going to be in trouble as a fintech, which is what has happened already,” said Kiatipong Ariyapruchya, senior country economist of the World Bank for Thailand. “So if you are new, and you have a new fintech product, but you don’t have access to data, then one of the large firms will acquire you.”
Of course, if there were a lot of foreign VC firms in Thailand, they might offer another option, but competition from local CVCs and the size of the Thai market are drawbacks.
“We cannot attract the foreign VCs to come in, because we are too small, and the deals are too small, so they don’t justify the due-diligence costs,” said Chonladet, adding: “We don’t have foreign VCs, so we need to rely on local CVCs.”






