


Thailand’s proposed global income tax sparks concerns over expat exodus
While the potential changes have raised worries among foreign chambers of commerce, they do not yet appear to be a major issue for incoming FDI
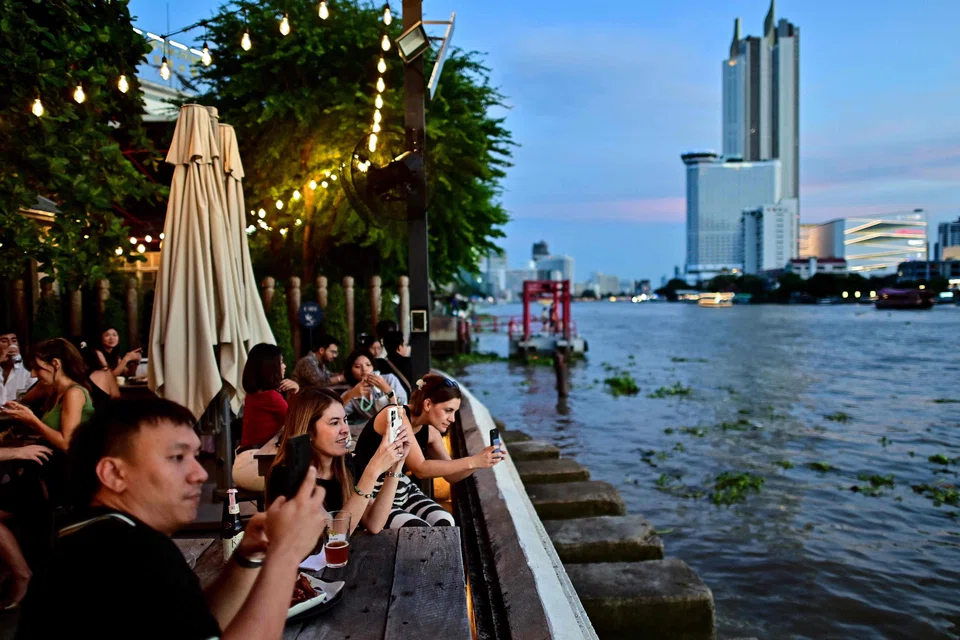
[BANGKOK] A proposed amendment to Thailand’s revenue code which aims to tax the global income and assets of all Thai residents – including expatriates residing in the kingdom for 180 days or longer – has prompted international chambers of commerce to seek urgent clarity.
In recent months, these groups have actively engaged with the Revenue Department to obtain further details and assess the potential implications of the new tax policy.
The draft legislation, which has yet to be finalised by the Revenue Department, could negatively impact Thailand’s foreign direct investment (FDI) climate and efforts to attract expatriates, such as retirees, to work or reside in the country, say observers.
“This new law would say that if you are a Thai resident, you will be taxed on your worldwide income, even if it is not remitted to Thailand. That would be a big negative change,” said Jonathan Stuart-Smith, a partner at tax consultancy Forvis Mazars in Thailand.
Under the kingdom’s existing tax policy, which went into effect on Jan 1 this year, foreign-sourced income is subject to taxation only if it was remitted to Thailand within the same calendar year it was earned.
Stuart-Smith, who sits on the tax committee of the American Chamber of Commerce, said a recent visit to the Revenue Department revealed that officials were still working on the draft and expected it could be put into law as soon as 2026.
The legislative process is expected to take time and may encounter opposition from officials or politicians worried about its potential impact on Thailand’s competitiveness in attracting FDI, as well as retaining skilled or wealthy expatriates in the future.
“This would require a change in the law,” said Stuart-Smith. “It would have to pass through the Revenue Department, the Ministry of Finance, the Cabinet and (the lower and upper houses of) Parliament. Quite a few hoops to jump through, but they are working on it.”
Impact on wealthy Thais
The law, if enforced, would also apply to the global incomes and assets of wealthy Thai nationals, many of whom have investments and earning abroad.
The value of Thai investments in foreign capital markets reached US$106 billion in 2022, Bank of Thailand statistics showed.
Wealthy Thais may be less affected by the new tax, as they are less likely to remit money back to the kingdom, potentially making it easier for the Revenue Department to audit their financial activities.
“Foreigners living in Thailand have to bring in money to be used in Thailand, so they are more worried,” noted one international tax lawyer who sits on the tax committee of another foreign chamber of commerce, but requested anonymity.
The proposed amendment to Section 41 of the Revenue Code builds on a reinterpretation of taxation on remittances announced in September 2023, which took effect on Jan 1 this year.
The Business Times’ queries to the Revenue Department for more information on the proposed tax law received no response.
Under the new rules, all money remitted to Thailand and earned after Dec 31, 2023, will be subject to progressive tax rates of up to 35 per cent, unless classified as a gift. For income originating from one of the 61 countries with which Thailand has a double taxation treaty, the Thai tax liability may be reduced by the amount of tax already paid overseas.
These tax regulation changes were introduced under the coalition government led by Prime Minister Paetongtarn Shinawatra and the Pheu Thai Party, which came to power after the May 2023 election.
The party campaigned on promises such as distributing 10,000 baht (S$385) to some 50 million Thai citizens, a pledge partially fulfilled with 14 million recipients already receiving the handout.
“The finance ministry needs to raise money for the 10,000 baht giveaway, and foreigners don’t get the handout,” said the tax lawyer.
Hopes of joining OECD
In September 2023, Thailand adopted the Common Reporting Standard, a framework backed by the Organisation for Economic Co-operation and Development (OECD) for the automatic exchange of financial account information. This aligns with the kingdom’s ambitions to join the organisation.
“The Revenue Department’s premise is that (it needs to tax global income) to align with global standards in taxation, as Thailand becomes more internationally aligned with international law, and in the context of applying for OECD membership,” said Stuart-Smith.
The American Chamber of Commerce in Thailand has argued that many other OECD members do not impose tax on global income, and those that do include exceptions, such as a waiver of the tax for residents of less than five years (such as Australia and Japan).
It also noted that Thailand’s main rivals for FDI, wealthy retirees and talent – such as Malaysia, Singapore, Vietnam and Hong Kong – have no such tax.
To get around the threat of tax on remittances and the global income of expatriates of a certain calibre, Thailand in September 2022 introduced a long-term resident (LTR) visa that targets wealthy global citizens, affluent pensioners, and highly skilled and “work-from-anywhere” professionals.
“It’s important to note that the LTR visa, administered by the Thailand Board of Investment (BOI), includes specific privileges designed to attract and support expatriates who can contribute significantly to the Thai economy,” said BOI secrerary-general Narit Therdsteerasukdi.
“One of the primary incentives is the tax exemption on foreign-sourced income for certain categories of LTR visa holders,” he noted.
Since the launch of the LTR programme – which is designed to attract one million applicants and generate 800 billion baht in investments within five years – more than 3,000 visas have been approved.
For those without an LTR visa, however, the uncertainty surrounding the Revenue Department’s impending tax law casts a long shadow, leaving many anxiously awaiting clarity on their financial future.
While the proposed taxation changes have raised concerns among foreign chambers of commerce in Thailand, they do not yet appear to be a major issue for incoming FDI.
“I speak with many foreign investors searching for factory sites in Thailand every day, and so far, no one has asked me about this tax law,” said an international property consultant who requested anonymity.
Applications for BOI tax incentives between January and September reached US$21.7 billion, up 42 per cent year on year, and a 10-year high.






