


Vietnam’s race for growth tests pace of energy transition: experts
Regional leaders are facing a ‘trilemma’ of balancing sustainable development, security and competitiveness
VIETNAM’S push for double-digit economic growth is turning the energy transition into an increasingly delicate policy challenge: how quickly governments can expand cleaner power and absorb transition costs without undermining household incomes, energy security or industrial competitiveness.
The problem is particularly acute in fast-growing South-east Asian economies, where rising electricity demand means governments have less room to tolerate shortages or sharp increases in energy costs.
“What really makes Vietnam specific is its very fast growth,” Dr Jens Arnold, country studies division head at the Organisation for Economic Co-operation and Development’s economics department, told The Business Times.
“When you grow very fast, you need much more growth in energy than in GDP (gross domestic product),” he said, underscoring the urgent demand for more renewables and cleaner technologies.
“How do you make this happen at a pace that matches these rising energy needs? That’s where things become complicated.”
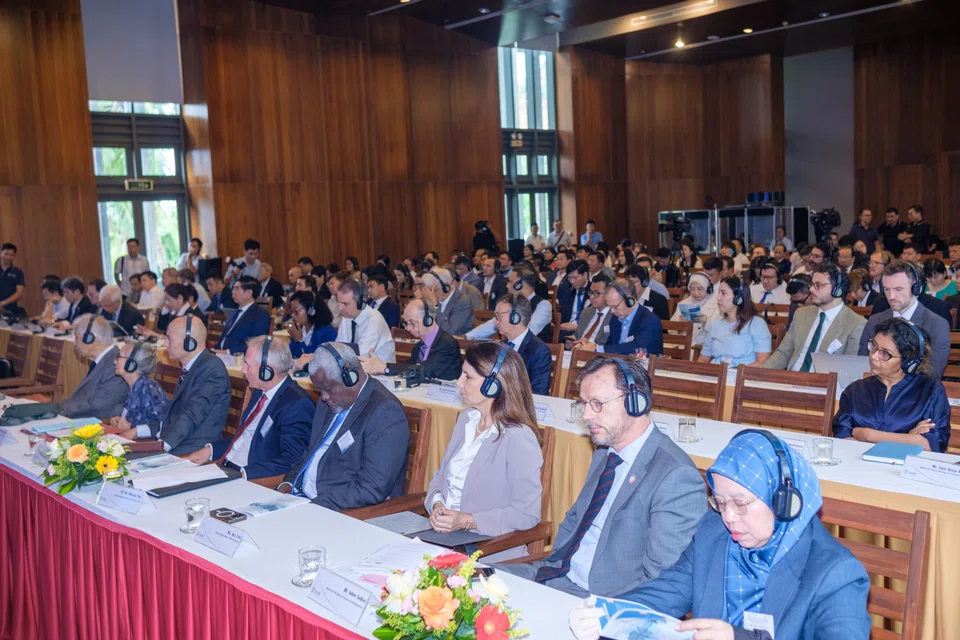
Dr Arnold was among more than 140 policymakers, scientists, economists and development-finance officials from 24 countries who gathered at the Quy Nhon Dialogue on Climate and Transitions over the weekend (Oct 10-11) in Vietnam’s central province of Binh Dinh.
He pointed out in one of the parallel discussions that transition was not only a question of deploying different energy mixes, but also of managing social safety nets, fiscal constraints and political pressures.
Vietnam, in particular, needs to add large amounts of power generation to support advanced manufacturing, infrastructure and industries to fuel its planned double-digit growth, while trying to reduce its reliance on coal as part of a target to reach net zero by 2050.
Speaking at the Quy Nhon Dialogue, Vietnam Deputy Prime Minister Ho Quoc Dung said the government does not see those objectives as mutually exclusive. “The issue is not choosing between growth and climate action, but how the transition can create new drivers for development.”
Dung added that cutting greenhouse-gas emissions in developing countries “cannot be separated from the requirements of growth”, energy security, food security, water security and economic stability.
Natural disasters and climate change reduce Vietnam’s GDP by an estimated 1 to 1.5 per cent a year, he pointed out. In 2025, disasters caused more than 104 trillion dong, or over US$4 billion, in economic losses and left 484 people dead or missing.
“The transition is only sustainable when it does not narrow development space, but instead creates new development opportunities for countries and people,” he said.
New markets, new positions
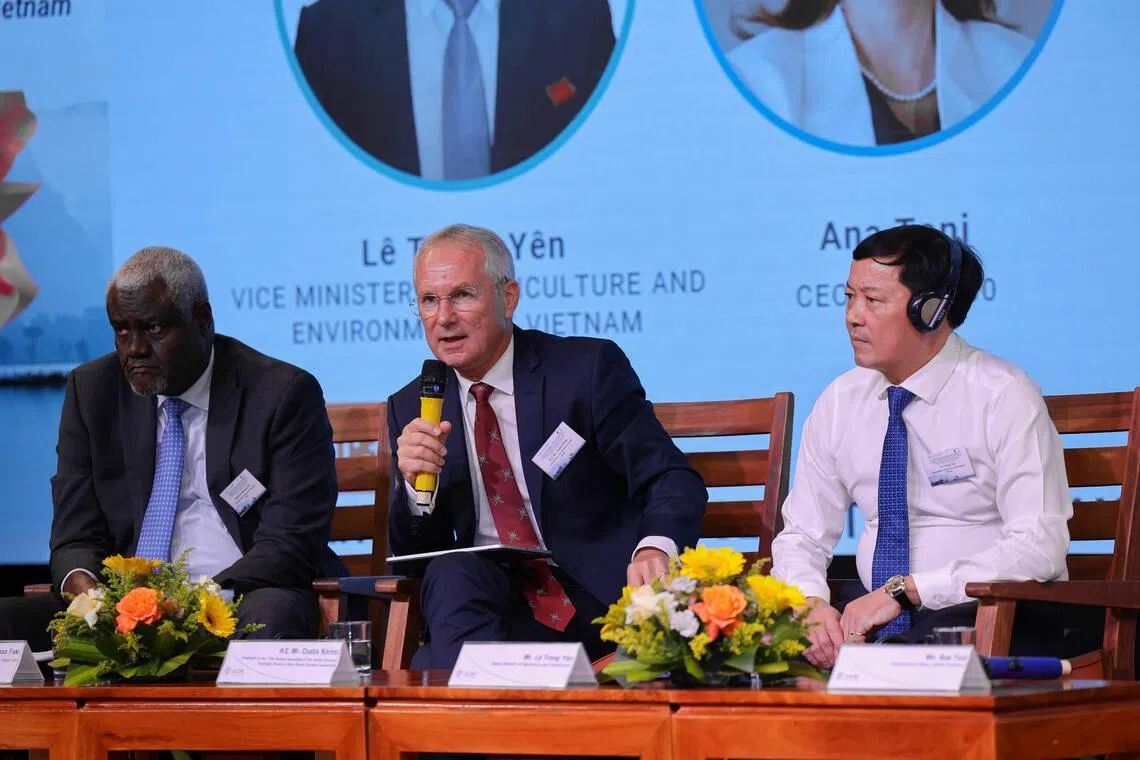
Csaba Korosi, former president of the United Nations General Assembly, described a “trilemma” confronting global political leaders – balancing sustainable development, security and competitiveness at the same time.
“The transition is creating new markets,” he told BT. “It will reorient investments from different segments of the market to other new segments.”
The more important question for Vietnam, Korosi said, is where it wants to position itself in the new markets.
“Those who are able to be leaders in the transformation will (find it) more beneficial, financially more rewarding,” he added. “Those who are only following and basically (taking) steps back, the development will become more and more costly.”
Governments may find it easier to revert to carbon-intensive fuels in the short term, Korosi noted, but they must consider whether those choices will “sacrifice their future market positions”.
Global climate negotiations alone also cannot guide transition efforts at the country level, he said. While forums such as the UN COP summits set overarching global policies, the challenges facing Vietnam differ sharply from those for other countries.
“The transition will be a long, demanding mission that requires integrated knowledge and dedicated, science-based regional platforms,” Korosi said, citing Singapore as a global model while positioning Vietnam as an emerging regional hub.
“We need these regional platforms working on a permanent basis.”
That imperative underpins the rationale for the Quy Nhon Dialogue, which aims to establish itself by 2027 as a recurring fixture focused on South-east Asia’s climate and transitions.
Power transition bottlenecks
Vietnam’s primary energy road map, known as PDP8, was designed to expand renewables to roughly 39 to 47 per cent of total capacity by 2030 while capping further coal expansion.
But the balance is starting to shift as policymakers confront delays in major power projects and the prospect that electricity supply may not keep pace with economic growth.
A Ministry of Industry and Trade report estimates Vietnam could face a power-capacity shortfall of over 4,000 megawatts (MW) in 2027, widening to almost 14,000 MW in 2030.
The country has begun another review of its power plan. The trade ministry said projects that are unlikely to be completed by 2030 should be replaced with more feasible alternatives, including coal-fired baseload generation.
Muralidharan Ramakrishnan, head of Asia-Pacific utilities at Fitch Ratings, said Vietnam’s experience during the power shortages of 2023 shows the danger of allowing supply to fall behind demand.
For the near to medium term, he said, policymakers may have to prioritise reliable and affordable electricity even if that complicates the emissions trajectory.
“Investing in coal is not (necessarily) bad if it is critical to ensure the availability of power at a reasonable cost,” the analyst noted, warning that sharply higher energy costs could weaken manufacturing competitiveness.
Financing the transition
Dung underlined at the Quy Nhon Dialogue that for developing economies such as Vietnam, the challenge of an economic transition is not only having more capital, but also gaining access to “funding at reasonable costs”, alongside technology and stronger domestic capabilities.
That will require closer links between public resources, concessional finance, multilateral development banks, climate funds and private capital, he said.
Still, bankability remains a primary hurdle for renewable and transitional power projects in Vietnam.
“In the absence of bankability, funding those projects is becoming challenging,” Ramakrishnan said, adding that while policymakers have responded to investor concerns step by step, “there’s still some more journey to be made”.
Nicolas Picchiottino, secretary-general of the International Development Finance Club, or IDFC, noted that public development banks can play a key role by raising long-term capital and channelling it into infrastructure, energy and other strategic investments. But their international borrowing costs are often closely tied to the sovereign rating.
Vietnam’s recent upgrade to investment-grade by Japan credit rating agency Rating and Investment Information provides a timely boost for the country’s foreign financing outlook to support its energy transition efforts, he told BT.
Still, traditional sources of public money and concessional capital are shrinking, Picchiottino added. “We really need the private sector to be more present.”
He also said that sustainability should increasingly be treated as part of financial risk assessements rather than as a separate policy objective.
“When you are achieving this double-digit growth, you need to ensure that it’s sustainable,” Picchiottino said.
“Sustainability is not linked to a decrease in profitability. On the contrary, when you invest in sustainability, you decrease your long-term risk.” THE BUSINESS TIMES
TRENDING NOW

Malaysian king buys stake in Singapore-listed mining firm expanding into rare earths
Family offices ‘kept captive’ by relationship managers turn to independent advisers, direct deals

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Could stablecoins be the future of money?

