



Will South-east Asia’s ambitious EV targets drive the region’s sustainable future?
Purchase prices and insurance costs remain a major hurdle for adoption
AS SOUTH-EAST Asian countries navigate the complex terrain of electric vehicle (EV) adoption, ambitious targets and transition pathways have become a focus of discussion. However, the critical question remains: are these targets sufficient to achieve the region’s long-term sustainability goals?
Both Singapore and Thailand have announced a target date to phase out the sale of internal combustion engine (ICE) vehicles. Other countries in the region have set alternative targets, including a minimum penetration rate for EVs.
Bold commitments are set out in the two countries. Singapore has aims for all new car sales and taxis to be of “cleaner-energy models” by 2030, with no more ICE vehicles on the roads by 2040. Thailand has committed to all new car sales being zero-emission by 2035.
Indonesia has no target date for when it will stop selling ICE vehicles, but has committed that its automotive fleet will be fully electrified by 2050. Similarly, Malaysia has committed to 50 per cent of its cars being fully electric by 2040, and 80 per cent by 2050.
These targets, while aspirational, face significant challenges. The nascent state of the EV sector means adoption rates will inevitably shift with technological, regulatory and social developments.
For South-east Asia to achieve its EV goals, further investments in infrastructure and affordable alternatives are essential.
Cost is a major hurdle
Cost remains a significant barrier to widespread EV adoption in this region. Even in Singapore, where the government offers attractive incentives such as the Early EV Adoption Incentive and the Enhanced Vehicular Emissions Scheme, insurance and road tax costs for EVs remain high.
Unlike Thailand and Indonesia, which are positioning themselves as regional EV manufacturing hubs, Singapore has minimal domestic manufacturing capacity for EVs, further driving up costs.
Insurance premiums for EVs are also higher than those for ICE vehicles, as insurers are still evaluating the risks associated with this new technology. Additionally, the high purchase price of EVs – driven by component costs – directly influences insurance costs.
While EVs may offer benefits such as reduced wear and tear, these must be weighed against the higher cost of replacing key components.
To compare the costs of owning a battery EV (BEV) and ICE vehicle across countries, we reviewed locally available models of an SUV with a 100kW to 150kW power output produced by a Chinese original equipment manufacturer (OEM).
Indonesia, where the use of motorbikes is more prevalent, was an exception. There, the leading battery EV model was a mini-compact 30kW model produced by another Chinese OEM.
The ICE models selected were comparable models produced by Japanese OEMs popular in the respective markets. But for Malaysia, a Malaysian vehicle was used, as the two leading Malaysian OEMs collectively account for over 60 per cent of passenger vehicle sales.
In Singapore and Thailand, the estimated total cost of ownership (TCO) for an EV that’s over 10 years old was marginally higher than that of a similar ICE vehicle – 4.4 per cent and 3.4 per cent more expensive, respectively. This was due to higher upfront and annual insurance costs, as well as higher annual road tax in Singapore.
The differences in TCO were more significant elsewhere, due to local nuances.
In Indonesia, the TCO of an EV was 55.9 per cent lower, due to the highly competitive annual running costs of the mini-compact models.
However, in Malaysia, the TCO was 32.1 per cent higher due to the domestic dominance of Malaysian car manufacturers.
While adoption incentives made EVs generally more affordable than ICE counterparts from international OEMs, EVs remained significantly more expensive than ICE models from the two dominant Malaysian OEMs. The situation will continue to evolve as Malaysian OEMs launch their maiden EV offerings.
Hence, while annual running costs are significantly lower in most of the countries reviewed, EV purchase prices and insurance premiums will have to be lowered to support the pace of EV adoption needed for the region’s transition.
Policy support to unlock EV potential
Policy support is critical to accelerating EV adoption. This includes not only direct measures such as target dates for ICE vehicle bans and road tax exemptions, but also less direct policies such as the rationalisation of fuel subsidies.
For instance, Malaysia plans to implement road tax for EVs from 2026, while grappling with the challenge of reducing the fuel subsidies that have historically kept ICE vehicles affordable.
In countries where oil and gas production significantly contribute to the nation’s gross domestic product – including Indonesia and Malaysia – outright bans on ICE vehicle sales may be politically challenging. Thus, hybrid and plug-in hybrid vehicles are likely to see higher adoption rates in these markets.
Rationalising fuel subsidies by limiting them to those in need could be a crucial step in making EVs more competitive.
Infrastructure: The backbone of EV adoption
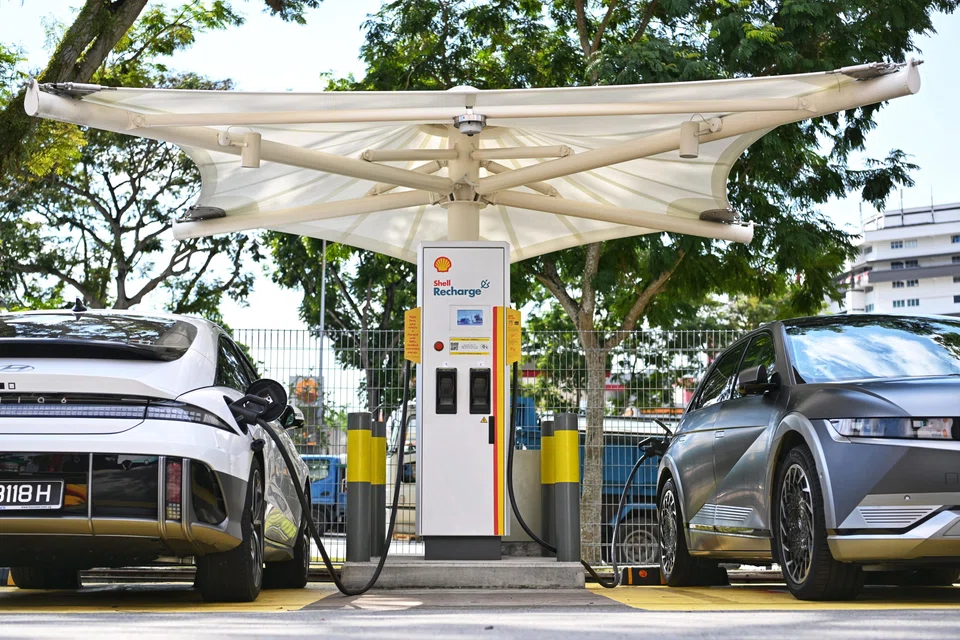
The availability of charging infrastructure is as critical as any other factor in driving EV adoption. In even the most advanced regional markets, infrastructure remains inadequate.
Thailand has more than 2,500 public charging stations as at December 2023, far short of the government’s target of 12,000 charging stations by 2030. Singapore’s EV adoption rate has grown significantly, but the country faces challenges in scaling up its charging infrastructure to meet future demand.
The expansion of charging infrastructure presents a significant opportunity for collaboration between public and private sectors. The development and financing of this infrastructure will be essential to supporting the region’s EV ambitions.
As countries continue their journey towards EV adoption, several factors will determine the success of these efforts.
First, it is critical to establish clear timelines for the phase-out of conventional ICE vehicles. These – coupled with complementary tax relief, incentives and subsidies – will be crucial for accelerating the transition.
Next, building the necessary infrastructure, including charging stations, is critical to making EVs a viable and attractive option.
Finally, limiting fuel subsidies to only those in need will be important to encourage a shift towards more sustainable alternatives.
While EV sales penetration rates are expected to rise, it will take time for EVs to become a significant percentage of the overall vehicle fleet in any of these countries.
Given that the average lifespan of a vehicle spans years and that meaningful EV sales have only recently commenced in 2022 and 2023 in most regional markets, the road to widespread adoption will likely be gradual.
The prospects for significant strides in EV adoption vary from country to country within South-east Asia.
Thailand and Singapore stand out as leaders, with EV sales penetration rates rising notably over the past year. But in markets such as Indonesia and Malaysia, these rates remain low, and it may take time before consumer habits shift on a meaningful scale in tandem with infrastructure roll-out and fuel subsidy cuts.
South-east Asia’s journey towards widespread EV adoption is filled with challenges, but also presents immense opportunities. With firm timelines, supportive policies, and robust infrastructure, the region can achieve its EV goals. A continued focus on these areas will be essential for ensuring that the transition is not only successful but also sustainable in the long term.
Bonar Silalahi is head of UOB’s sector solutions group and Justin Lim is head of insights at UOB’s industrials sector solutions group.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Singapore-based Ryde accused of pump-and-dump fraud in class action lawsuit

Malaysia’s F1 return: A low-cost second chance, possible Singapore boost

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

