China’s big GDP miss in Q2 may be the bad news needed to spur more policy support
Fiscal and credit easing may play a more important role in coming months
Angela Tan
CHINA’S economic growth for the second quarter came in at below consensus estimates, prompting some economists to cut again their full-year projection for the world’s second-largest economy, even as the big miss may be the bad news needed to spur more policy support.
On Friday (Jul 15), the National Bureau of Statistics (NBS) said the economy expanded 0.4 per cent from the year before in the second quarter. This is the lowest rate of growth since the first 3 months of 2020, when China effectively shut down to fight the virus, and its economy shrank for the first time in 28 years.
NBS spokesperson Fu Linghui told reporters that it was not easy to maintain a positive growth: “Looking at the next stage, the risk of stagflation in the global economy is rising.” Stagflation is a mix of slow growth, high unemployment and rising prices.
Goldman Sachs said: “The second quarter gross domestic product (GDP) data surprised on the downside, suggesting a heavier-than-expected toll on China’s growth from the April-May Covid lockdown, and mechanically leading to a downward revision to our full-year GDP growth forecast to 3.3 per cent year on year, from 4 per cent previously.
“We maintain our view that fiscal and credit easing may play a more important role in coming months.”
Goldman Sach’s economists had projected a 1.5 per cent on-year growth, and market consensus was for a 1.2 per cent growth, down from the 4.8 per cent expansion in Q1. On a quarterly basis, Q2 GDP fell by 2.6 per cent. As a result, China’s GDP for the first six months of 2022 grew 2.5 per cent.

Stephen Innes, managing partner at SPI Asset Management, said China’s official growth target of about 5.5 per cent for 2022 “now looks impossible to achieve”; he concurred with forecasts of a 4 per cent growth instead.
He added: “But we could easily read the big GDP miss as ‘bad news is good’, as it should signal a call to action for both the fiscal and monetary authorities.”
While April and May bore the worst of the impact from the Covid lockdowns, June’s data showed a broad-based recovery, except for a further drop in property investment, given that sentiment remained weak.
Industrial production rose 3.9 per cent on year in June, benefiting from the reopening of several Chinese cities. Retail sales rebounded sharply, reversing the 6.7 per cent decline in May, as consumption recovered, notably for services.
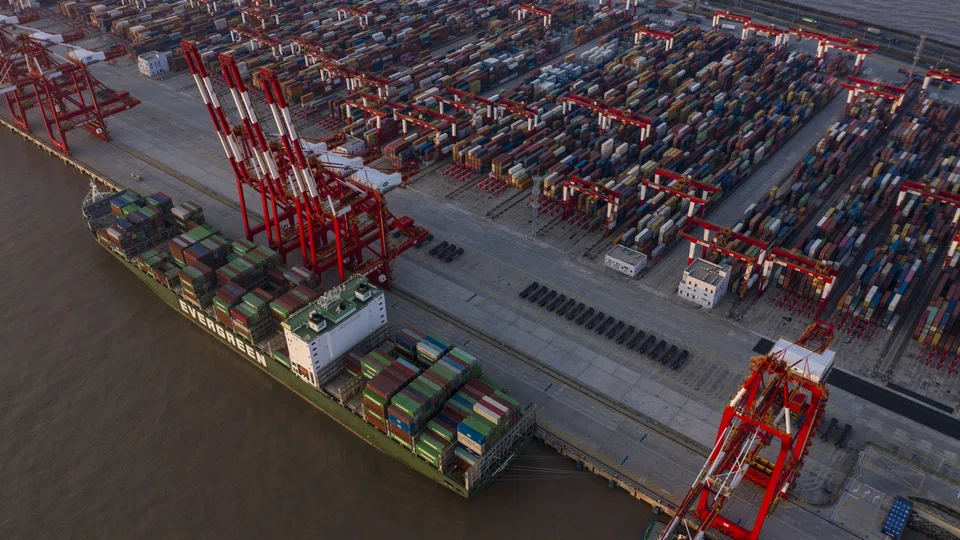
Exports exceeded expectations, growing 17.9 per cent, in June. Carlos Casanova, senior economist for Asia at Union Bancaire Privée (UBP), said that this was more likely the result of a backlog in orders rather than a sign that external demand was recovering.
He said: “The business cycle in Europe and North America is slowing, with the probability of recession in both key markets increasing quite significantly last month. Moreover, China is facing increased competition from other Asian markets. The latter have regained market share since their economies reopened (instead of being stuck in zero-Covid limbo), and their currencies have experienced stronger depreciations against the US dollar. We expect exports to moderate significantly in H2 2022.”
On the property sector, he said China is still in the middle of a housing-sector slump: “I expect that the broader environment will remain contractionary in 2022, before stabilising around H1 2023. That means it may still take several months before we see an inflection point.”
While unemployment declined to 5.5 per cent in June, unemployment among youth (those aged 16 to 24) rose to 19.3 per cent, up from 18.4 per cent in May.
Casanova warned: “This poses a challenge from a social-stability perspective, requiring additional measures to stabilise employment and provide opportunities for fresh graduates.”
The outlook for the second half remains challenging, with the Covid-19 still lurking around, property sector weak and global demand expected to slow down.
Erin Xin, HSBC’s economist for Greater China, said: “More proactive fiscal policy, still-accommodative monetary policy as well as regulatory and property policy fine-tuning are needed to pave the way for an investment-led recovery in the coming months.”
Richard Tang, China strategist and head of research for Hong Kong at Bank Julius Baer, said the weak Q2 growth reinforces the fact that the Chinese economy remains weak. But he said the worst of the growth cycle is over, and strong easing measures are still needed to stimulate a recovery.
However, he warned that while rising expectations on policy stimulus should typically boost market sentiment, the Chinese market has been hit by a wave of homebuyers refusing to repay mortgage loans for delayed projects.
“Investors are now waiting on the sidelines until they see more clarity on how policymakers will respond to minimise the risk to the financial system before committing more liquidity into the market,” Tang said.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.