


Asia underweight in private markets despite influence in global economy, say money managers
Three of the five largest countries by GDP (China, Japan and India) are in Asia, which offers private-market opportunities
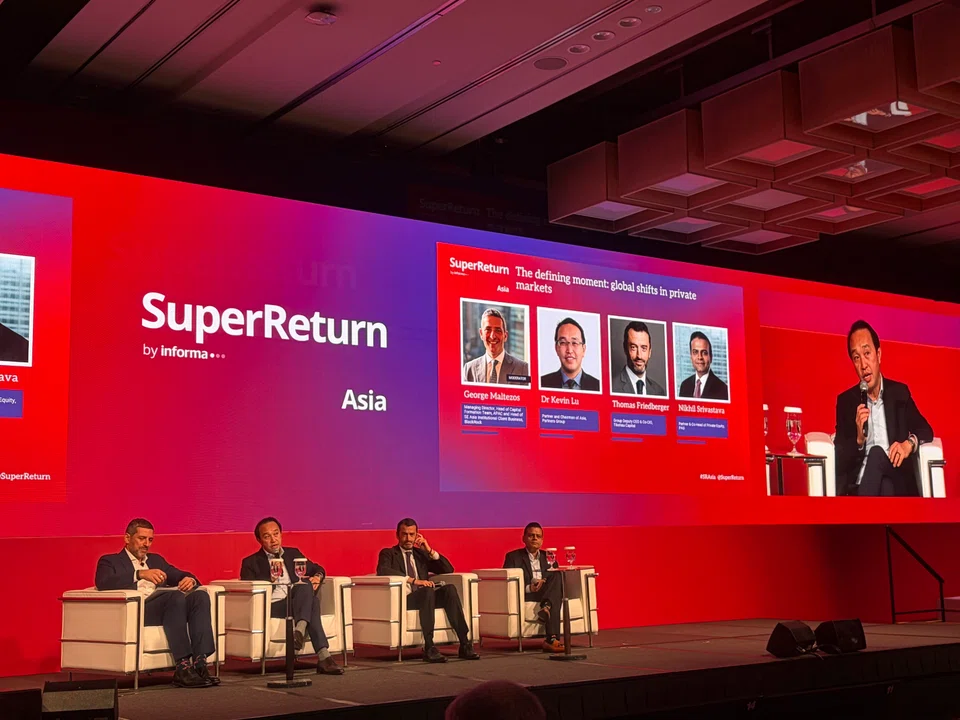
[SINGAPORE] Asia remains under-represented in global private-market portfolios despite its growing weight in the world economy, with investors pointing to opportunities in China, Japan and India as global capital flows shift.
Asia accounts for a third of global gross domestic product and roughly half of global growth, yet most limited partners (LPs) allocate only 10 to 15 per cent of their portfolios to the region at most, said George Maltezos, managing director and head of capital formation for the Asia-Pacific at BlackRock.
“Three of the five largest countries by GDP (China, Japan and India) are in Asia,” he said in a panel discussion at private capital conference SuperReturn Asia 2026 this week.
Kevin Lu, partner and chairman of Asia at Partners Group, also cited these three countries as areas of opportunity.
“We do see China continuing to be interesting, but you have to find the right way to get your exposure, whether it is offshore, onshore, directly or secondaries,” he said.
South-east Asia, by comparison, is more fragmented, and needs more effort to “organise through”, he added.
Nikhil Srivastava, partner and co-head of private equity at PAG, said China went through a difficult period from 2021 to 2024, but buyouts are now an area that the firm is excited about.
Valuations have corrected meaningfully, he said, while financing conditions and the appreciation of the yuan have become more supportive, citing loan-to-value ratios of 70 per cent and interest rates below 2 per cent.
Srivastava also said capital could shift towards Asia, after substantial flows into US markets in the last five to 10 years.
US equity market returns have become increasingly driven by artificial intelligence, he noted. With heavy capital flows pushing valuations higher, some investment could move towards Asia – a trend already visible from the sizeable Asia buy-out funds raised, he added.
Why private markets?
The panellists said that private markets remain relevant for investors when it comes to managing their exposures.
Partners Group’s Lu said private markets enable general partners (GPs) to “intervene, control, (and) make an impact, whether it is financial or non-financial”, while allowing LPs to curate longer-term exposures without being subject to daily volatility.
Meanwhile, Thomas Friedberger, group deputy chief executive officer and co-chief investment officer at Tikehau Capital, pointed to two sectors in which private markets play an increasingly important role: defence and electrification.
Electrification, in particular, could be the best investment opportunity of the generation, he noted.
Infrastructure has also expanded as a private-market asset class.
Lu noted that it has seen major growth, with his firm’s exposure exceeding US$20 billion, bringing it closer in scale to the firm’s private equity business, even though infrastructure is a much younger asset class.
Cyclical and structural shifts
Panellists identified both cyclical and structural forces reshaping private markets globally.
Srivastava said that the significant amount of capital flowing into the US in the last decade could be affected by changes in the macroeconomic and geopolitical environment.
Structurally, he pointed to the reorganisation of supply chains leading to more uncertainty, and the impact of generative AI on private markets.
Friedberger also identified another shift – that of the growing convergence between liquid fixed-income and private credit.
Larger issuers, from the upper mid-market to investment grade, can choose from among private credit, leveraged loans, high-yield and investment-grade liquid credit, which could lead public and private credit markets to converge.
He also sees a broader shift in the use of equity, from companies focused on improving efficiency towards those providing resilience.
Investments are flowing into areas such as defence, decarbonisation, deglobalisation and digitalisation, and these sectors require massive financing where private capital can play a part, he said.
Against those global shifts, Srivastava said that one attraction of Asia is that its economies are at different points in their economic and market cycles and are less correlated with one another.
Major shocks can still affect the region, but individual Asian economies otherwise tend to follow their own trajectory, he noted. This creates opportunities for private-market investors, but that also makes local expertise particularly critical.
“It is quite a nuanced geography where you need to have boots on the ground, be able to understand each geography to be able to invest,” he said.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Stocks to watch: DBS, DFI Retail, Frasers Property, Clint, ESR-Reit, Centurion, Coliwoo
DFI Retail to bag US$340 million, Starbucks business in Asia in deal with Maxim’s Caterers

Green fuels, autonomous ships: How Singapore is future-proofing its shipping industry

