


Blackstone, KKR drive surge in private-equity deals in Korean beauty
Recent investments by Blackstone and KKR could help push deals made this year in sector past those in 2024
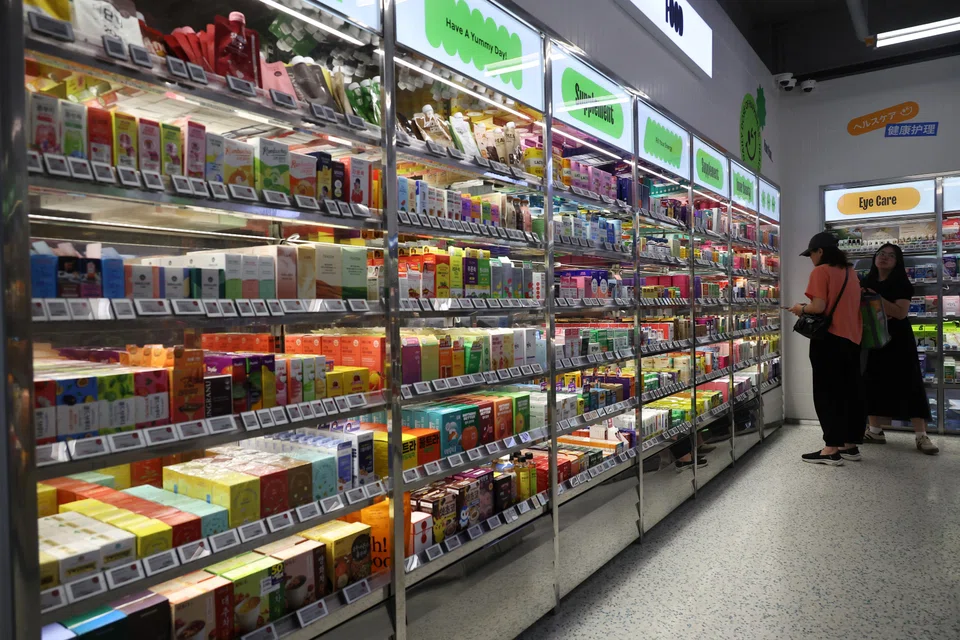
[SINGAPORE] From a premium hair salon chain to the popular skincare and make-up brand Skinfood, private-equity (PE) investors are scooping up assets in the hot South Korean cosmetic products and personal care sector.
The latest investments by PE giants Blackstone and KKR – their first acquisitions in the K-beauty sector – could push 2025 moves past the total value of deals logged last year, according to data compiled by The Business Times.
KKR announced on Sep 4 that it would fully acquire South Korean cosmetics packaging company Samhwa Co from TPG for around US$528 million. This came two days after Blackstone said that it was making a “significant investment” in South Korean premium haircare business Juno. While the world’s largest alternative asset manager did not disclose the terms, Blackstone is reportedly buying a majority stake in Juno that would value the company at 800 billion won (S$739 million).
The two transactions, together with four other mergers and acquisitions (M&A) in the K-beauty sector reportedly inked so far this year, bring total deal value to US$1.41 billion. That is 85 per cent of the US$1.65 billion in a record 18 deals logged in all of 2024, according to data from Korean advisory firm MMP.
Domestic PE investors are also active. Goodai Global, known as the South Korean L’Oreal, reportedly teamed up with Hahm Partners to buy Skinfood for US$108 million.
Industry experts see more legs to the boom, as the global appeal of K-beauty products and services is not a short-lived trend.
Eugene Cook, head of Korea at Blackstone Private Equity, told BT: “When you speak to beauty experts at even the most global companies, there is a strong recognition that consumers, regardless of age group, actually are demanding or seeking K-beauty as part of their skincare and beauty regimen, whether that’s colour cosmetics, skincare and now increasingly haircare as well.”
Riding “Hallyu” wave
The boom in K-beauty dealmaking is riding on the “Hallyu” or Korean wave. Referring to the rising popularity of Korean pop culture that largely began in South-east Asia and China in the late 1990s, it has since engulfed many parts of the world. Interest in Korean pop culture through its music, television series and movies is spilling over to fuel demand for beauty products such as skincare and cosmetics.
South Korea’s food and drug safety ministry said the country was the world’s third-largest exporter of cosmetics in 2024, up one place from 2023. By value, shipments of cosmetics rose 20.3 per cent from 2023 to US$10.2 billion last year. That compares with US$23.3 billion for France, and US$11.2 billion for the US.
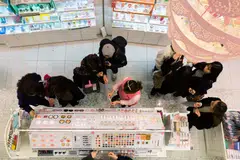
A January report by Research and Markets said that it expects the global K-beauty products market to grow annually by 8.97 per cent between 2025 and 2033, to reach US$31.8 billion in 2033.
While K-beauty has found a more natural affinity in the US given its sizeable Asian community, the sector’s appeal has also grown in Europe in recent years, said David Braga Malta, thematic health principal at Pictet Alternative Advisors.
Just a year ago, French healthcare-focused PE fund Archimed spent about US$742 million on Korean skincare-device maker Jeisys Medical – the first foray of a European player into K-beauty.
The global reputation of K-beauty, its competitive moat and potential to scale are the key reasons for KKR’s investment, said Hong Hi-joo, its director of private equity.
“The K-beauty ecosystem has established itself as a global trendsetter, with innovative products appealing to diverse consumers worldwide. Packaging has emerged as a critical differentiator for premium brands, with companies like Samhwa providing the technological innovation that helps these brands tell their stories more effectively.”
Even US tariffs are not likely to spoil the party, noted industry experts.
Rise in reverse pitches
South Korea’s beauty product exports to the US slumped 37.2 per cent to US$36.9 million in the first 10 days of August, compared with the same period in July. That was even though the 15 per cent tariffs came into effect on only Aug 7.
Cook said that “the initial slowdown” last month likely stemmed from buyers stepping on the brakes in placing orders until there is more visibility and clarity around the tariffs.
While the general K-beauty sector has demonstrated adaptability and resilience, Hong pointed out that Samhwa’s primary end-market consumers are in Asia.
Braga added that the global interest in K-beauty has led to an increase in so-called reverse pitches, where foreign buyers are approaching owners, asking them to sell, instead of owners seeking buyers.
This trend, which has been rising in the past three to five years, together with the current frenetic pace of dealmaking in K-beauty, are leading to concerns that assets might be becoming overvalued.
When reverse pitches start occurring, valuations can be managed. But once they are more frequent, sellers “understand that the interest is there, and valuations could go up”, said Braga.
Blackstone’s investment was reportedly made at an enterprise multiple exceeding 20 times Juno’s earnings before interest, taxation, depreciation and amortisation (Ebitda).
Globally, M&A in the beauty sector averaged about 13.5 times enterprise multiple to Ebitda from 2022 to the middle of this year, according to a July report by Capstone Partners, a Boston-based investment banking firm.
Valuation concerns
Cook declined to comment on the reported multiple. But he said that Blackstone believed that the valuation for the Juno transaction, “while potentially may be perceived as rich by the market, is appropriate”.
That is because Juno sits at the intersection of two themes: booming growth in K-beauty and quality franchisors, both of which drive “robust valuations”, he explained, adding that Blackstone decided to invest in Juno after eight years of hunting in the sector.
The Samhwa transaction, which was said to have let seller TPG more than double its investment made in 2023, also raised some eyebrows.
TPG reportedly bought Samhwa for around US$216 million. The US company declined to comment when contacted by BT.
KKR’s Hong said the investment was based on Samhwa’s advantages, such as its position as a market leader in key product segments.
While the glow-up in K-beauty is generating excitement, some market players point to the instance of Bain Capital’s unsuccessful attempt to sell its entire stake in Classys, a South Korean aesthetic medical devices company, as a sign of potential cooling.
The Boston-based private investment firm sold 6 per cent of its stake via a block deal for US$163 million in May. That was after it reportedly failed to find a buyer for its 60.2 per cent stake in Classys as potential buyers baulked at the valuation.
Market players BT spoke to about the deal said that the example is unlikely to signal that exits are getting tougher for K-beauty.
That is because device makers form just a part of the overall industry, where there is sufficient deal flow.
Like any investment, there are risks, even in a sector such as K-beauty where there is potential for the high-growth pace to continue.
The global beauty sector is trend-led, and celebrity clout can fade quickly, Preqin said in a report early this month.
“The volatility of consumer attention means a brand may go viral on TikTok one quarter, only to lose relevance the next,” it noted.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

Britain’s mansion tax shows the difficulty of targeting wealth

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

The only common thing in S-E Asia is that we all eat rice: Cisco’s Asean president
Singapore data centre operator DayOne opts for US IPO at likely US$20 billion valuation

