Buyers beware: China’s economic recovery may be painful and perilous
While a bullish consensus is building on Chinese equities, we believe a share price correction could be in the offing as growth fails to meet lofty expectations
CHINESE equities have been on a tear in 2023.
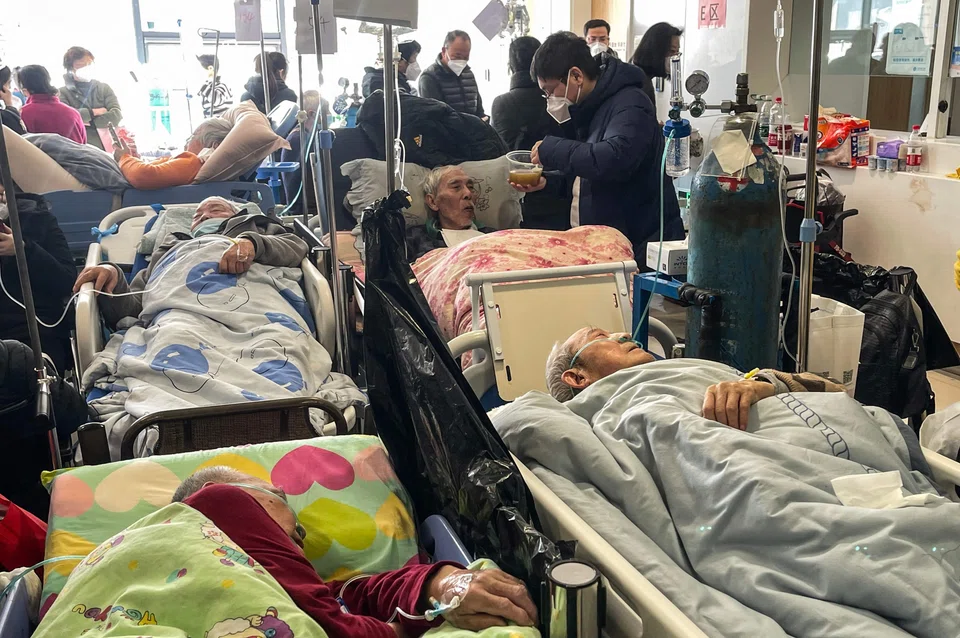
Despite a tidal wave of fresh virus infections, the Chinese government has moved forward with its plans to dismantle the zero-Covid policy that it adhered to for the past three years. Markets welcomed the move. Investors rushed back into Chinese equities as they position for a sharp rebound in economic activity.
Even though a bullish consensus is emerging for Chinese equities, we prefer to remain cautious as there are reasons to believe that the recent rally may not last.
Bigger Covid wave
China’s current Covid-19 wave has been confined to the urban areas so far, with rural areas remaining largely unscathed. This is about to change. As millions of people travel back to their hometowns for Chinese New Year, the virus will likely spread to the rural areas, where many are elderly, vaccination rates are lower than in cities, and healthcare systems are even less prepared to handle a surge in infections.
An even bigger Covid-19 wave could be coming, causing short-term shocks to labour supply.
Already, hospitals and financial institutions have been battling staff shortages. Factory activity contracted at the sharpest pace in nearly three years, as many factory workers and truck drivers were down with Covid-19. As a result, manufacturers have been forced to delay or cancel their orders.
No doubt, China’s dismantling of its zero-Covid policy was meant to revive the country’s stalled economy. However, the abrupt (and likely unplanned) reversal has so far been counterproductive, contributing to a huge surge in infections that has not only overwhelmed hospitals and crematoriums, but also caused serious disruptions to businesses across many industries.
China’s reopening is also ill-timed. The dismantling of its zero-Covid policy comes at a time when the rest of the world is slowing down. By the time this wave ends, the US and Europe could already be in a recession. As such, China’s exports will likely face headwinds in the year ahead.
Consumer spending could disappoint
One of the key drivers in China’s stock market rally is the expectation that consumption will rebound strongly following the dismantling of zero-Covid. We believe the actual pace of recovery could trail the high expectations placed on consumer spending to supercharge China’s economic growth.
For a start, a deep-rooted fear of Covid-19 remains ingrained in the population. Furthermore, the government has now left the public to fend for itself as cases surge across China, with drug shortages and soaring cremation prices all hampering consumer confidence.
China’s property market also remains plagued by a confidence crisis, with homebuyers unconvinced that developers have the ability to deliver pre-sold properties. Even if confidence returns, prospective homebuyers may not feel confident enough about their own financial situation, given the uncertain economic outlook and falling home prices.
The job market also points to a bleak outlook for consumer spending. Youth unemployment remains chronically high at 16.7 per cent. For those fortunate enough to find jobs, they are increasingly settling for lower pay. The average monthly salary for 2022 college graduates was 12 per cent lower than what 2021 graduates received, according to Chinese online recruitment firm Zhaopin. With another 11.6 million college graduates preparing to join the workforce this year, the labour market stress is likely to worsen.
It seems consumers are more likely to save than splurge in 2023.
Longer term structural issues
There are lingering long-term structural issues to worry about as well.
As President Xi Jinping consolidates power at the top echelon of the Chinese Communist Party, he is likely to push China towards a top-down state-controlled economic growth model, ushering in a low-growth period and imperilling the long-term profitability of private companies, as state goals are now more important than profits. The risk of policy mistakes will also be higher.
Even as the government has signalled that the crackdown on the tech sector is coming to an end, recent reports of government entities taking “golden shares” in units of Alibaba and Tencent suggest Beijing is moving to exert greater control over the private sector.
China’s foreign policy stance will likely be more assertive. Even if China seeks warmer relations with the West, the damage has already been done. Under President Xi’s leadership, China’s many years of aggressive “wolf-warrior” diplomacy has damaged the trust and goodwill built up over the years with the West. China will also likely adopt a harder line against Taiwan.
China’s abrupt policy shifts also mean foreign firms may be less confident that their operations would not be disrupted. As China becomes an increasingly challenging (and uncertain) place in which to do business, multinational companies have been willing to pay higher costs to manufacture elsewhere. This shift away from China is likely to accelerate.
Share price correction coming
While a bullish consensus for the Chinese equity market is emerging on Wall Street, we remain unconvinced. We believe a share price correction could be in the offing as economic growth eventually fails to meet lofty expectations.
At the asset class level, we now have a preference for fixed income over equities.
Within fixed income, our preference is for short-duration bonds, with the Nikko AM Shenton Short Term Bond SGD, LionGlobal Short Duration Bond Cl A Dis SGD, and the United SGD Fund Cl A Acc SGD all suitable options. An unconstrained bond strategy, such as the Allianz Global Opportunistic Bond Cl AMg Dis H2-SGD, is also viable as it allows for a better management of interest rate risk in this tough environment.
Within equities, the US and Japan now stand out as more attractive options compared to Chinese equities. For exposure to US and Japan, we recommend the JPMorgan Funds - US Value A (acc) USD and the JPMorgan Funds - Japan Equity A (dist) SGD, respectively.
Furthermore, given our expectation that inflation is likely going to be higher for longer, commodity-linked equity strategies such as the BlackRock Natural Resources Growth & Income A2 USD will also be amongst the winners. The shift of production away from China will also benefit Asean equities, which investors can access via the Principal ASEAN Dynamic Fund Class SGD.
The writer is a senior portfolio manager of the research & portfolio management team at FSMOne.com, the B2C division of iFast Financial. The latter is the Singapore subsidiary of SGX-listed iFast Corporation Ltd.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services