


China’s looming confidence crisis makes it even harder to achieve 5.5% growth target
Angela Tan
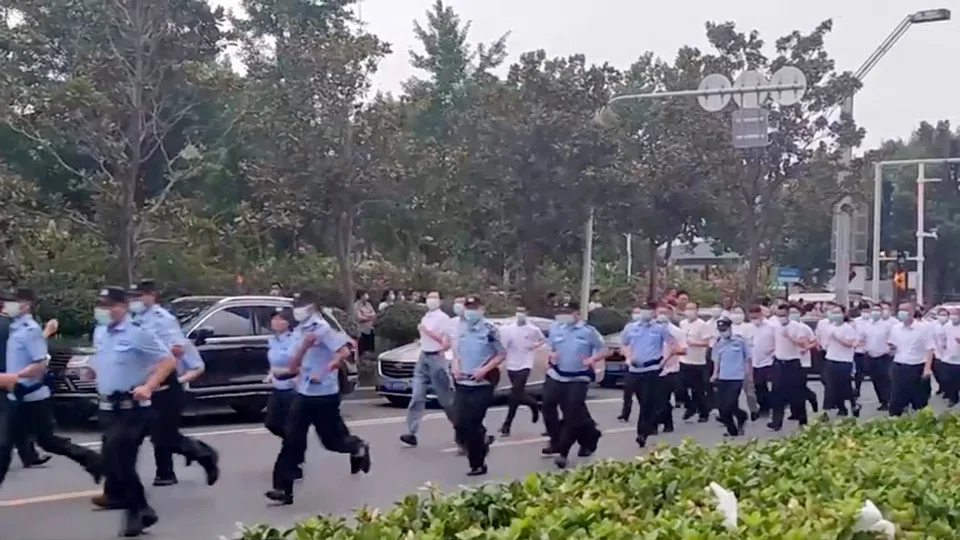
THE list of concerns facing China is getting longer. First, Beijing defanged its tech tigers such as Alibaba, Meituan and Tencent. It also removed the spiritual opium gaming from under-18s; battered the after-school tutoring sector to pulp; and defused what it perceived to be a potential time bomb in the over-leveraged real estate sector. Then, there is its unsustainable dynamic zero-Covid policy that has locked down entire cities; health code systems that double up as policing aid that stopped bank depositors in Zhengzhou, Henan, from protesting.
Now, concerns that the Henan bank scandal - which saw 40 billion yuan (S$8.3 billion) deposits disappear - may not be an isolated case. As if Beijing doesn’t have enough on its plate as it fights to boost its economy, news of mortgage defaults across 22 cities are threatening to smother any remaining spark of confidence left in the world’s second-largest economy, and disrupt order ahead of the crucial National Congress of the Communist Party.
Investors will be watching the data deluge coming out of China on Friday (Jul 15). Many economists are expecting the harsh lockdowns to hit growth in the second quarter. Estimates range from a 1 per cent contraction in gross domestic product (GDP) to a 1.5 per cent expansion on year. Performance will be mixed, with the external and housing sectors dragging all others.
Carlos Casanova, senior economist, Asia at Union Bancaire Privee (UBP), is among those who expect Q2 GDP to contract 1 per cent on year, while acknowledging that there could be upside, depending on credit growth and how resilient domestic consumption was in June.
China’s housing sector slump and rising inflation are expected to continue to have a drag on domestic demand.
“Regardless, we expect that economic activity will stabilise to around 5.0 per cent year on year in the second-half of 2022, assuming authorities continue to provide adequate fiscal and monetary policy support and move progressively towards economic reopening,” Casanova said. For now, the Swiss private bank is keeping its 2022 GDP growth forecast for China at 3.7 per cent. Beijing has an official target of around 5.5 per cent for 2022.
Industrial production could possibly see a 4 per cent improvement in June, as Shanghai emerges from a 2 month long Covid lockdown. China’s Purchasing Manager Index (PMI) for June already supports this, with factory activity expanding at its fastest in 13 months.
Beijing’s efforts to encourage bank lending seems to have gained traction, with bank loans jumping in June. New yuan loans grew by 2.81 trillion yuan in June, from 1.89 trillion yuan in May. Long-term loans to corporates rose, along with mid to long-term loans to households. Significant credit growth also came from government-related entities.
But not all economists are convinced that all of the loan growth went to economic activity.
ING for one noted that while corporate loans growth was significant, some of the data hint that loan demand was smaller than loan supply. Some of the corporate loans may have been deposited back into the banking system in the same month.
“This would be similar to 2016 when the government urged banks to boost loan growth to support the economy,” ING said.
Friday’s data may well show that the worst is over, and that Q2 was the trough, as BlackRock economists said.
But behind the optimism, they, like many other economists, are wary. Plenty of uncertainties remain. Growth in May and June as well as coming quarters may not be enough to make up for the slowdown in Q2. Beijing is unlikely to achieve its 5.5 per cent growth target.
For that to happen, Beijing needs to be more aggressive in its fiscal and monetary policy support. This is easier said than done. Wary consumers and investors hold the key to China’s economic growth target. The problem is they are not spending.
While June retail sales are likely to reverse the 6.7 per cent on-year drop in May, sentiment is still fragile. Unemployment is high. About 1 in 5 Chinese urban youths are unemployed, the highest since the government started to publish the data in 2018.
The housing market, notably in third tier cities, is not out of the woods. The financial leverage for Chinese developers is still high - almost 3 times that of global developers. This means the growth for Chinese developers over the medium term will be constrained by debt.
UBP expects property investment to fall further to minus 4.5 per cent on year year-to-date in June, led by a minus 33 per cent on year year-to-date decline in residential property sales.
It is no longer about regulations or cutting home mortgage rates. It is about households feeling very uneasy about their future, preferring to save their money. This kind of sentiment is hard to turn around in the short-run.
But this is to be expected, in the aftermath of the massive layoffs in tech, education and property sectors. With more pain on the horizon, China desperately needs a quick fix.
This is unlikely to come from an external boost given that global growth is facing downward pressure, with economists predicting a 50 per cent chance of a recession as interest rates rise. If we really have to don rose-tinted glasses, perhaps one can say that pessimism on China is close to or at its peak, and 2023 could be brighter. We can also look to science and hope that Covid-19 would eventually peter out like past pandemics.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

32 companies, 6 individuals bag accolades at Singapore Corporate Awards 2026

Can a first-time homebuyer couple earning S$18,000 a month afford a new EC unit?

Floods compound Philippine growth woes from public-works scandal

