China’s reopening to spur Asean growth, but may also draw equity investors north
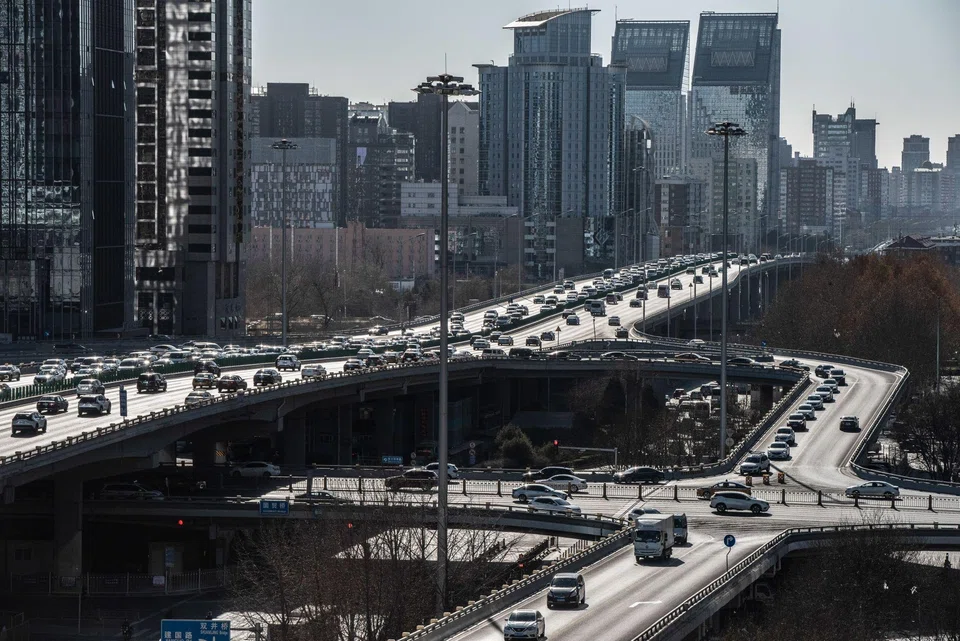
THE economies of Hong Kong, Thailand, Singapore and Malaysia may benefit the most as China reopens its borders. But when it comes to equities, past Asean winners could underperform as they have become expensive relative to North Asia in 2023.
Morgan Stanley said China’s faster reopening will be an “additional pillar of domestic demand support in Asia, while also imparting the largest positive spillover effects to the rest of Asia”.
Asia’s growth is expected to improve from a trough of 2.5 per cent in the first quarter of 2023 to 5.1 per in the second half of 2023. Morgan Stanley lifted its 2023 growth projection for China to 5.4 per cent, from 5 per cent. This compares with the market consensus of a 4.8 per cent growth for 2023 and around 3 per cent for 2022.
Nomura economist Sonal Varma also believes it is Asia’s time to shine: “Once the global dust settles, we expect Asia to outperform, with the region attracting large capital inflows, owing to its better growth prospects and stronger fundamentals.” She expects Asia’s 2023 GDP growth to rebound to 4.3 per cent, while the US and Europe experience a more tepid U-shaped recovery.
Hui Shan, chief China economist at Goldman Sachs, said Hong Kong and Singapore would benefit the most from the trading of goods as China reopens. Their GDPs could potentially rise 2.7 per cent and one per cent, respectively. Taiwan, Australia and Malaysia could also see a moderate boost to GDP of about 0.4 percentage point.
From a tourism perspective, Hong Kong and Thailand may benefit the most when China removes visa restrictions and outbound travel gradually normalises.
Shan said: “For Hong Kong and Thailand in particular, the current account boost could be as large as 6 per cent and 3 per cent of GDP, respectively, even without factoring in any pent-up demand for international travel after three years of strict zero-Covid policy.”
Some of the boost from trade and tourism could, however, be offset by the impact of higher oil prices.
Chinese oil demand is estimated to spike by one million barrels per day as borders reopen. “The negative GDP effect from higher oil prices would be the largest for Hong Kong, Singapore, and Taiwan (0.8-0.9 percentage point),” Shan added. “Taken together, Hong Kong looks poised to benefit the most from China’s reopening, with a potential cumulative GDP boost of 7.6 per cent, followed by Thailand, Singapore and Malaysia.”
SEE ALSO
With Asia’s exports and tourism expected to turn the corner, more strategists are revisiting the stock markets of North-east Asian economies that are more closely intertwined with China.
Morgan Stanley believes the equity markets have not fully priced in China’s reopening and reiterated its overweight stance on Chinese equities.
Desh Peramunetilleke, global head of microstrategy at Jefferies Hong Kong, said that despite the recent rally, most North Asian stock markets still have “an average upside of 20 per cent over the next year, with a 90 per cent hit rate”, based on price to book multiples.
Investors should focus on fallen angels such as Tencent, Alibaba and JD.com; topline leaders such as Kweichow Moutai and BYD; and Asian beneficiaries of China re-opening including BHP and Rio Tinto.
Peramunetilleke said investors should see any China Covid lockdown weakness as an opportunity to accumulate, and “avoid last year’s winners in Asean, India and Australia” due to high valuations after investors took refuge in them while riding the China storm.
Sectors favoured include China’s battered Internet stocks, the South Korea and Taiwan technology and chip sectors, Asian commodities, China and Hong Kong real estate, as well as Japan information technology. Sectors to avoid include India consumer, Asean financials, and Asian telecommunications and utilities – all of which have become expensive. Australia and Singapore real estate will be negatively impacted by higher interest rates; and the Japanese automobile space by earnings cuts and high operating leverage.
Jefferies is overweight Hong Kong, China (A and H shares), South Korea and Taiwan; neutral Philippines, Indonesia, Japan and Malaysia; and underweight Singapore, Australia, Thailand and India.
Still, Asian equities will be fighting three battles simultaneously in 2023: troublesome inflation, slowing growth and concerns over their foreign exchange reserves, said Sean Darby, global equity strategist at Jefferies Hong Kong. “There are three risks for Asian investors. First, a much-slower pace of reopening in China. Second, an over-tightening by the (US) Federal Reserve. Third, a too-rapid cooling of local real estate markets,” he said.
Investors will need to be quite nimble as long-term issues for China such as geopolitics and common prosperity are not going away. Any worsening news flow has to be met with a swift reversal in the country’s positioning, strategists added.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.