

China’s US$3.5 trillion stock rout deepens as profits sink, major stimulus stays elusive
Chinese leaders are in no rush to jump-start an economy that is slowing but at a tolerable speed
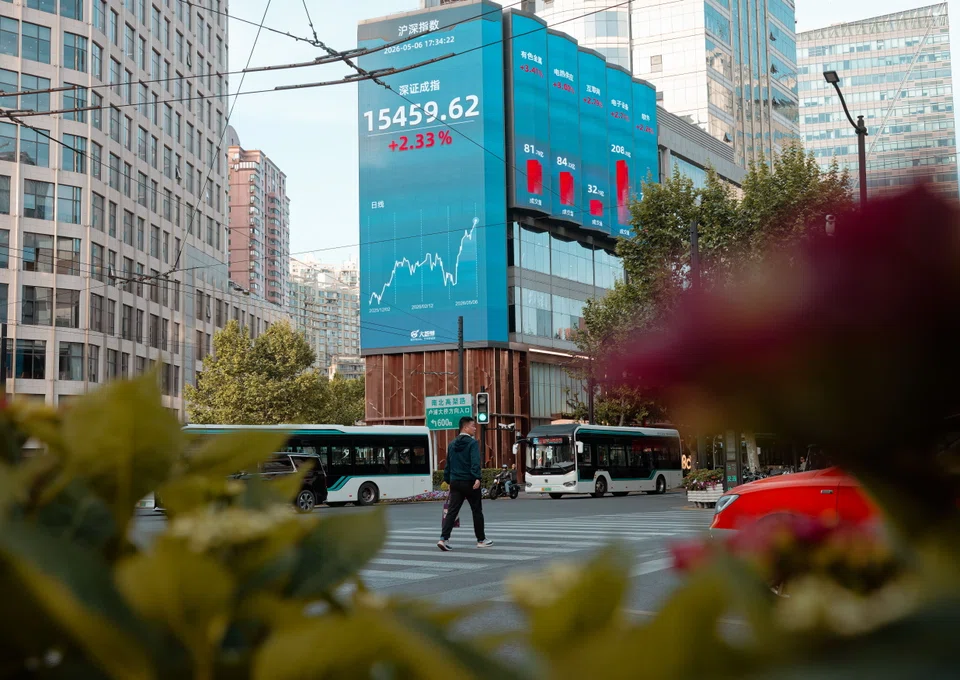
PESSIMISM has gripped Chinese stocks, with no end in sight for a deepening sell-off as investors confront the realities of an economy that is weak enough to erode corporate profits but not to trigger forceful new stimulus.
The world’s second-largest equities market has lost US$3.5 trillion in value from a peak in May, data compiled by Bloomberg show.
The rout intensified last week, pushing the onshore benchmark CSI 300 Index into a bear market and a technology sector gauge in Hong Kong toward erasing all its gains since Beijing’s sweeping growth support package two years ago.
At the heart of investor gloom is an unsettling realisation that a protracted consumption slump and the race-to-the-bottom mentality among businesses is taking a heavier toll on earnings across industries from banks to electric carmakers and AI model developers.
Further darkening the outlook is the growing perception that Chinese leaders are in no rush to jump-start an economy that is slowing but at a tolerable speed.
“It is too early to conclude that the worst is over,” said Ulrich Urbahn, head of multi-asset strategy and research at Berenberg. “The biggest concern remains profitability: China’s strength in production and exports is not translating consistently into stronger domestic demand, pricing power and corporate earnings.”
The third-quarter reporting season got off a disappointing start, with battery giant Contemporary Amperex Technology Co Ltd, or CATL, suffering a profit miss that was symptomatic of both weak demand and fierce competition.
The consensus 2026 earnings forecasts for the MSCI China Index members has declined by over 4 per cent since the end of March, according to data compiled by Bloomberg. The Hang Seng Tech Index, dominated by Chinese Internet firms mired in e-commerce price wars, has seen profit projections plunge more than 13 per cent during the period.
Yet even against the lowered expectations, the MSCI China’s constituents that have released results have missed consensus forecasts by an average of 9 per cent, set for the second-worst quarterly miss in two years, according to Bloomberg calculations.
Among them, AI infrastructure builder China Mobile’s January-September net profit tumbled 8 per cent on year amid cost pressures, while major materials firm Ganfeng Lithium Group Co also missed estimates on falling prices.
“CATL is the best poster child of what’s going on: great innovative company that’s doing great things but a victim of cut-throat competition and margin squeeze,” said Jason Lemire, chief investment officer at Bold Wealth Partners. “Competition is encouraged and generally brutal in China, not shareholder friendly.”
Profit squeeze
The earnings pressure has left companies, particularly China’s Internet behemoths that are in a tense race to fund costly AI infrastructure build-outs, increasingly out of cash. That has forced some of them to tap the equities market to raise funds, such as Alibaba Group Holding’s US$10 billion follow-on stock sale, which further diluted share value.
“I’d always weigh Japan, Korea and Taiwanese firms over China because they have better earnings,” said Stanley Tang, senior portfolio manager at Sumitomo Mitsui DS Asset Management. “If you ask me what China can do, hard to think of any - even further localisation of tech may not help to boost share prices.”
Weakening investor confidence is also showing up via other measures. Turnover in China’s onshore stock market is hovering near the lowest level since July 2025, while the outstanding amount of margin trades – bets funded by borrowed cash – fell to the least in a year.
To be sure, the slumping market has already prompted authorities to mobilise state funds known as the national team to prevent stock prices from spiralling out of control.
Meanwhile, the recent rout has boosted the appeal of Chinese equities to some investors. Bridgewater Associates’ China arm, for one, said it has turned “prudently optimistic” on local stocks, saying the declines in the third quarter were largely driven by liquidity while valuations aren’t high. It also argued that policy favours long-term capital formation and more money may flow into equities given low bond yields.
Still, scepticism abounds that while the national team’s rescue efforts may be a temporary fix, the market’s long-term prospect remains dim given policymakers’ reluctance to adopt big-bang stimulus measures to accelerate economic growth.
China’s third-quarter gross domestic product grew 4.5 per cent from a year ago, nudging expansion in the first nine months back into the government’s annual goal of 4.5-5 per cent. That target-meeting performance has given authorities more reason to stick to a drip-feed style of growth support, without compromising fiscal discipline or further reducing historically low borrowing costs.
“Policymakers are comfortable with the nature of economic growth,” said William Bratton, head of cash equity research for Asia Pacific at BNP Paribas. “As a result, either because they’re consciously keeping it in reserve or because philosophically they don’t believe in it, there’s no urgency to use fiscal measures to promote large-scale consumption.” BLOOMBERG
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services
TRENDING NOW
Singapore expects all parties to honour commitments, says PM Wong after Indonesia cuts gas exports

Gas supply cut from Indonesia accounts for less than 2% of Singapore’s daily gas demand: EMA

Singapore’s central gas buyer affirms Indonesia’s role as ‘important partner’ amid export review warning

If Europe goes to war, the fallout will be felt in East Asia

