


K-pop, Chinese games to drive Asia tech sector growth: Macquarie
Baidu, Tencent are among the research firm’s top 2026 Asian tech picks
[SINGAPORE] 2026 is poised to be a boom year for the Asian Internet sector, as companies pivot from consolidation to aggressive monetisation and ecosystem integration.
The resurgence follows two challenging years of model building and infrastructure catch-up against Western competitors, analysts from Macquarie noted in a report released recently.
The research firm identified 13 top picks across the region, with domains ranging from tech to entertainment and e-commerce.
Agentic ecosystems lead the charge
While Internet companies in Asia have long established their own forms of “super apps” – Korea’s Kakao and China’s WeChat are examples – analysts at Macquarie believe that the next leg of growth will involve integrating artificial intelligence (AI) into the system.
In fact, the report pointed out that some of the “super apps” have already begun implementing their own form of agentic AI – which involves the use of AI-empowered assistants to perform complex, multiple-step tasks.
“Internet companies are transitioning their super apps into ‘agentic ecosystems’, in which AI functions encompass a much broader scope … to capture a higher wallet proportion and return on invested capital,” the report said.
Take Korean messaging app Kakao as an example. Its latest “Kanana” update works inside group chats and can leverage chat contexts to streamline tasks such as organising events and summarising discussions.
It can even offer purchase suggestions to close the transaction loop.
In the domain of agentic integration, Macquarie has thus identified the Korean super app, alongside China’s Tencent and Alibaba.
Growth within digital infrastructure
But such ambitious AI integration would require more infrastructure to support it.
“The rising complexity of frontier models, accelerated industry implementations, and real-time data processing are pushing demand for more aggressive infra buildouts, including acquiring high-end computing and data centre resources,” the report noted.
Yet, the report noted that Asian Internet’s spending on capital expenditure is lagging the United States by approximately 18 to 24 months.
“We anticipate an aggressive acceleration through 2026,” it added, as analysts estimate the Asia Internet capex to expand to US$78 billion in 2026, from US$60 billion.
Leading this charge are hyperscalers such as China’s Alibaba, Tencent and Baidu, which were also among Macquarie’s top picks.
One advantage in their favour is that the construction cost of a data centre is significantly lower relative to that of their peers. It costs approximately US$2 to US$3 a watt in China, US$5 in Singapore and US$10 in the US.
Such low construction cost will benefit Chinese data centre firms such as GDS, which has been added into Macquarie’s “Marquee Buy” list.
Its report said: “We believe GDS is well placed to benefit from rapid AI infrastructure growth by major hyperscalers in China, supported by its Tier 1-focused land bank revenue.”
The research firm also identified Internet Initiative Japan (IIJ), one of the nation’s largest data centre-related names, as a top pick. “We think IIJ will benefit from increased bandwidth demand accompanying AI data centre growth.”
Entertainment-boosted strong tailwinds
Moving beyond tech, the report identified Asian content – such as Korea-Pop (K-pop), Chinese intellectual property (IP) and Japanese IP – as the next sector of growth.
“Asian content is no longer a niche export, but rather a global powerhouse,” said the report.
“With structural tailwinds from the wallet shift among young consumers, we believe K-entertainment should continue to command premium recognition.”
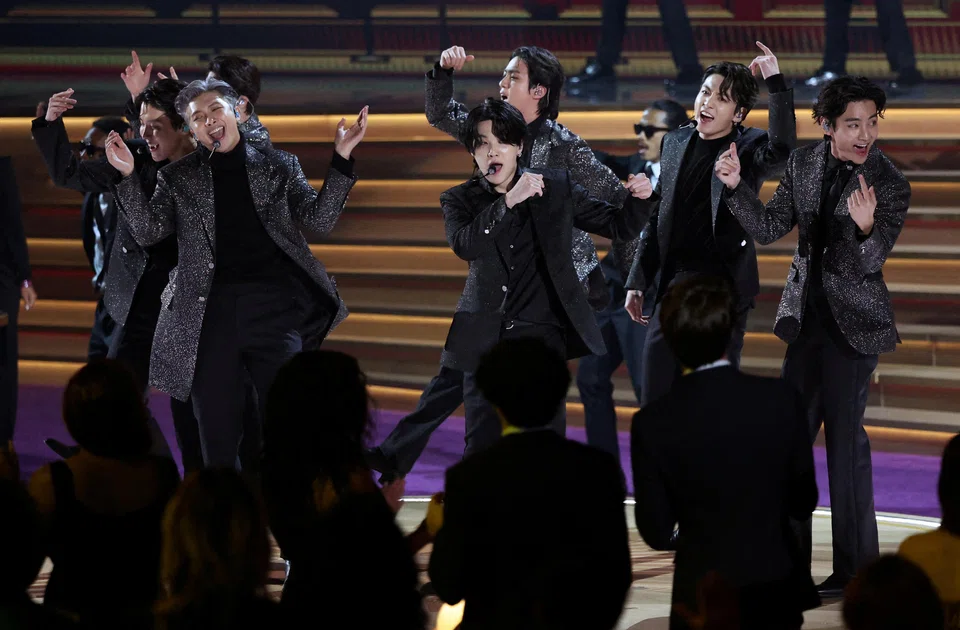
Catalysts such as the potential comeback of K-pop supergroup BTS and easing China-Korea relations will further boost the entertainment scene.
Companies such as South Korea’s Hybe – identified as the research firm’s top pick – will benefit from the growing entertainment sector.
Apart from film and music, Chinese game studios are also expanding their global footprints with enhanced earnings visibility and brand longevity.
Moreover, Asian IPs accounted for more than half the world’s top 30 mobile game gross revenue as of Dec 20, 2025, market data services provider Sensor Tower reported.
“Top-tier IPs are no longer confined to their original domains, but rather transforming into cultural touchstones that bridge physical and digital experiences,” the report noted.
Chinese video game companies Tencent and NetEase, as well as Japan’s Koei Tecmo and Konami were identified as the top picks in the video game sector.
Transaction platforms face stiff competition
The outlook for transaction platforms, which include those for e-commerce, remains mixed as competition intensifies.
Despite the headwinds, Macquarie identified Korean e-commerce firm Coupang as the top pick, citing optimism in its overseas expansion plans.
“We expect Coupang to continue to gain market share, thanks to its unparalleled logistics coverage and fulfilment expansion, supported by a favourable market consumption rebound,” it noted.
On top of expansion, analysts believe that market consolidation around the leading players – mainly Coupang and Korean online platform Naver – is likely to continue.
In South-east Asia, logistics player J&T Express is positioned to ride the growth of TikTok Shop (TTS).
The report said: “J&T’s strong relationship with TTS positions J&T to benefit most from rapid video commerce growth amid ongoing market consolidation,” the report noted. J&T was the sole logistics platform identified by Macquarie as the top pick.
Grab was also identified as a top pick, even as a major consolidation of players is likely in the Asean on-demand services sector.
“We believe 2026 will either see the merger of Grab and Goto, or see further progress towards that eventuality,” the report noted.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Deal between tycoon friends sparks scrutiny of Philippine power sector
Singapore’s S$80 million vertical farm must pass the 50-cent test to succeed

