

Making Asia great again!
WHEN China announced its re-opening in January 2023, a loud rejoicing reverberated throughout the region, propelling most market watchers to upgrade the outlook for regional economies poised to benefit from the positive flow-through from the expected recovery in the Chinese economy.
This optimism appeared to be short-lived as strong market gains seen in February and March of 2023 fizzled out as economic numbers came in lower than market expectations over the following months. By July 2023, other concerns emerged, including high youth unemployment numbers. Unemployment for 16-24 year-olds in urban areas hit 21.3 per cent in June, the highest since 2018 and triple that in the US. This is an area of concern as it points to lower consumption demand from this age group.
With global economic slowdown and elevated inflation, it is understandable that the world is re-focusing on China after it re-opened its economy. While business sentiment has recovered from pandemic lows, spending is coming off. The People’s Bank of China’s Consumer Willingness index (inclination to increase spending on home purchases) fell from the pre-pandemic level of 20.7 as at end-2019 to 16.2 as of end-June 2023.
China recently posted weaker-than-expected Q2 economic growth due to slowdown in retail sales and the continued weakness in China property stocks stemming from declining property prices. GDP growth was 6.3 per cent year on year (versus 4.5 per cent yoy in Q1 and expectation of 7.1 per cent yoy). Retail sales growth was 3.1 per cent in June versus 12.7 per cent in May. Meanwhile, exports fell 12.4 per cent yoy in June.
Cognisant of this, China has recently announced plans to boost and promote household spending on several products including household items for the homes, vehicles and electronic products. These measures are aimed at driving policies that will boost domestic consumption.
Overall, there is likely to be short- to medium-term volatility in the market as China’s slower-than-expected growth means that earlier corporate earnings expectations may have to be adjusted. The other major concern is the current weak property market, as seen from the 20 per cent decline in the Shanghai Stock Exchange Property Index, which declined from the 52-week high of 6779 in November 2022 to 5445 currently.
Attractive valuations
Key China equity indices have largely fallen this year, with energy, communication services, industry, information technology, telecommunications and utilities bucking the downtrend. After the euphoria in January 2023, Chinese stocks gave up gains in February and March, and the downtrend continued into July.
For the rest of 2023, we expect short-term weakness and volatility to remain, but valuations are starting to look interesting. On a price-earnings ratio, this has now come off to about 12.1 times this year’s earnings – below the five-year average of 15.1 times based on the Shanghai Shenzhen CSI 300 Index. Earnings are projected to grow 12 per cent in 2023 and 15.9 per cent in 2024 (from 281.09 in 2022 to 314.7 in 2023 and 364.65 in 2025).
Geopolitical tensions will continue to loom large; however, the silver lining is that this could have already been partially reflected in depressed current share prices and valuations. In addition, recent moves by the Chinese authorities to encourage consumption will help to stimulate domestic demand of certain products including household items and automobiles, and their supporting industries.
Mega trends
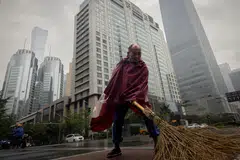
For investors with a long-term investment timeframe, it is also critical to keep an eye on some of the long-term mega trends including sustainability and generative artificial intelligence. In China, the sustainability trend will include electric vehicles, which could benefit from policy-easing. China remains a key economy with a large domestic population and is truly too big to ignore especially for long-term investments.
With the Chinese authority’s measures to boost domestic demand and the recent 15-day visa-free policy for Singaporeans, we expect more Singaporeans to visit China for both business and leisure. This is also positive for Singapore companies operating in China, allowing for freer movements of staff in and out of the country.
While China’s growth for this year has been adjusted down, we expect the longer-term economic growth strategies to still be a key driver for the rest of Asia and Singapore as it further strengthens its pole position as a key trading partner.
The writer is head of OCBC Investment Research
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services
TRENDING NOW
Far East Organization’s The Serra Residences sells less than a quarter of units released at average S$3,460 psf
A bumpy road ahead for some of Singapore’s fresh graduates in their job search
Philippine power giant First Gen rebuffs foreign offers, plans up to US$2.6 billion in expansion

No chicken feed: How Malayan Flour Mills built an empire from flour to fowl

