


Supply shock-induced slowdown in China could shave Asia’s growth by 1.3%: IMF
Angela Tan
A SUPPLY shock-induced slowdown in China could shave Asia’s growth by about 1.3 per cent in the medium term, said a senior official from the International Monetary Fund (IMF).
Growth in the world’s second-largest economy is projected to moderate to 3.2 per cent in 2022, from 8.1 per cent last year, and remain below 5 per cent for the next five years. This is expected to generate spillovers around the world, especially in Asia where growth is expected to moderate to 4 per cent in 2022 before rising to 4.3 per cent in 2023.
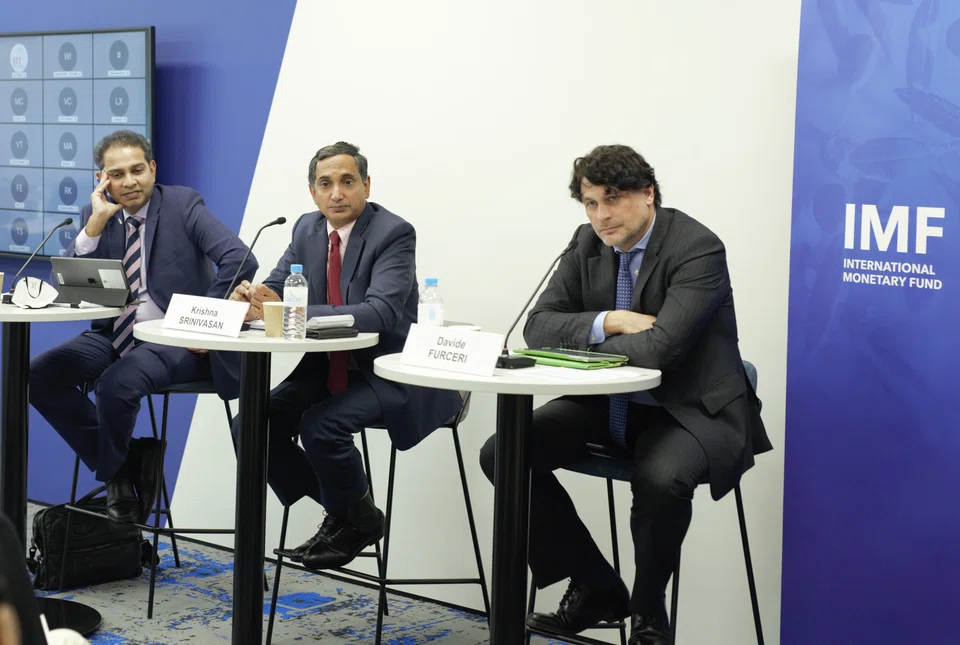
“Intra-regional trade has grown significantly in the past decade to more than half of total Asian trade,” said Krishna Srinivasan, director of the IMF’s Asia-Pacific department.
“Chinese demand absorbs one-quarter of the region’s exports, with 20 per cent absorbed by final demand and 5 percent re-exported,” he told a select group of media, including The Business Times, at the release of the IMF’s Regional Economic Outlook for Asia Pacific report last Friday (Oct 28).
The recent slowdown in China’s property sector may lead to regional spillovers, as the value-add absorbed by the mainland’s final demand for real estate averages about 0.6 per cent of gross domestic product (GDP).
It is estimated that a 2.3 percentage point drop in China’s GDP growth would result in only moderate short-term effects.
In the medium term, however, it could see a 0.3 to 0.9 percentage point cut in GDP in other countries, with Asia suffering the brunt of the impact.
The size and persistence of spillovers on the region depend on the type of shock confronting China. The IMF noted that the impact on regional growth is significant – about 1.3 per cent – when the fall in Chinese activity is caused by shocks to supply.
Similar-size spillovers to the region are seen from shocks as a result of a slowdown in Chinese consumption or real estate investment. However, the knock-on impact is more front-loaded, peaking within the first year.
A trade-related slowdown will have a more pronounced impact on countries that have stronger trade links, particularly Asia’s advanced economies.
In general, emerging markets which are major exporters to China could see an additional drag of 0.41 percentage point on their GDP, while those which rely on Chinese imports could see a 0.46 percentage point hit.
“However, Asia faces a larger hit from export exposures than from import exposures. And contrary to the general result, advanced economies in Asia are more heavily exposed than emerging economies, due to relatively higher imports from, and exports to, China,” said Srinivasan.
He said China’s frequent Covid-19 lockdowns and the real estate crisis have spread to other parts of the economy. The slowdown in China has now become broad-based across sectors, with consumer confidence very low. Internal weakness is compounded by slowing external demand, he said.
“In our baseline, we assume that the restrictions related to the Covid-19 pandemic will be gradually lifted in 2023, but we don’t see a quick resolution of the real estate sector crisis because that will take longer,” he said.
The turmoil in China’s property sector has deepened, as property developers are facing exacerbated liquidity stress. With a growing number of property developers defaulting on their debt over the past year, the sector’s access to market financing has become increasingly challenging.
Liquidity conditions are further impaired by tighter control over the sale of units before construction, which were previously an important source of working capital, and this has diminished the ability of developers to execute new projects.
Risks to the banking system from the real estate sector are also rising because of substantial exposure, said Srinivasan.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.






