

India trade deficit narrows in August even as oil risks loom
The gap between exports and imports stood at US$26.9 billion in August, compared with US$31.98 billion in July
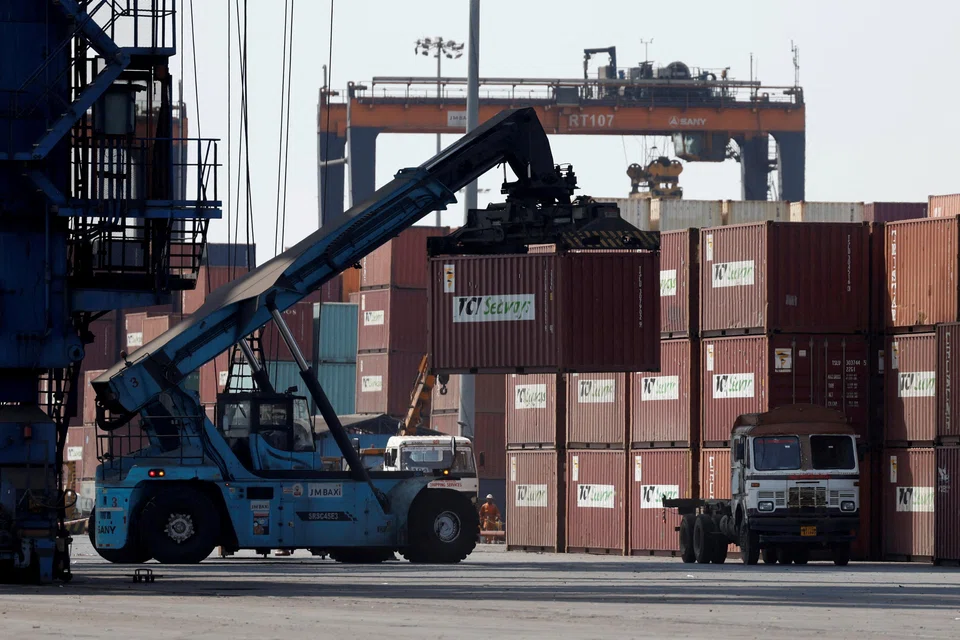
[NEW DELHI] India’s trade deficit narrowed in August even as instability across the Middle East and little sign that the US or Iran are ready to back down added to headwinds for the economy.
The gap between exports and imports stood at US$26.9 billion in August, compared with US$31.98 billion in July, data released by the Ministry of Commerce and Industry on Tuesday (Sep 15) showed. Economists had expected a deficit of about US$32 billion, according to a Bloomberg survey.
A narrowing trade deficit could ease some pressure on the already weak rupee, which is Asia’s second-worst performing currency this year.
Exports rose 26.1 per cent from a year earlier to US$43.81 billion in August, while imports rose 14.1 per cent to US$70.67 billion, the data showed.
Major demand for Indian goods is coming from the US, the European Union, and emerging markets, Commerce Secretary Rajesh Agrawal told reporters in New Delhi.
The trade data follows higher-than-expected economic growth in the quarter ended June, driven by manufacturing and services. Prime Minister Narendra Modi called the performance a “herculean feat” despite oil shocks, supply-chain disruptions and global uncertainty.
A prolonged conflict in the Middle East, however, remains a major risk for India’s economy, with surging oil prices threatening to push up the import bill. Oil surged past US$107 a barrel as disruptions to regional supplies intensified. India imports almost 90 per cent of its crude needs. BLOOMBERG
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Share with us your feedback on BT's products and services






