

Modi calls on Indians to put idle gold to good use to cut imports
New Delhi
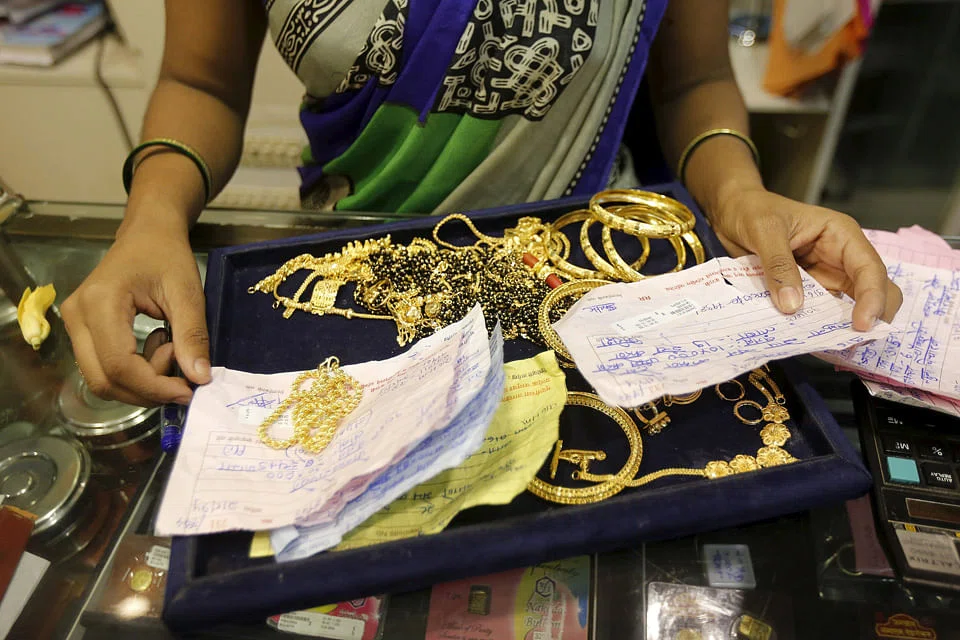
PRIME Minister Narendra Modi on Thursday exhorted Indians to put thousands of tonnes of gold stacked away in households and temples into productive use, launching three programmes aimed at cutting massive imports of the metal.
This would trim physical demand and reduce imports by providing people with alternative avenues for investment. At an event in New Delhi, Mr Modi announced the formal start of a gold-deposit plan, a sovereign-bond programme linked to the metal's price and introduction of locally minted coins, some bearing the face of Mahatma Gandhi.
Under the gold-deposit plan, investors can deposit a minimum of 30 grams with banks to earn interest, and at maturity either redeem the gold or cash, according to a government statement in June.
Banks holding the bullion will be free to sell or lend the gold to jewelers, thereby boosting supply. The planned sovereign-bond issue will be open to investors from Thursday up to Nov 20, the Reserve Bank of India said on Nov 3.
India's obsession with gold is rivalled only by China, with the metal used widely in wedding gifts to brides, religious donations and as an investment. The country has amassed about 20,000 tonnes of gold worth over US$800 billion in family lockers and temples,more than four times the amount that's held in Fort Knox in Kentucky.
Bullion will be a help to India's growth only when it enters the banking system, and large imports should be discouraged, Finance Minister Arun Jaitley said at the event in the capital, which comes a week before nationwide demand peaks. Bullion demand in India usually peaks in the final quarter of the year, with gifting during festivals, and continues with the start of the wedding season in November. The festival of Dhanteras, which falls on Nov 9, is the biggest gold-buying day in the year as it is considered to be an auspicious day to purchase bullion.
Mr Modi called the schemes an "icing on the cake". "Gold has often been a source of women's empowerment in Indian society, and these schemes will underscore that sense of empowerment," he said.
Last year India spent about 1.7 per cent of its GDP on gold imports that range between 800 and 1,000 tonnes annually. The deposited gold will be auctioned off from time to time to meet domestic demand for jewellery and coins.
"These schemes will be transformative for the Indian gold industry," said Somasundaram PR, World Gold Council's managing director in India. "However, the expectations from the schemes in the short term must be tempered as it will take time to build the infrastructure and products and for customer acceptance to grow."
"We should see this announcement and launch as a strong indication of an intention to put gold at the heart of the financial system and make it work for the Indian economy," he added.
Industry experts said many prospective depositors will not take the scheme due to concerns that the tax department could question the source of gold, while others may find conventional bank deposit rates of about 8 per cent more attractive. REUTERS, BLOOMBERG
TRENDING NOW
Trump welcomes China’s Xi at airport to kick off three-day state visit

As the Fed hikes interest rates, S-Reits sector could be overdue for consolidation

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Simba admits exceeding spectrum limits amid failed M1 deal; parent company Tuas’ full-year profit surges 277%

