

Looking for your second property abroad: Possibilities and pitfalls
It’s worth considering an offshore property, but be sure to do due diligence
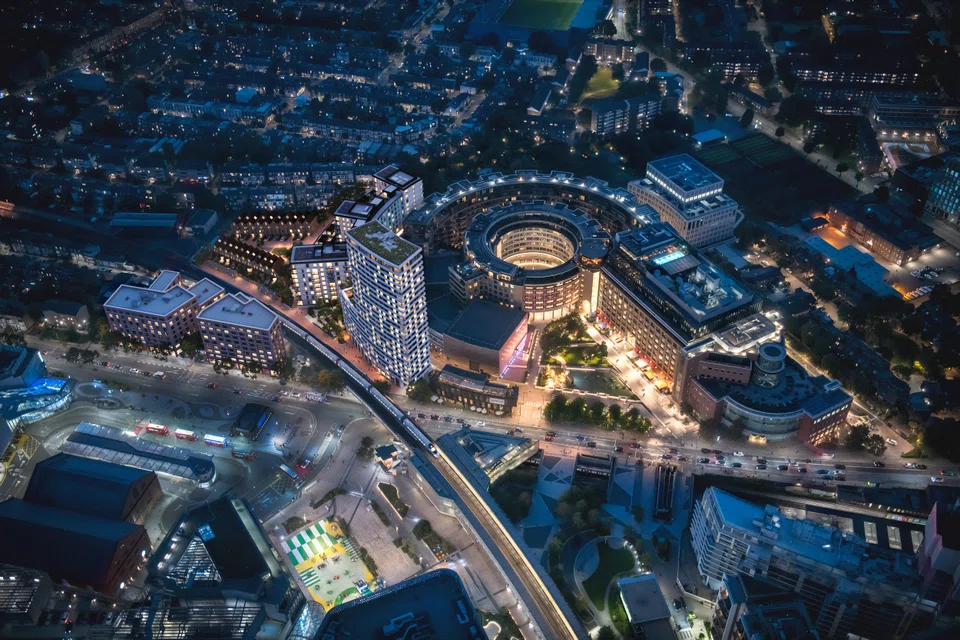
SINGAPOREANS’ love affair with property is so enduring, many will undoubtedly throw money at a second – or more – residential property, if they could. The only thing in their way is the daunting prospect of paying an Additional Buyer’s Stamp Duty (ABSD) of 20 per cent on the second home and 30 per cent on the third and subsequent purchases.
With the ABSD working out to S$200,000 for a S$1 million second property, it makes sense to look farther afield if you’ve got a serious property itch to scratch – and some moolah to spare.
Of course, the wealthy have long been buying overseas property, often scooping up the most desirable and pricey properties in a given location. These prime residential markets typically draw a significant number of international buyers, with Knight Frank’s Wealth Report 2024 showing that prices there surprised on the upside in 2023.
Of the 100 markets tracked in its Prime International Residential Index, 80 recorded flat or positive annual price growth, with the index posting a solid 3.1 per cent overall gain.
This is despite earlier anticipations for a much weaker outcome due to high borrowing costs and forecasts for a poor performance in stock markets.
Clarice Lau, Knight Frank’s head of residential sales (international project marketing), says that real estate in key gateway cities with solid underlying fundamentals – such as strong rule of law, a robust and diverse economic base, excellent education and healthcare systems, as well as a great lifestyle and global connectivity – consistently draws strong local demand among both home buyers and renters.
“Therefore, especially in times of uncertainty, investors gravitate to safe haven markets in search of capital preservation and income,” she points out.
Possible options
For middle-class Singaporeans on a far less generous budget, buying a second property overseas is still viable.
For instance, the report shows that US$1 million can get you just 344 square feet (sq ft) of prime property in Singapore, but 689 sq ft in Tokyo and 980 sq ft in Dubai. It could also get you a generous 2,293 sq ft holiday home in Phuket.
A traditional favourite for overseas homes among Singaporeans is London, which Lau says continues to retain its appeal. This is because many send their children there for their university education, with a significant number staying on to work in the city for several years.
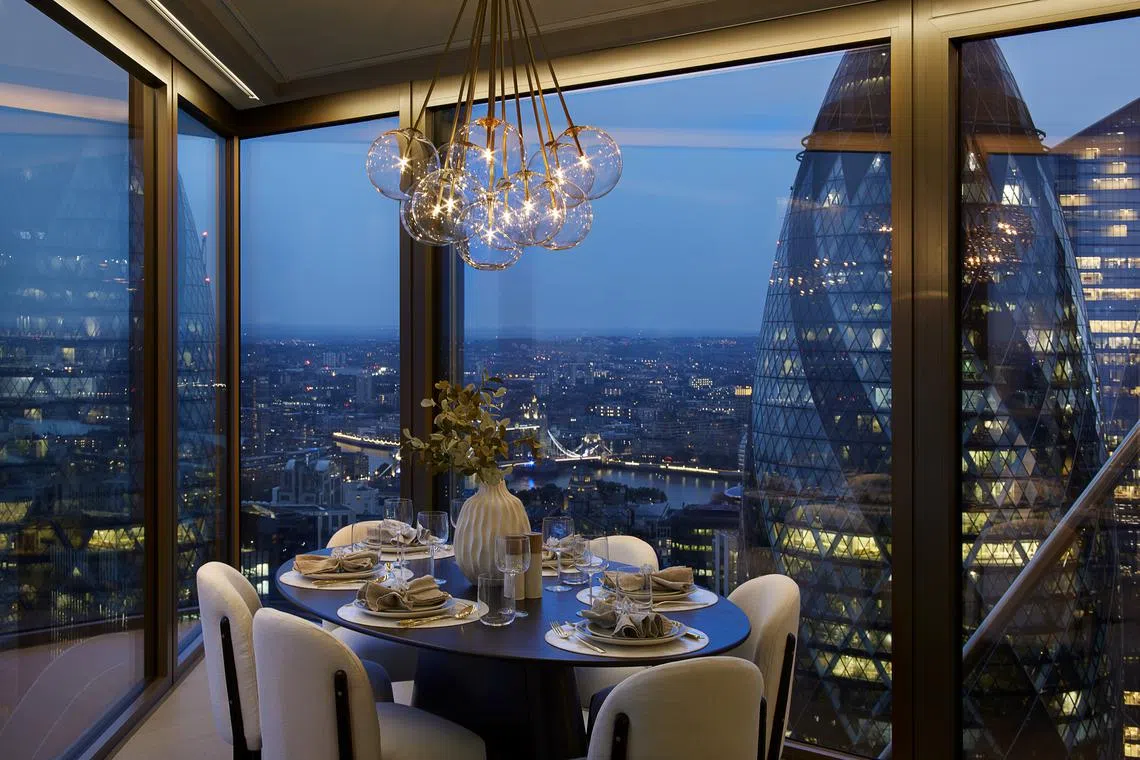
“Furthermore, there is a strong rental market there, driven by high demand and chronic undersupply, resulting in attractive rental yields compared to back home,” she says.
And while there have been economic challenges and headwinds following the Covid-19 pandemic, the sterling has also weakened, making London property more affordable for Singaporean buyers. Average gross yields in London range from 3 to 6 per cent, Lau estimates.
Furthermore, the new government in the UK has initiatives to bring residential properties back to their heyday, says Ruben Koh, senior director and head of international residential sales at Savills Singapore.
The examples he cites include the plan to build 1.5 million homes over the next five years, the regeneration of more properties, a home ownership target of 70 per cent, and new mortgage schemes for locals.
“This includes the anticipated lowering of interest rates from the Bank of England, which will trickle down to retail mortgages,” he says, estimating yields in the UK to range from 4 to 6 per cent.
Closer to home, Koh likes Australia, which he says “has never really felt a recession” and seems “immune to what is happening in the rest of the world”. That the Australian government is mending ties with China should bode well for its economy, even as local demand for properties has always been strong.
“However, investors (should) focus on cities such as Perth, as Sydney and Melbourne are expensive and have higher barriers to entry,” Koh suggests, adding that yields in Australia range from 4 to 7 per cent.
“Perth has just recovered from the high prices seen during the mining boom and now, the government is planning to keep (prices) sustainable. They’re encouraging new foreign investment and giving incentives to home buyers.”
Japan, which tops the list of Singaporeans’ favourite holiday destinations, is another of his picks, thanks to a favourable exchange rate and rental yields – ranging from 2 to 7 per cent – as well as the Bank of Japan’s near-zero interest rate policy, which makes mortgages affordable.
Knight Frank’s Lau also has Dubai on her list. According to the Wealth Report, prime prices there are 134 per cent higher at end-2023 than at the start of the pandemic. Yet, they are still significantly lower than in more established markets.
Like Japan, Dubai’s residential market is increasingly popular and offers great entry-level opportunities for Singaporean investors as the cost of acquisition is low, at about 4 to 5 per cent, she says.
Both markets also offer an attractive tax environment and rental market, as well as economic stability, with the average gross yields for Dubai and Japan ranging from 5 to 8 per cent and from 3 to 5 per cent, respectively.
Of professionals and perils
Overseas properties can be rented out and managed by lettings and property management companies which typically assist their investor clients with one-stop solutions ranging from purchasing, financing arrangements, letting and property management to selling.
In fact, when it comes to property management, Koh says real estate agencies in the UK, Australia and Japan undergo more stringent processes than in Singapore. Property agents there will be able to check for defects, ensure rents are paid, and repairs are done – the full turnkey solution for the investor.
But while owning an overseas home is an attractive idea, there is also much homework to be done.
For starters, buyers should speak to professionals in order to understand the rule of law and taxation in the market they are keen on. Trusted and experienced international agents can also do proper due diligence to ensure that the property is investor-grade, and that the developer is legitimate and will complete the project.
In addition, a firm with a presence in the market of interest will give buyers access to on-the-ground expertise, insights and research.
Meanwhile, pitfalls to watch out for include offers that are too good to be true, such as promises of very high rental yields and guaranteed buybacks, as there may be potential issues down the road, Koh cautions.
Buyers should purchase from reputable developers and do their homework on the property’s location as sometimes, a regeneration project may not take off, even though it’s been planned and approved.
They should also understand the culture of the city and country of purchase. “Many investors carry the Singapore culture into the countries they invest in, which is wrong,” he says.
And of course, everyone must be prepared for fees and taxes related to overseas property purchases. These include stamp duty, capital gains tax, inheritance tax, income tax on rentals, legal fees for buying and selling, property tax, service charges, lettings and management fees, and agent fees upon a sale.
If that doesn’t put you off as much as ABSD does, then perhaps it is indeed time to look overseas for that dream property.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW

World’s largest offshore wind platform by Seatrium consortium on track to be completed by 2028

Is stamp collecting enjoying an analogue revival or are its best days over?

GovTech retrenches another 38 staff in second round of layoffs

MBS adjusted property Ebitda falls 20.6% in Q3 with fewer high-roller visits, weaker hold

