

In 2025, global businesses must be ready for a new payments ecosystem
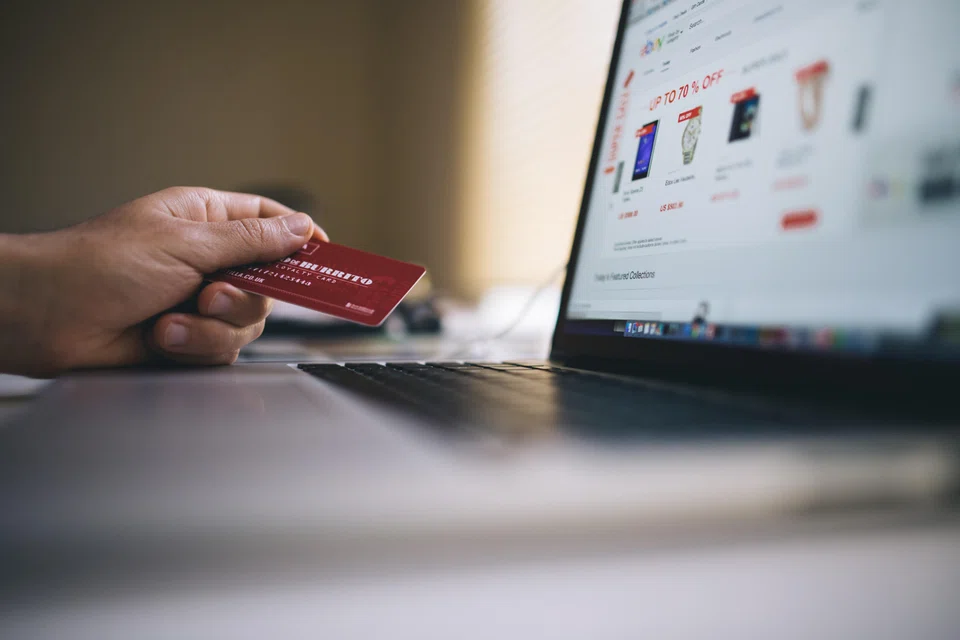
RECENTLY, e-commerce giant Taobao made headlines with its announcement that it would offer more payment options, including WeChat Pay, for Chinese shoppers. This integration of previously siloed competitive payment methods is not just a response to regulatory pressure – it reflects growing demand from consumers for flexibility and choice at the checkout.
As consumer expectations evolve, businesses across industries face a stark reality: The ability to offer diverse, seamless payment experiences is no longer a competitive advantage – it is a necessity, particularly for businesses looking to capture international markets.
Despite the clear market signals, many companies remain hesitant to meet customer demand due to the complexity of their payment infrastructures and the resources required to make change. But in delaying the inevitable, the opportunity cost of inaction is growing.
Payments no longer a back-office operation
A recent survey of payment leaders in Singapore, France, Australia and the UK revealed that four in five payment leaders say their payment technology needs to be replaced or overhauled. However, they face a range of hurdles – technical debt being one of the biggest.
Many companies, especially early ecommerce adopters, still rely on payment systems built over a decade ago. At their core, those systems were never designed for today’s fast-moving digital landscape. Payment teams have adapted with incremental changes, an approach that is akin to putting a Band-Aid on a deeper, more systemic issue.
The result is that over time, they have become overly complex, more embedded and increasingly challenging to manage.
Despite payment professionals recognising the need for an overhaul, another key challenge lies with a lack of buy-in from management, coupled with short-term thinking: the same study revealed that over three-quarters of those surveyed believed that their company’s leadership does not view payments as a priority.
Largely viewed as a cost centre, many leaders fail to see that payments can be a revenue driver; conversely, issues such as payment fraud, poor authorisation rates and lack of unified data and insights across the payments ecosystem can quietly drain revenue over time.
A study this year by LexisNexis found that every dollar lost to fraud in Asia-Pacific costs firms S$3.95, and that 75 per cent of Asia-Pacific businesses surveyed report that fraud impacts customer conversion. The longer businesses ignore issues with their payments, the greater the risk of those problems escalating.
Payment walls are coming down
Historically, the strategy of large payment service providers (PSPs) has focused on offering a full-stack solution, locking in merchants and “owning” the payments value chain, by proposing value-added services like fraud prevention, billing or tax solutions.
But in a global economy, where merchants are looking to grow and expand to new markets, there is greater pressure on existing PSPs to effectively manage the diverse web of regulations, payment methods, costs and risk.
2024 has been a year that major payment service providers have begun to modularise the all-in-one approach.
Merchants want to be able to access several different services throughout the transaction life cycle, recognising that traditional PSPs may not offer the best solution for every need. In response, major players like Stripe have decoupled payments from other services, moving towards a more inclusive ecosystem that recognises the need for interoperability.
As the payments ecosystem continues to develop, businesses taking a “DIY” approach to managing several services across the payments stack will only add more pressure on engineering and product resources, technical debt, data reconciliation and more.
Beyond the time and resources required to add new payment methods to your checkout, payments infrastructure also needs to be able to grow with the business, enable data sharing across different PSPs to support growth, provide real-time insights to boost authorisation and more. How do businesses keep up?
More than “off-the-shelf” payments needed
Today, businesses’ payment strategy must serve the global consumer. Take the travel industry, working across multiple currencies, and catering to vastly different consumer preferences across different regions.
Pelago, the travel experiences platform of Singapore Airlines, has said it is simply not possible to operate a global business using a single processor. Instead, it adopted a unified payments infrastructure to access multiple processors to meet local payment preferences and strengthen fraud protection capabilities across markets.
Regulations across different markets impact the cost of doing business, and different optimisation strategies for cross-border payments are needed to maintain payment success rates. Cost and delays associated with FX and cross-border payments remain a major pain point for businesses if not managed effectively. But they can also be a strategic advantage.
Hence, global businesses need to tailor their payments, leveraging local expertise to support them with strategies to innovate and expand without being limited by their payment infrastructure.
The businesses that will win will be those that act quickly, embrace change and invest in building payment infrastructures that can evolve as the market demands. The future of commerce is global, digital and increasingly diverse – and businesses must be ready to meet these demands head-on.
The writer is head of global sales at Primer
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons
Proton e.Mas 5 review: The little EV that beat Tesla
Cash-strapped AirAsia takes unusual step of unloading new planes

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

