

America should debate its broken fiscal future
If Washington refuses to change course, financial markets will eventually force its hand, and the crunch that follows will be brutal
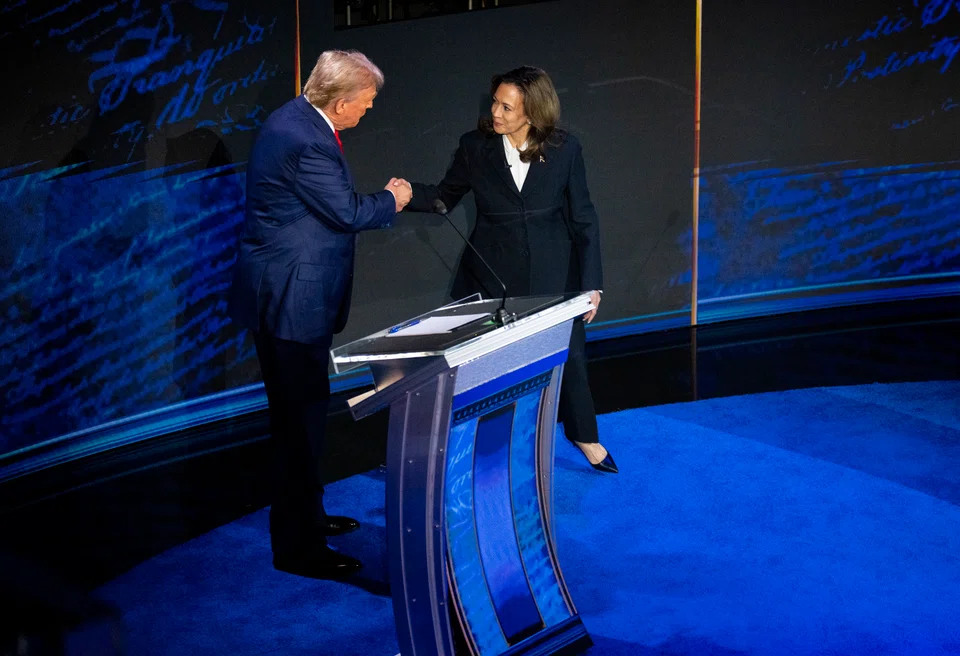
ONE of the most important issues facing the country has been conspicuously absent from the US presidential contest – and got only the most superficial mention at Tuesday (Sep 10) night’s debate. Democrat presidential candidate Kamala Harris and her Republican counterpart Donald Trump apparently agree that unsustainable public borrowing is not their concern. In fact, both are proposing to make the problem worse.
Trump’s fiscal plans – if you can call them that – are certainly more reckless than the vice-president’s. But both are promising tax cuts and spending increases that would deepen projected budget deficits and push the rising trajectory of public debt on to an even higher path. This literally cannot go on much longer. If Washington refuses to change course, financial markets will eventually force its hand, and the crunch that follows will be brutal.
As things stand, the budget deficit is on track to stay at roughly 6 per cent of gross domestic product over the coming decade – enough to raise net public debt from a little under 100 per cent of GDP now to more than 120 per cent in 2034.
Bear in mind, this assumes low unemployment, steady growth over a decade and interest rates that don’t spike because buyers of government debt start to panic. It also assumes that most of the tax cuts introduced in 2017 will expire on schedule at the end of next year – which Harris and Trump have both promised won’t happen, without saying how they’ll make up the difference. In other words, the most plausible current-policy “baseline” is already dire.
Yet both candidates are explicitly pledging to exacerbate the situation. Granted, their plans are so vague that costs can’t be calculated with much precision, but numbers from the Penn Wharton Budget Model give a sense of what’s coming – and it’s alarming.
Proposals
Trump’s most intelligible proposals (extend the provisions of the Tax Cuts and Jobs Act, lower the corporate tax rate to 15 per cent from 21 per cent, and eliminate taxes on Social Security benefits) would cost some US$6 trillion over 10 years, pushing the medium-term debt trajectory up another 10 per cent.
He’s also proposed an across-the-board import tariff of 10 per cent or more, which he says could pay for additional tax cuts. Even if tariff revenue wasn’t used for that purpose, it would fall far short of bringing deficits back under control. The more tariffs squeeze imports, the less revenue they raise – and that’s to say nothing of the broader damage they’d cause to the economy. If US trading partners retaliated, leading to a full-scale trade war, the economic setback would be massive.
By these standards, Harris’s fiscal plans look almost sensible – but the fact is, they aren’t. The plans she’s announced so far (increase the child tax credit to US$3,000, with US$3,600 for children under five years and US$6,000 for newborns; give first-time homebuyers US$25,000 in down payment assistance; raise the corporate tax rate to 28 per cent from 21 per cent) would add another US$1 trillion to deficits over the coming decade. The likely fiscal cost would be double that if you took account of the effect of higher corporate taxes on investment and hence on economic growth.
To be sure, the personal tax reforms Harris has advocated are, in themselves, good policy. Experience during the pandemic shows that giving more help to low-income families substantially reduces child poverty. But good policies still have to be paid for. Taken as a whole, promises that add to an already unaffordable outlook for public borrowing are simply irresponsible.
Every further delay in addressing the problem makes the fiscal outlook harder to stabilise. And the harder that gets, the more likely it is that financial markets will start asking whether the government is still creditworthy. Public debt isn’t a problem until, all of a sudden, it is – and then it’s too late. BLOOMBERG






