

Analysts, investors must challenge status quo to unlock value, forge a more vibrant market
The widespread undervaluation of Singapore stocks may have reduced the incentive to run companies for the benefit of minority investors
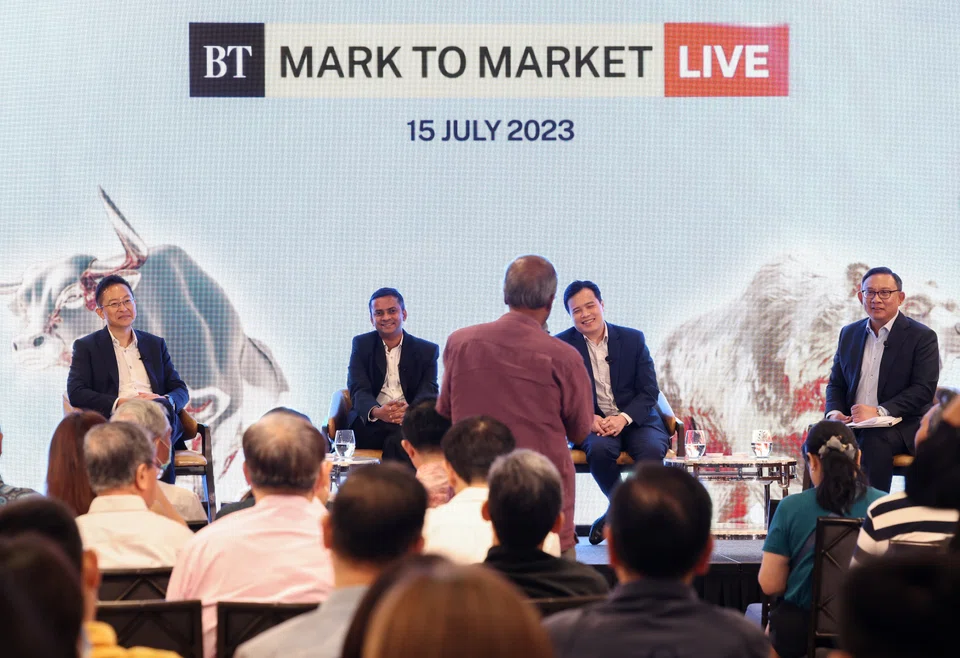
DURING the Mark To Market “Live” forum held earlier this month, there were lots of comments and questions from the audience about the long-term weakness of the Singapore market, and the widespread undervaluation that has resulted in many companies being taken private on the cheap.
Among the possible solutions floated during the lively discussion was that there should be more analyst and media coverage of promising Singapore-listed companies.
It was also suggested that Temasek and other Singapore institutional investors should be encouraged to invest more in the local market.
Another idea was that the Singapore Exchange should emulate its Japanese counterpart in actively pushing companies to address the undervaluation of their shares.
On the face of it, these are all good ideas. Taken together, they may well contribute to a more vibrant market and generally higher valuations for locally listed stocks.
These initiatives could, however, become a difficult and disagreeable business if they run up against the vested interests of a company’s board and controlling shareholder.
One consequence of the market’s weakness and the chronic undervaluation of locally listed stocks is that controlling shareholders have less incentive to ensure their companies are run for the benefit of minority investors.
What is the point of striving for higher earnings if this often does not result in a company’s shares trading at a richer valuation? Why not just try to take the company private for less than the book value of its assets?
The way I see it, analyst and media coverage would stand the best chance of enlivening the Singapore market if it were focused not just on highlighting companies that are undervalued, but also on explaining how value at these companies could be effectively unlocked. This would involve an independent-mindedness that may not sit well with the boards and controlling shareholders of some companies.
Similarly, the presence of big institutional investors in the market would probably make the most difference if those investors were inclined to aggressively push the companies in which they are invested to maximise shareholder value – even to the extent of having those companies drastically reposition their operations.
As for top-down regulatory directives, these could be effective – but only if our market regulators are prepared to mete out tough penalties for non-compliance. Much like analysts and investors, regulators need some steel in their collective spine if they are to make a real difference.
Fight at Sabana Reit
The quickly unfolding saga of Quarz Capital’s bid to internalise the manager of Sabana Industrial Real Estate Investment Trust (Sabana Reit) offers a stark perspective on how ugly and uncertain things can get when minority investors push for fundamental change.
When Quarz requisitioned an extraordinary general meeting (EGM) last month to put forward its internalisation plan, this column said it was effectively proposing to transfer value from ESR Group to unitholders of Sabana Reit.
Sabana Reit paid its sponsor group nearly S$7.3 million in fees in 2022. This was more than the S$6.9 million ESR Group would have received in distributions in respect of its nearly 20.7 per cent stake in Sabana Reit.
The problem for minority investors is Quarz’s internalisation plan could take more than a year to implement, and it is likely to involve further EGMs for the trustee to obtain directions from unitholders.
Sabana Reit’s manager has said the whole exercise is risky and potentially costly, and may end up destroying value for all unitholders. In particular, it warned that a change in Sabana Reit’s manager could trigger a mandatory prepayment of its loans.
The manager has also said there is no guarantee its staff will stay on until an internal manager is up and running, raising the possibility that Sabana Reit may be left without anyone to handle its day-to-day operations.
ESR Group went as far as applying to the courts for a declaration that Quarz’s EGM requisition is invalid, and a permanent injunction restraining Sabana Reit’s manager from convening an EGM. The courts dismissed the application last week. The EGM is now scheduled for Aug 7.
Will Quarz be able to push its internalisation plan through in the face of such fierce resistance from Sabana Reit’s sponsor group? Why is it seemingly prepared to risk crashing the Reit?
In my view, Quarz may be betting that ESR Group’s interests will converge with its own in the event its internalisation proposal is voted through next month. At that point, ESR Group may suddenly have as much interest as Quarz in ensuring that a properly licensed and adequately resourced internal manager is installed expeditiously.
OCBC’s hold on Great Eastern
Another interesting case on the horizon involves OCBC and its insurance subsidiary Great Eastern.
OCBC made headlines last month when it bought nearly 2.35 million Great Eastern shares at S$16.99 per share, which raised its stake in the insurer from 87.9 per cent to 88.4 per cent.
With Great Eastern now very close to losing the minimum required public float of 10 per cent, OCBC appears to be in a strong position to take it private at a bargain price. Great Eastern closed Friday at S$18.50 – a more than 51 per cent discount to its embedded value as at end-2022 of S$37.81 per share.
One reason Great Eastern’s market price does not reflect its fundamentals is because the stock is tightly held. Another possible reason is that Great Eastern has a longstanding practice of rewarding its executives with OCBC shares instead of its own shares.
Putting an end to this inappropriate remuneration practice, and promoting wider ownership of Great Eastern’s shares, could go a long way in lifting the market value of the stock.
Yet, it seems unlikely that Great Eastern will take any such action – because it is not in the interest of OCBC. As long as OCBC harbours intentions of taking Great Eastern private some day, it is likely to prefer that shares in the insurer simply languish.
What would it take for the interests of Great Eastern’s controlling shareholder to align with those of its minorities? Ironically, it might involve persuading OCBC that it is time to let go of its insurance arm for the sake of its own share price.
Nearly 20 years after making a strategic decision to subsume Great Eastern in order to increase its financial heft and diversify its sources of income, investors still sometimes debate whether OCBC would be less of a curiosity and easier to compare with its peers if it did not have a big insurance unit in its fold.
If OCBC were to propose a distribution in-specie of a major portion of its stake in Great Eastern, my view is that this could well trigger a re-rating in shares of both companies.
OCBC’s board and management will probably not be easily persuaded. For years, they have maintained the narrative that Great Eastern provides the group with an important competitive advantage in serving its customers. Moreover, Great Eastern has grown substantially over the past two decades despite being tightly owned by OCBC.
This brings me back to my original point. Unless analysts and investors are inclined to engage in the often difficult and disagreeable task of challenging the long-held attitudes and ideas of Singapore’s most respected companies to unlock value, we may never get the vibrant market we crave.






