

Asia’s AI rally is narrowing. But the opportunity is also broadening
Investors may find companies that offer better entry points, more specific earnings drivers and less crowded positioning
ARTIFICIAL intelligence has changed the way investors look at Asian equities.
The first phase was easy to understand: buy the visible beneficiaries. These are the semiconductor leaders, memory makers, foundries, hardware suppliers and companies closest to global AI infrastructure spending.
That trade was not wrong. Taiwan and South Korea have become critical toll booths of the digital economy. The capital expenditure cycle is real: Goldman Sachs Global Institute estimates annual AI capital expenditure at US$765 billion in 2026, rising to US$1.6 trillion by 2031.
But the more successful the first phase becomes, the more complicated the next phase becomes.
In some markets, buying the index increasingly means buying concentration. Taiwan Semiconductor Manufacturing Company (TSMC) occupies 41.5 per cent of Taiwan’s Taiex, while Samsung Electronics and SK Hynix together comprise 55 per cent of South Korea’s Kospi.
Many remain exceptional businesses with genuine earnings visibility. But investors need to be clear about what they own.
A benchmark-heavy position in North Asia can now be a large implicit bet on a narrow group of companies, a narrow part of the supply chain and a narrow set of end-demand drivers. The risk now is that too much future growth becomes priced into too narrow a group of companies.
The question is no longer simply whether AI demand will continue. The better question is where the next dollar of earnings growth is most under-appreciated, and where the risk-reward remains attractive after the rerating.
In our view, capturing alpha (market-beating outperformance) will increasingly require looking lower down the value chain – in the picks-and-shovels of the picks-and-shovels.
This is not just a slogan. Goldman Sachs Research forecasts the total addressable market for AI networking to increase nine-fold to US$154 billion.
That points to a broader opportunity beyond chips: advanced packaging, testing, optical networking, power, cooling, automation, precision components and materials.
These companies are not always at the centre of the trade, but they may offer better entry points, more specific earnings drivers and less crowded positioning.
This is why Japan is becoming more interesting.
A credible growth market
For many global investors, Japan has been viewed as a value market. More recently, the story has been governance reform, balance-sheet discipline and better capital allocation. Those remain important.
But that framing is now too narrow. Japan is also becoming a more credible growth market.
Japan’s reported policy ambition is to mobilise around 370 trillion yen (US$2.27 trillion) in combined public and private investment by 2040 across 17 strategic sectors, including AI, chips and space development.
Policy targets are not the same as earnings delivery, but they reinforce the direction of travel: Japan is trying to align industrial policy, private capital and strategic technology capability.
The AI angle in Japan should be neither overstated nor dismissed. Japan has meaningful exposure through semiconductor equipment, materials, precision manufacturing, automation, data-centre infrastructure and industrial technology.
Japan is different from South Korea and Taiwan because its market drivers are less concentrated.
South Korea and Taiwan offer more direct exposure to the AI hardware cycle through memory, foundry and semiconductor supply chains.
Japan’s AI exposure is meaningful and sits within a wider market that includes industrials, automation, capital goods, financials, consumer companies and governance-reform beneficiaries.
That breadth matters. If the regional AI rally becomes narrower and more concentrated, Japan may become a better hunting ground for long-term active managers.
The opportunity is not simply to buy Japan for AI exposure, but to find companies where growth, valuation and capital discipline are beginning to overlap.
“The next phase of Asia’s AI story will not be won simply by owning the most AI-heavy index. AI is concentrating benchmarks, widening dispersion and making public policy more important to equity outcomes.”
India offers a different lesson. It does not have a TSMC, Samsung or SK Hynix equivalent, and its listed information technology services sector faces real pressure from generative AI.
Its US$315 billion IT sector continues to face pressure from AI-driven business-model shifts and weak global client spending.
But India is not structurally excluded from the AI opportunity. The opportunity in India may lie beyond the benchmark.
Look beyond the large-cap IT names and there are companies enabling the build-out of AI infrastructure: power transmission equipment, optical fibre cable, networking equipment, electricals and data-centre-related infrastructure.
India’s data-centre capacity is expected to rise meaningfully over the next few years, creating a broader opportunity set for companies exposed to power, connectivity and digital infrastructure.
The public-policy dimension of AI is worth highlighting. Data centres are not just technology assets. They require power, grid reliability, land, permitting and local acceptance.
Semiconductor supply chains also depend increasingly on industrial policy, production incentives and national resilience strategies.
The countries that can align demand, infrastructure, policy and capital may capture more of the next phase of AI build-out than their benchmark weights currently suggest.
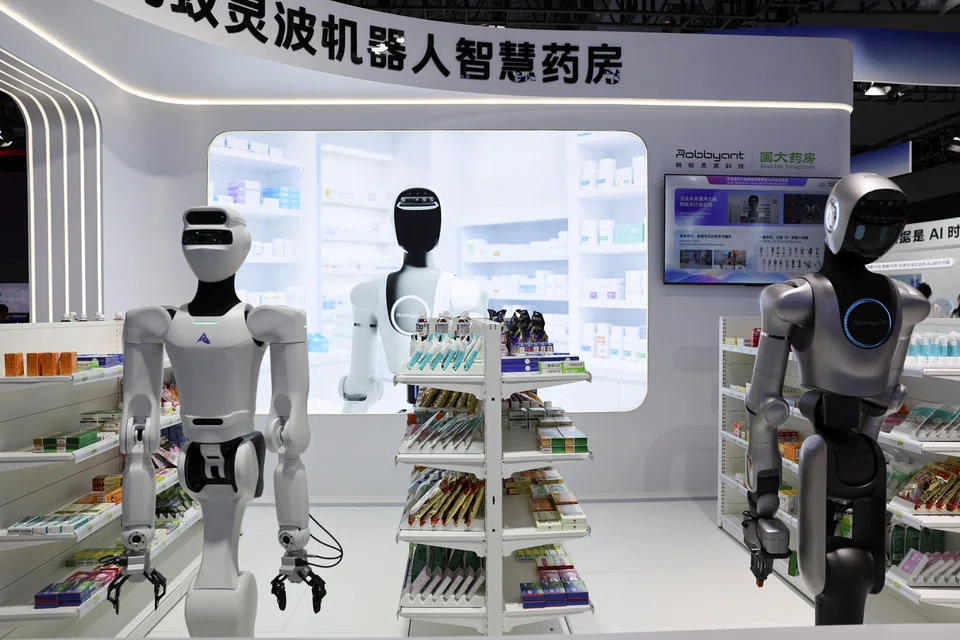
For some investors, China remains difficult from a risk, policy and geopolitical perspective. But it is progressing across multiple AI fronts: open-source models, humanoids and physical AI, semiconductor equipment and domestic supply chains.
Recent measures to promote AI adoption in consumption, progress in humanoid robotics and requirements for chipmakers adding capacity to use more domestically made equipment all point in the same direction: China is trying to move from AI adoption to deeper AI self-sufficiency.
That creates two types of opportunity: within China, in companies exposed to domestic AI, automation and semiconductor self-sufficiency; and outside China, as peers in Japan, South Korea and Taiwan innovate in order to compete.
Asia’s AI opportunity is therefore not one trade.
Taiwan offers quality and visibility, but also high expectations. South Korea offers AI exposure plus the possibility of governance-led rerating, but with more cyclicality. Japan offers breadth, reform and an increasingly credible growth overlay.
India offers less direct AI infrastructure exposure, but more scope for data-centre growth, enabling infrastructure and domestic adoption. China offers both direct AI opportunities and competitive pressure on the rest of the region.
The next phase of Asia’s AI story will not be won simply by owning the most AI-heavy index. AI is concentrating benchmarks, widening dispersion and making public policy more important to equity outcomes.
The opportunity is broadening beneath the surface, even as the headline rally becomes narrower.
For long-term investors, that is exactly the kind of market where active management should matter more, not less.
The writer is portfolio manager, Asian equities, at M&G Investments in Singapore. The views expressed in this article should not be taken as a recommendation, advice or forecast.
TRENDING NOW

Once staunchly pro-China, Malaysian Chinese businesses are now distancing themselves from Beijing

Britain’s mansion tax shows the difficulty of targeting wealth
Three hats, one goal: How Ng Kian Swan runs sustainability at NUHS
COE review: The gap between luxury and mass-market cars isn’t the only one worth bridging

