

Bridging the financing gap for climate impact in Asia: Challenges and opportunities
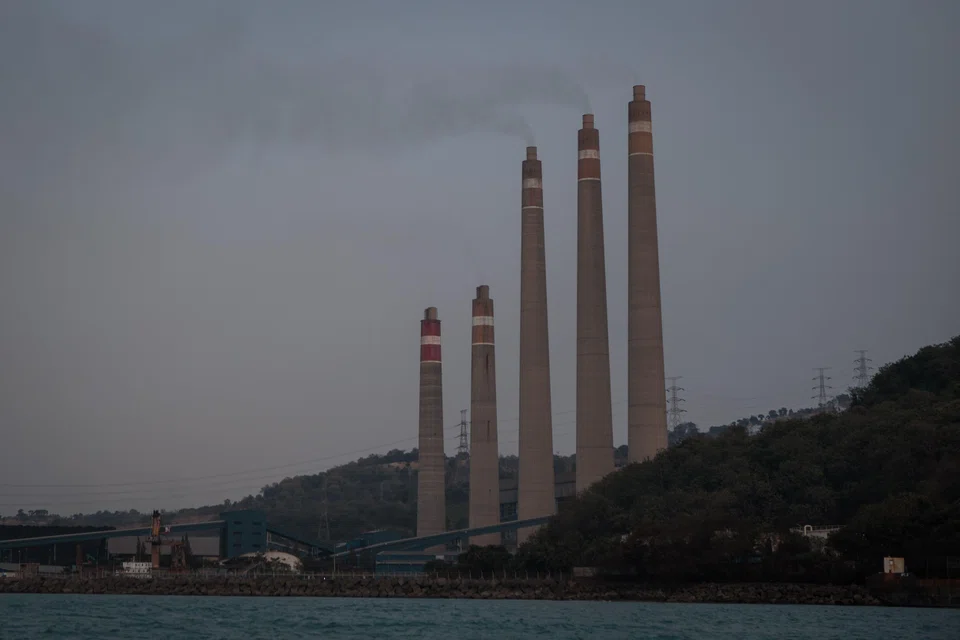
ACCORDING to the latest United Nations Emissions Gap report, we are racing past our 1.5 degree Celsius goal towards a 2.5 to 2.9 deg C temperature rise above pre-industrial levels. With Asia currently responsible for half of the world’s carbon emissions, there is an urgency for the region to accelerate climate action as the UN Climate Change Conference (COP28) gets underway this week. Yet Asia’s energy demand continues to grow, and it battles the multiple forces of economic development and the need to uplift its communities against the costs of a green transition.
For a dose of reality confronting the green transition, look no further than South-east Asia. South-east Asia’s Green Economy 2023 Report forecasts that energy demand, powered by a burgeoning middle class and a reliance on heavily subsidised energy and electricity, will grow by 42 per cent over the decade to 2030. This means that decarbonising the region while meeting energy demands and the need to deliver just and equitable economic growth will not be an easy feat. But we cannot concede defeat, because it would be impossible to become a net-zero world without Asia’s green transition.
Constraints in deploying capital
While there is general recognition that more capital needs to be channelled towards Asia’s transition to a greener economy, there are challenges. It often requires high upfront capital costs with insufficient or uncertain investment returns, uncertainties in policy direction, and market-access issues. Many projects are also either marginally bankable or unbankable. Furthermore, there is a dire need to uplift lives and communities, which means that climate objectives cannot be pursued in isolation without also considering socio-economic goals.
South-east Asia alone requires more than US$1.5 trillion in cumulative investment to meet its emissions reduction commitments of some 33 per cent by 2030, versus the US$5.2 billion observed in 2022. To close this financing gap, it is critical to take a systematic approach coupled with a diversified toolkit and innovative solutions that can bypass existing challenges and accelerate Asia’s green and just transition.
That is where opportunities lie, especially for investors like Temasek.
Paving the way for private investments
Blended finance de-risks climate investments, especially for marginally bankable clean infrastructure projects. Such an approach requires governments, multilateral development banks, and private and concessionary capital providers to come together and cultivate the right conditions for these projects to get off the ground. By de-risking projects in the early stages through first-loss capital, it is possible to fund critical development needs and crowd in necessary capital to finance breakthrough sustainable solutions.
Pentagreen Capital, a joint venture between HSBC and Temasek established in 2022, is one such example of how we are trying to bridge this gap. The platform aims to catalyse capital flows for sustainable infrastructure to unlock more marginally bankable projects.
In its first announced transaction, Pentagreen and Citicore Renewables recently collaborated on a US$100 million Mezzanine Construction Green Loan Facility for solar projects in the Philippines. The commitment of an initial tranche of US$30 million comes with a greenshoe option to increase the committed amount to US$100 million to fund additional ready-to-build greenfield solar projects, which would expand Citicore’s portfolio from 490 megawatts currently to over one gigawatt of renewable energy assets.
However, the viability of the approach relies heavily on various capital providers stepping forward and leaning in. To further scale and replicate this model, governments, multilateral development banks, and concessionary and philanthropic capital providers must come in to provide first-loss capital, and fund critical development needs. Private and institutional investors must then take calibrated risks and provide further capital to bring these projects to the next stage.
The complex real economy
In an ideal situation, the immediate decommissioning of Asia’s coal-fired power plants would address a large percentage of the region’s carbon emissions. But these plants are also responsible for nearly 60 per cent of the region’s power generation and the livelihoods of nearly 80 per cent of the 8.4 million people employed across the global coal value chain. A managed phase-out of these coal projects, with clear net-zero glide paths, is necessary, especially with Asia’s energy demands growing in tandem with economic development, population growth and rapid urbanisation.
This means that decarbonising the region needs to be done in a balanced manner to ensure continued energy accessibility and security. Fossil fuels will likely continue to play a role in the near to medium term, especially when many coal-fired power plants in the region are younger and have long lifespans.
Deployment of capital here can come in various forms, such as tapping on innovative solutions like transition credits. The Monetary Authority of Singapore is working alongside multiple partners, including Temasek’s decarbonisation investment platform GenZero and carbon marketplace and exchange Climate Impact X, which we jointly established with DBS, the Singapore Exchange and Standard Chartered. The partnership looks at creating a new asset of carbon credits to reduce the economic gap in the early retirement of coal plants. This could act as a buffer by providing revenue while the plants are being phased out.
We also see opportunities to provide capital to scale renewable energy, reduce costs in energy storage, as well as invest in solutions that mitigate carbon emissions from existing power and industrial assets. For example, we invested in Svante, a carbon capture and storage solutions provider, and Form Energy, an energy storage company that is developing a low-cost and multi-day duration battery for grid applications.
Accelerated radical collaboration
Public policies and government action, such as carbon taxes and financial incentives, can help to redirect investment flows in support of the transition. Simultaneously, the private sector, multilateral development banks, international financial institutions and concessional finance can play complementary roles.
Scaling of capital can also be done through strategic partnerships among the private sector. For example, recognising the gap in financing for early-stage growth companies, Temasek launched Decarbonisation Partners with BlackRock, jointly committing US$600 million to invest in such companies, thus targeting proven technologies that can reduce carbon emissions and crowding in like-minded partners.
When these different sources of finance work together, they can create powerful synergies that can help to accelerate economic growth and development. We need more of such collaborations across the public, private and developmental finance sector players to crowd in capital and deploy climate finance at scale.
Heading into COP28, we all recognise that the world is not on track to achieve net-zero goals, and this highlights the crucial and urgent need to attract private-sector financing. But the road to climate impact in Asia is full of complexities, and progress to net zero is not a one-size-fits-all endeavour. It demands a systems approach where all sectors lean in, with all hands on deck, and at an accelerated pace.
As UN Secretary-General Antonio Guterres aptly puts it: “We have never been better equipped to solve the climate challenge, but we must move into warp-speed climate action now. We don’t have a moment to lose.”
The writer is chief financial officer of Temasek
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose
Number of listed companies an ‘outdated metric’ of Singapore market’s success: SGX chairman

UOB found ‘grossly negligent’ over Stamford Land rights issue advice, to pay S$1.9 million
Oil climbs after Trump denies he is willing to ease sanctions on Iran

