

Bukit Sembawang ticks all the right boxes, so why aren’t investors biting?
LIKE many property developers on the Singapore Exchange (SGX), mainboard-listed Bukit Sembawang Estates trades at discounted valuations. It is also thinly traded.
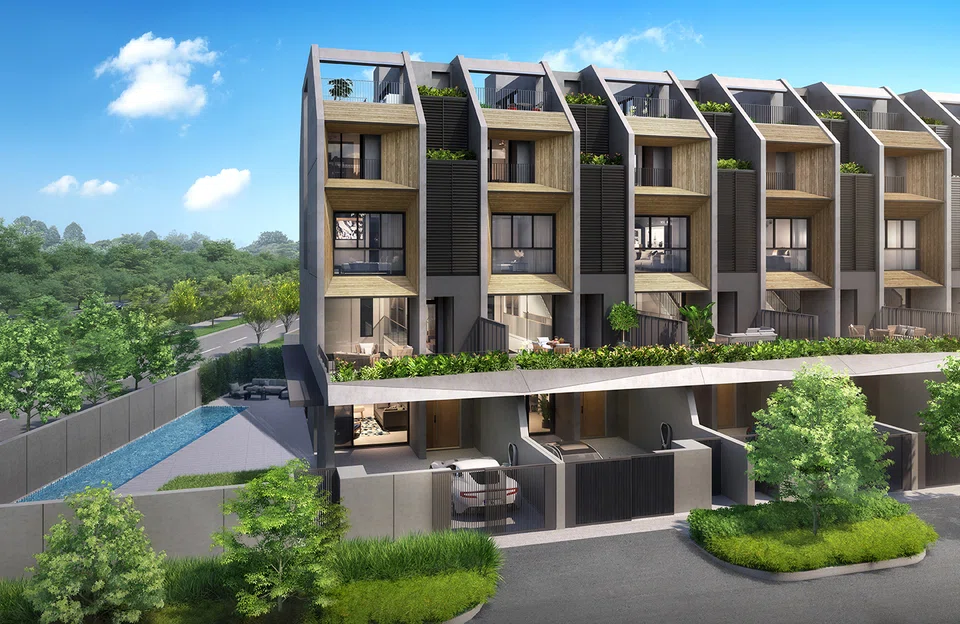
But the company – which recently reported changes to key management – has a relatively healthy balance sheet. Bukit Sembawang’s specialisation in developing landed properties and luxury condominiums may also make it worthy of investor attention amid the current property boom.
The counter has fallen 7.5 per cent over the past year to close at S$4.58 on Wednesday (Feb 8). That is worse than the 0.4 per cent decline in Singapore’s benchmark Straits Times Index, but is comparable to the average among real estate developers on SGX.
Financials
The current price values Bukit Sembawang at an 18 per cent discount to its net asset value (NAV) per share of S$5.61 as at Sep 30, 2022.
This is slightly better than the median price-to-book ratio of around 0.5 for its property development peers.
Yet, Bukit Sembawang’s NAV may be relatively conservative.
Around half the group’s total assets as at end-September were development properties valued at S$835.8 million. The value used is the lower of either cost or net realisable value, which means some of the assets may be worth much more.
In mid-2021, DBS Group Research analysts noted that the group had a sizeable land bank – pegged to low historical cost – slated for landed homes.
The analysts had previously estimated Bukit Sembawang’s revalued NAV at S$10.76 per share.
Property prices in Singapore have since risen further: the Urban Redevelopment Authority’s landed property price index for the fourth quarter of 2022 has gained 16.9 per cent since the second quarter of 2021.
With its sizeable land bank, Bukit Sembawang is also less likely to be pressured to bid for new development sites. The DBS analysts had noted in 2021 that the group had enough inventory for the next decade.
Land scarcity, growing affluence and the appeal of landed properties may prove to be tailwinds for Bukit Sembawang.
The group’s overall balance sheet also appears to be relatively healthy. Bukit Sembawang had cash and cash equivalents of S$533.1 million as at end-September 2022, while its borrowings only amounted to S$65.4 million.
Its total debt-to-total assets ratio as of its latest financial statement was 4.1 per cent, which was significantly better than the 35.9 per cent average for its peers according to Bloomberg data.
Bukit Sembawang’s net cash position may allow it to capitalise on opportunities to add to its land bank. The group’s relatively low debt position is also helpful amid rising interest rates.
But it may also face challenges if the global economy were to enter a recession, as buyers may prefer prudence over splurging on luxury properties.
The inflationary environment and supply chain disruptions may also weigh on costs of developing projects.
Management changes
In October 2022, the company appointed Chng Kiong Huat as its new chief executive after operating for more than a year without one.
In August 2019, former CEO Ng Chee Seng had announced his retirement after 13 years at the helm. Chief financial officer Ooi Chee Eng was appointed acting CEO, but Ooi left in February 2021.
Chief operating officer Charles Chow was then made responsible for operations.
Chng – a registered architect – had previously been a non-executive director of Bukit Sembawang. He stepped down from the board this month to focus on his CEO role and to “meet the management and operational needs of the company in its property development business”.
Chow tendered his resignation this month to pursue other opportunities.
Realising value
It is hoped that new management will have new ideas for unlocking value.
Bukit Sembawang saw an average of under 45,000 shares trading each day over the past year. The stock also has no sell-side analyst research, after DBS suspended its coverage in June due to reallocation of resources.
A privatisation offer is one option, although recent history suggests it would be a poor one.
Property developers such as Roxy-Pacific Holdings, SingHaiyi Group, Fragrance Group and Top Global were taken private at prices deemed by their independent financial advisers (IFA) to be “not fair, but reasonable”.
Investors eyeing upside opportunities in Bukit Sembawang should be mindful of the lessons that past precedents in the Singapore market provide when making their investing decisions.
TRENDING NOW

Despite the de-dollarisation debate, demand for dollar liquidity in Asia is growing

URA to review guidelines on floor space to give developers more design flexibility: Chee Hong Tat

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Can a first-time homebuyer couple earning S$18,000 a month afford a new EC unit?

