Can management changes help YZJ Financial realise value?
Raphael Lim
SOMETHING appears to be brewing at Yangzijiang Financial (YZJ Financial).
The investment management company hit an all-time low last month, shortly after it announced that chief executive officer (CEO) Vincent Toe would leave the company next April.
The counter slipped to S$0.295 on Oct 26, closing below S$0.30 for the first time since it was spun off from Straits Times Index (STI) constituent Yangzijiang Shipbuilding (YZJ Shipbuilding) in April 2022.
Apart from Toe’s impending departure, YZJ Financial has also recently announced other changes to its senior management. These include the removal of the chief investment officer (CIO) roles and the resignation of its general counsel.
The company has said the leadership transition impacts neither the group’s strategic direction nor its operations.
But it may take more to fully reassure shareholders, and adequately convince them to value the company closer to its book value.
Leadership changes
Toe, who is said to be leaving the organisation “to pursue other opportunities”, will stay on until April 2024 to aid in the transition. He is also YZJ Financial’s Singapore CIO, alongside China CIO Peng Xingkui.
YZJ Financial said that it made the “strategic decision” to remove the CIO roles following Toe’s departure as part of the streamlining process. Peng will be reassigned to another role in the group, but will remain a member of the investment committee.
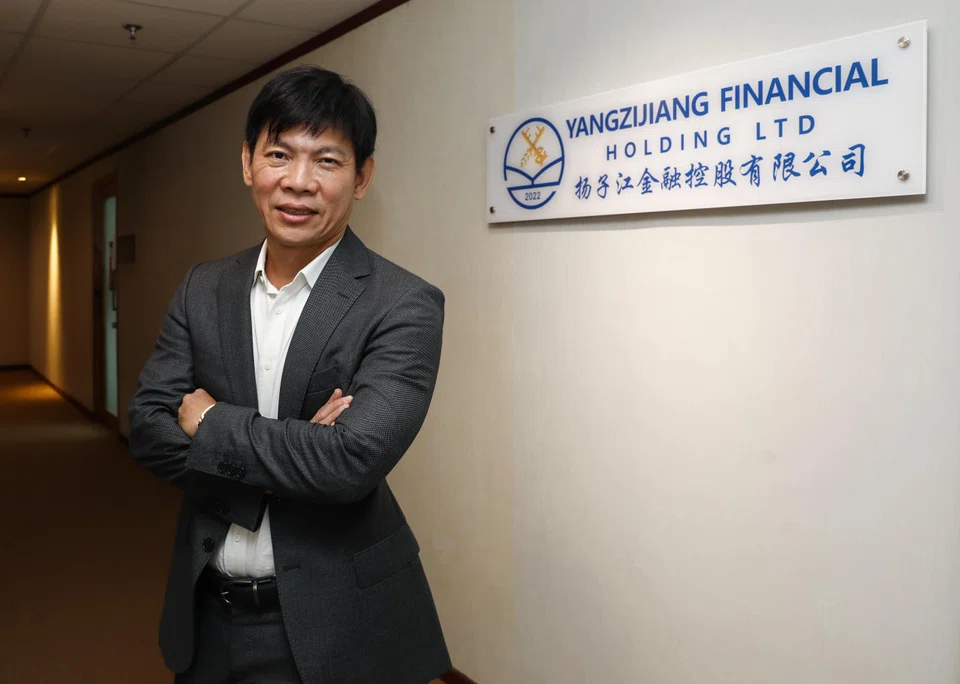
Meanwhile, executive chairman Ren Yuanlin – who is also the largest shareholder of YZJ Shipbuilding and YZJ Financial – will assume the role of YZJ Financial’s CEO on the date of Toe’s departure on Apr 24.
Ren will also oversee the group’s investments, both in China and Singapore, which were being undertaken by the CIOs.
The group’s chief financial officer (CFO) and chief operating officer Liu Hua will be appointed as deputy CEO, in addition to retaining her existing CFO responsibilities.
The company said it did not expect day-to-day operations to be impacted.
“We would also like to reassure our shareholders and stakeholders that this leadership transition neither alters the group’s strategic direction nor impacts its operations,” Ren said at the time.
Investors, however, did not appear to be convinced.
YZJ Financial’s shares fell as much as 16.2 per cent on the next trading day amid heavy volume, before eventually closing 7.4 per cent lower.
Earlier this month, YZJ Financial also announced the resignation of its general counsel Koh Boon Chiao effective end-December. The group is in the process of searching for a new candidate to cover the Singapore regulatory compliance function.
The counter has recovered slightly from its end-October lows, but still trades below the levels prior to the announcement of the management changes.
New direction?
It is not surprising that investors are opting for a cautious stance.
YZJ Financial has said it strives to be “a leading investment manager in Asia, focusing on sustainable long-term value creation”.
But the current changes mean that it will lose both CIOs responsible for overseeing the investments in China and Singapore. The company has also not announced the hiring of any additional investment professionals with similar responsibilities so far.
A key question for investors would be whether a leaner management team would still be able to deliver on YZJ Financial’s existing plans. Investors should also weigh potential strategic shifts that might arise following the management changes.
Outgoing CEO Toe and executive chairman Ren have vastly different experiences.
Toe has been the CEO of YZJ Financial since it went public last year, and brought with him over 25 years of experience in the financial sector, including in fund management and investment advisory.
Ren, meanwhile, is an accomplished businessman – having grown YZJ Shipbuilding over the years.
YZJ Financial has said that Ren “is well placed to assume his new responsibilities, in particular the group’s asset allocation and investments”, given his more than 40 years in the shipbuilding industry and “extensive experience and business acumen”.
Ren’s experience would clearly be useful for YZJ Financial’s maritime fund, which has a US$600 million target size. The capital would come from both YZJ Financial and other parties, and the group has said that this fund is one of its key focus areas.
YZJ Financial’s exposure to the maritime fund is currently small. Its stake in the fund accounts for just 2.1 per cent of its portfolio as at June. Around 61.1 per cent of the portfolio was in debt investments, while 20.9 per cent was in cash and yield enhancement products.
Investors would also be closely watching how he manages the rest of the portfolio.
Prior to the spinoff, most of YZJ Financial’s investments came from debt investments in China. The group has a long-term strategy to diversify and allocate around half of its investments outside of China.
The group has been facing non-performing loans (NPLs) in its debt portfolio in China, but it had reduced its NPL ratio to 37 per cent in June 2023, from 41 per cent six months earlier. It said in August that it is “cautiously optimistic” about the recovery prospects of its remaining NPLs.
As at June 2023, the group’s international investments outside of China were valued at S$574.4 million, accounting for 14.5 per cent of its total portfolio.
Unlocking value
The move to spin off YZJ Financial last year was, in part, a value unlocking exercise. While it has worked well for YZJ Shipbuilding, the same cannot be said for YZJ Financial.
At listing, YZJ Financial had a net tangible asset per share of around S$1.08, and the counter was initially an STI constituent. But it closed its first day of trading at S$0.62 and was booted out of the index, as its market capitalisation was the smallest among all constituents.
The shares have slid further since, closing at S$0.325 on Friday (Nov 10). It represents a nearly 70 per cent discount to its net asset value per share of S$1.052, and a trailing price-to-earnings ratio of 6.4.
Valuations have stayed muted, despite the company buying back its shares regularly. Some 70.1 million shares have been repurchased since its mandate was obtained in April.
Just one analyst covers the stock currently. CGS-CIMB had an “add” recommendation with a S$0.55 target price in August.
While investors may be more cautious currently, they might be more reassured and value the company closer to its book value if the company can show in the coming quarters that it is still able to progress towards its long-term strategic objectives despite the management changes.