

Blue skies ahead – piloting a tokenisation take-off
MAS’ strategy for building Singapore’s digital asset ecosystem is an excellent step towards cementing the Republic’s status as a leading global financial centre and fintech hub
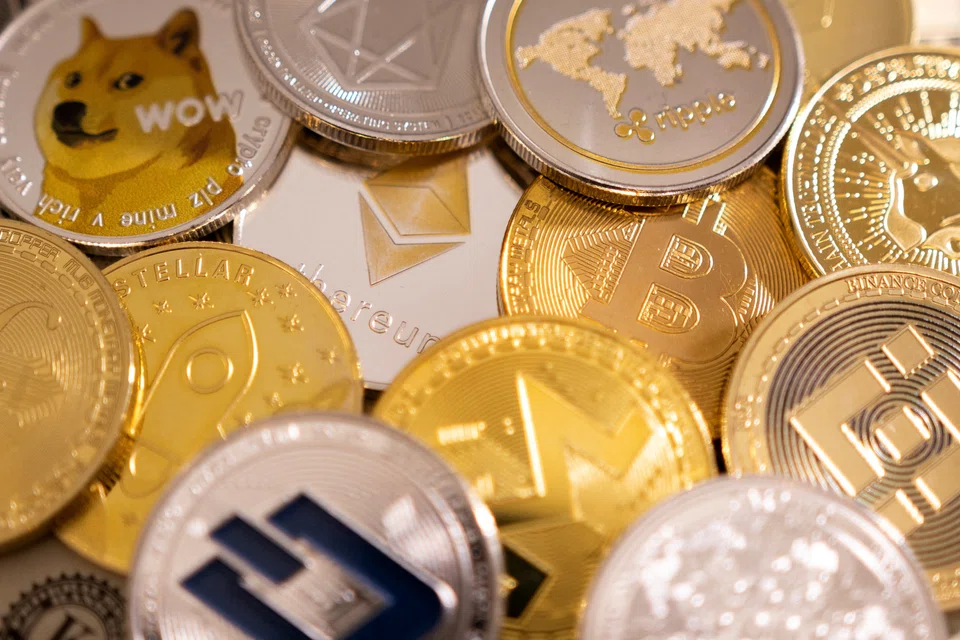
THE Monetary Authority of Singapore (MAS) recently clarified its stance on digital assets and cryptocurrencies. In a speech on Aug 29, MAS managing director Ravi Menon also set out MAS’ strategy to build a digital asset ecosystem. While MAS discourages cryptocurrency speculation, it supports innovation in digital assets such as the tokenisation of financial and real economy assets and the use of distributed ledger technology (DLT) in financial services.
The emphasis on promoting the digital asset ecosystem is timely as industry trends indicate an upsurge in the use of DLT in financial markets. A survey by the International Securities Services Association (ISSA) comprising 148 organisations across the global investment cycle shows that over 30 per cent of the industry is using DLT in live production, a four-fold increase from 2021. By 2023, it is expected that over 50 per cent of current projects will progress from experimentation to commercial usage with market participants looking beyond cryptocurrencies to tokenise securitised assets, bonds and mutual funds.
Such increased levels of DLT adoption could transform capital markets. In particular, the ‘tokenisation of securities’, or the digital representation of financial instruments such as shares, bonds or fund units on distributed ledgers and the development of secondary markets for tokenised assets, would not only facilitate efficient securities trading and transactions but also enhance financial inclusion and unlock economic value. As Menon stated, the innovative combination of tokenisation and DLT offers transformative economic potential.
Financial markets innovation race heats up
Singapore, however, is not alone in this journey. Other financial centres too are exploring ways to transform their financial markets by testing new technologies. After all, part of what it takes to be a pre-eminent financial centre is to have the best technology stack and ecosystem on offer.
For instance, the European Union (EU) in June 2022 introduced a regulation announcing a 3-year pilot regime commencing March 2023 for DLT-market infrastructures for tokenised assets that qualify as financial instruments (essentially shares, bonds and fund units). This is intended to enable the bloc to play a leading global role regarding tokenised financial instruments and to contribute to the development of a secondary market for those assets. The regulation also permits DLT market infrastructures to operate in a test environment and exempts such operators from several requirements of EU financial services legislation.
The United Kingdom, too, has announced its digital assets aspirations and its vision to be a global hub for crypto-asset technology. The Financial Services and Markets Bill introduced in UK Parliament in July 2022 recognises that DLT could potentially provide greater efficiency, transparency and overall resilience in the performance of financial market infrastructure. The Bill empowers the UK Treasury to set up a suitable sandbox and, similar to the EU’s approach, to temporarily disapply or modify relevant financial services legislation to facilitate innovation.
The EU and UK’s willingness to embark on pilot regimes, notwithstanding the current trials and tribulations surrounding cryptocurrencies, clearly indicate their confidence in the digital asset ecosystem and the economic gains that DLT and tokenisation could offer.
Towards the digital horizon
Seen in this light, MAS’ efforts to facilitate tokenisation through industry participation and experimentation will be crucial to uncovering and understanding the specific risks and benefits relating to digital assets. In building this digital asset ecosystem, 5 key issues will need to be addressed:
1. Securities issuance – While most use cases in Singapore have till now focused on tokenised assets, the next phase in securities evolution is the issuance of native digital securities tokens or asset tokens that are issued directly on a DLT allowing for a fully digital issuance process and life cycle. Countries such as Luxembourg, France and Germany have adopted specific legislation allowing companies to issue certain securities on a DLT thus providing legal certainty for such issuances. Likewise, it would be necessary for Singapore to assess how asset tokens and smart contracts could be effectively accommodated under Singapore law and regulatory frameworks.
2. Payment mechanisms – To fully realise the expected benefits of tokenised securities, such as instant settlement and reducing counterparty risk, digital settlement mechanisms will be required. In his speech, Menon mentioned the potential of wholesale central bank digital currencies and stablecoins to facilitate settlements and experimentation will be crucial to assess which option works best.
3. Asset categories – Most DLT pilots globally have been around digital bonds and fixed income products. To fully realise the potential of DLT and tokenisation, pilot use cases should extend to other asset classes such as securitised assets, infrastructure assets and private funds. The recent launch of a distributed ledger fund settlement utility, Fundnode, which will aim to enhance efficiency in funds settlement in Singapore, is a good example.
4. Identity solutions – To comply with securities regulations and to ensure that only eligible participants transact in tokenised asset transactions, the pilot use cases should look into the suitability of appropriate institutional mechanisms that can screen and issue verifiable credentials. Such mechanisms should also be capable of issuing tokens and performing checks at token levels to ensure that transfers comply with investor suitability.
5. Stakeholder awareness – As tokenisation efforts gather pace, the key question is how they will impact issuers, investors and other market participants. As part of industry engagement, emphasis must be placed on DLT and tokenisation education, its distinction from cryptocurrencies and awareness to build trust in these technologies, gain stakeholder acceptance and drive adoption.
To cement its status as a leading global financial centre and fintech hub, it is imperative for Singapore’s financial markets and the regulatory frameworks that underpin it to remain appropriate for the digital age. MAS’ strategy for building Singapore’s digital asset ecosystem is an excellent first step in this direction. With its pro-innovation attitude, openness to attracting investment and anchoring players with strong value proposition and execution capabilities, there is every reason to believe that Singapore’s digital assets aspirations will take flight and soar.
The writer is head, regulatory affairs and industry engagement, at Marketnode, a SGX Group-Temasek joint venture.
TRENDING NOW
Two Singapore-listed palm oil firms named in Greenpeace report on Indonesian plantation fires
Singapore Airlines flight returns to San Francisco after ‘unruly’ passenger incident
Singapore looking into which companies responsible for haze-causing fires: PM Wong
Deluge IPO 3.86 times subscribed ahead of SGX debut

