

Fed rate cuts have mixed impact on stocks, so don’t get carried away
Investors should carefully examine the thesis for any purchases, especially since equities have been on a generally upward trajectory for the last two years
THE United States Federal Reserve is almost certain to deliver an interest rate cut next month, and strategists are predicting positive movements in many parts of the market.
Past trading patterns, however, show mixed results from cuts to the federal funds rate (FFR). Investors should carefully examine the thesis for any purchases, especially since equities have been on a generally upward trajectory for the last two years.
The MSCI World Index, for instance, has gained roughly 53 per cent since hitting a four-year low of 2,379 points in 2022. The S&P 500 is up by about 57 per cent from its 2022 low of 3,586 points.
There are several reasons why stocks have room to run. Vasu Menon, managing director for investment strategy at OCBC, noted that the amount of money parked in US money market funds is at a record high of US$6.2 trillion.
“Once rates are cut, money will move out of these funds in search of better returns in equities and bonds,” Menon said. “The firepower from liquidity should not be underestimated and is a silver lining for medium-term investors – assuming the outlook for the US economy and earnings remain decent, and there is no recession.”
Although equity markets have rallied since the start of early 2023, valuations are “not excessive”. “Lower rates support higher price-to-earnings multiples, so Fed rate cuts should support equity markets,” he added.
No clear patterns
The relationship between interest rates and stock valuations is complicated, though. Factors that affect this relationship include prevailing interest rates, macroeconomic conditions and sentiment.
Analysis by BlackRock portfolio manager Russ Koesterich found that higher real rates are associated with higher multiples, and that this is particularly true when rates are rising from low levels.
Kelvin Wong, senior market analyst at Oanda, looked at dovish Fed pivots dating back to 1957. Of the 12 episodes, four were followed by periods of positive performance in US stocks in the three months after. Over a 12-month period, there were four instances of negative performance.
A paper published in the Journal of Banking and Finance found that outside of a crisis period, an unexpected cut in the FFR led to an increase in stock prices. During the financial crisis of 2007 to 2009, however, cuts were interpreted as signals of worsening future economic conditions and triggered a flight to safety.
Some sectors of the stock market are also more sensitive to rate changes than others, and correlations with interest rates might be positive or negative depending on a stock’s fundamentals. Yield plays do better as interest rates fall, for instance.
South-east Asian story
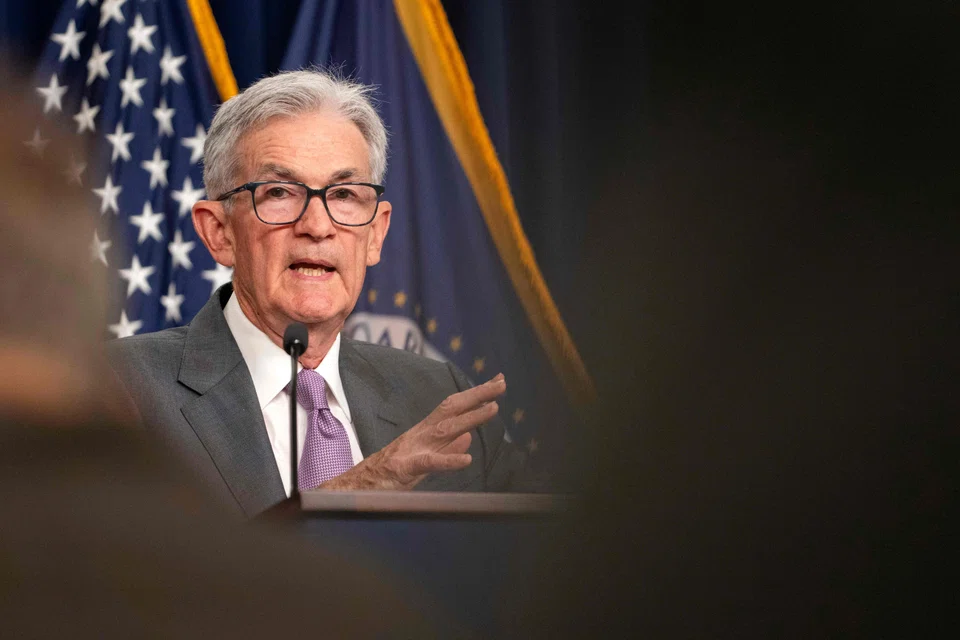
The Powell pivot – as it is now being called, after Fed chair Jerome Powell – could be relatively more positive for equity markets in Singapore and South-east Asia.
Singapore’s Straits Times Index has had a more modest gain of 14 per cent since its 2022 low, partly because real estate investment trusts (Reits) and property developers make up a significant portion of the index.
UOB Kay Hian (UOBKH), in an Aug 26 report, said that Reits should “regain their lustre for investors desiring income”. It noted that many Singapore-listed Reits trade at attractive distribution yields of 6 to 7 per cent.
“Relatively lower borrowing costs should encourage more merger and acquisition activities and capital recycling,” UOBKH added. Beneficiaries would include asset managers CapitaLand Investment and Keppel, as well as developer City Developments.
Maybank analyst Thilan Wickramasinghe, in an Aug 23 report, highlighted several companies that are more sensitive to interest rate changes due to their high interest costs.
These are caterer and ground handler Sats; healthcare Reit Parkway Life Reit; financial services platform iFast Corporation; property groups Wing Tai Holdings, Hong Fok Corporation and Frasers Property; and commodity suppliers Golden Agri-Resources and Olam Group.
“Lower rates should be a boon across Asean, encouraging emerging market flows and strengthening (currencies),” Wickramasinghe said in a separate report dated Aug 26.
Domestic tailwinds include increases to civil servant salaries in Malaysia, an aggressive fiscal strategy in Indonesia, and the appointment of a new prime minister in Thailand.
Cliffs to watch
The biggest risk to equity prices is likely to be an escalation of the tariff war between China and several developed markets.
A Citi report noted that emerging markets in Asia have traditionally reacted positively to Fed rate cuts, especially if not associated with a US recession, but that trade conflicts mean investors may be better off sticking with markets that have “strong domestic growth momentum”.
These would include India, Taiwan, South Korea and Japan, the bank said. For South-east Asia, which depends more on “traditional industrial demand”, the situation may be more neutral from a growth perspective, it added.
Investors should therefore be circumspect with their market bets. The Fed appears to be cutting rates more to head off a recession, and whoever becomes the next US president is unlikely to leave off putting pressure on China. There is unlikely to be a rising tide that lifts all boats.
TRENDING NOW

Grab CEO’s wife Chloe Tong on life with Anthony Tan and finding her purpose

Singapore-based Ryde accused of pump-and-dump fraud in class action lawsuit

Malaysia’s F1 return: A low-cost second chance, possible Singapore boost

Canada is upping oil flows to Asia, but South-east Asia’s refineries aren’t ready to handle them yet

