

Long auditor-client relationships a threat to independence
The role of auditors is so crucial that they cannot afford to get too close to their clients at any level.
RECENT regulatory changes in the European Union (EU) have sparked off a spate of new auditor appointments in listed entities. In July 2015, British bank Barclays replaced PricewaterhouseCoopers (PwC) with KPMG as its auditors after 120 years of association. In the same month, Aberdeen Asset Management, one of the UK's largest asset manager, picked PwC as its new auditors, ending a 32-year affair with KPMG. Earlier this year, in March, Schroders announced it would switch its auditors of 57 years from PwC to another firm via a tender for its audit. Other corporate behemoths such as Rolls-Royce and Tesco have made similar moves. This is just the tip of the iceberg.
All these changes in appointment came hot on the heels of new rules in the EU where an audit firm can be the auditor of a public interest entity for a maximum period of only 10 years. EU member states can opt to extend this if a tender is held at the end of the 10-year mark. If the incumbent auditor is re-appointed, he can stay in the role for another 10 years, capping it at a total of 20 years. After that, a new auditor must be appointed. Gone are the days when an entity can remain with one auditor for decades. The bottom line is auditors cannot have too long a relationship with their audit clients as a long tenure can give rise to familiarity threats to auditor independence.
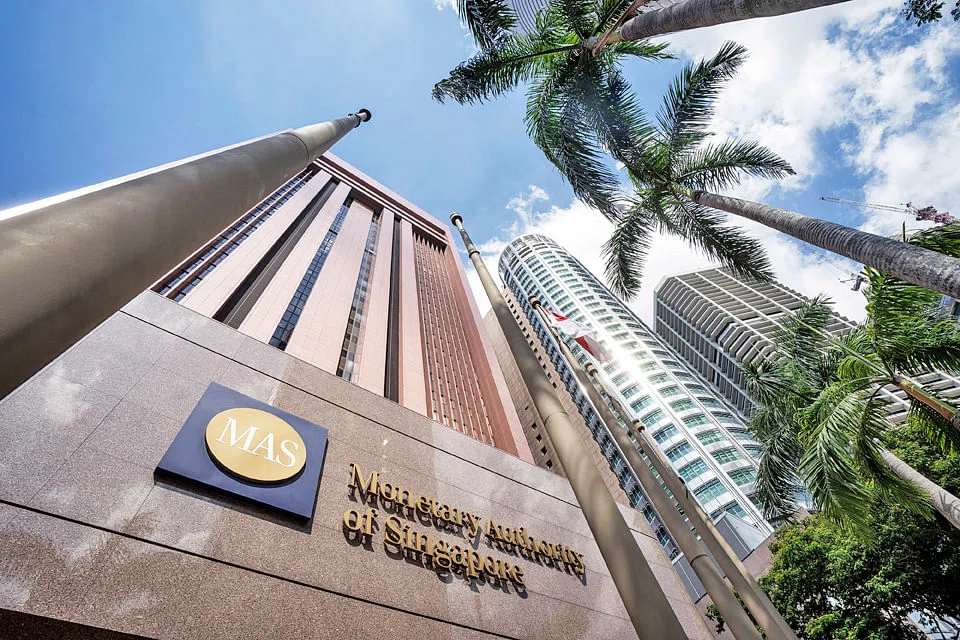
In September, the Monetary Authority of Singapore (MAS) issued a consultation paper proposing to dispense with the audit firm rotation requirement for the three local banks. The requirement was suspended in October 2008 due to the global financial crisis and is the only one in Singapore where mandatory audit firm rotation is being applied. In supporting the proposal, the MAS highlighted numerous measures which have been put in place since 2008 to strengthen auditor independence.
At the heart of the issue is auditor independence - the mainstay of the audit profession in gaining public trust and enhancing public confidence. Without auditor independence, we can practically throw any audit out the window. Credibility of the audit will be found wanting. As the foundation of the profession, auditor independence has to be as solid and impregnable as it can be. In the fairy tale The Three Little Pigs, the big bad wolf effortlessly blew down the house of straw, but was helpless against the house of bricks. Auditor independence cannot, and must not, be a house of straw.
Given the significance of auditor independence, it is both inevitable and reasonable that public expectations of this element are on the rise. In the current business, investment and regulatory climates, it is no longer sufficient merely for the auditors to know that they are independent. More crucially, external parties such as the general public, investors and regulators have to be satisfied and assured that the auditors are indeed independent. Otherwise, it may be more than just one or two disgruntled shareholders that entities have to placate.
The saga earlier this year involving Singapore Post (SingPost) is a very good example. As much as SingPost attempted to justify the appointment of its long-standing external auditor of more than 10 years for an impending special audit, public opinions were anything but convinced that it was the right choice. In the end, another party had to be enlisted to jointly undertake the assignment to appease the public dissension.
The SingPost episode has illustrated that independence in appearance is just as vital as independence of mind. Auditors must be seen to be able to perform their role objectively. This will go a long way towards instilling a high level of public confidence in the audit profession and the audits carried out. Auditors can plan and execute the most detailed and meticulous audits, but if the public has misgivings about their independence, no one will trust the opinions given by the auditors.
Hence, a positive market perception of auditor independence is especially critical for a global financial hub such as Singapore. In attracting foreign investments to boost economic development, Singapore prides itself on having a first-class financial reporting environment where investors can safely rely on financial statements verified by auditors without any cause for concern. Strong auditor independence unquestionably attests to this achievement.
Equally important, genuine threats exist if auditors get too familiar with their clients, which may impair their independence. In the world of audit, familiarity may breed complacency. The auditors may be overly trusting of the clients' work as a result of the affable working relationships established over the years.
For instance, an auditor who has not encountered any audit issues with a long-term dream client who keeps impeccable accounting records, may unwittingly be lulled into a false sense of security and assume that every audit will be as plain sailing as the previous year. The auditor's objectivity will be clouded even before the audit has started. The predicament will worsen if the client is a major contributor to the auditor's revenue. The client, if he knows he has leverage over the auditor, may turn the screws on the auditor to deter him from acting professionally during the audit. The auditor himself may also succumb to his inner demons since he will loathe losing a key customer who may be pivotal to the survival of his firm.
By the same token, the auditors may become overly sympathetic to the plights of their clients. For example, consider a long-time client who suffers a severe downturn in business and faces the likelihood of banks recalling loans granted to him unless the financial statements show a healthy position. He pours his sorrows to the auditor and hints that the auditor can help by selecting certain pre-determined samples for testing. Out of compassion, the auditor may be at risk of compromising his audit.
It is apparent the threats have to be eliminated, or at least mitigated. But this is no easy feat. It requires striking a balance between achieving audit quality and addressing the risks. To carry out a high-quality audit, auditors need to have a comprehensive understanding of their clients and their businesses, in order to identify and tackle the relevant risk areas. This requires auditors to spend sufficient years on the engagements to learn from experience, especially if considerable complexities are involved. On the other hand, to overcome the threats from being too close to clients, auditors should not spend an extended period of time with them.
The International Ethics Standards Board for Accountants (IESBA) is hoping to deal with this paradox with a recent proposal for an audit partner to stay away from an audit engagement for a certain number of years so that another partner can take over to have a "fresh look". The number of years will depend on the role undertaken by the audit partner, such as whether the partner is in charge of the audit engagement and signs off the auditor's report, or whether the partner is in charge of reviewing the quality control aspects of the engagement. The audit profession should watch this space for future developments.
To compound the issue, it is not merely the business relationships with clients that auditors have to be wary of. Recently, the Securities and Exchange Commission fined EY US$9.3 million for failing to keep in check the personal relationships of two of its partners and their respective clients, thereby undermining their roles as independent auditors.
In the final analysis, the role of auditors is so imperative that they can ill afford to get too close to their clients for comfort at any level. Auditors need to remain professional and independent at all times. There are no two ways about it.






