

More regionally driven growth needed: IMF
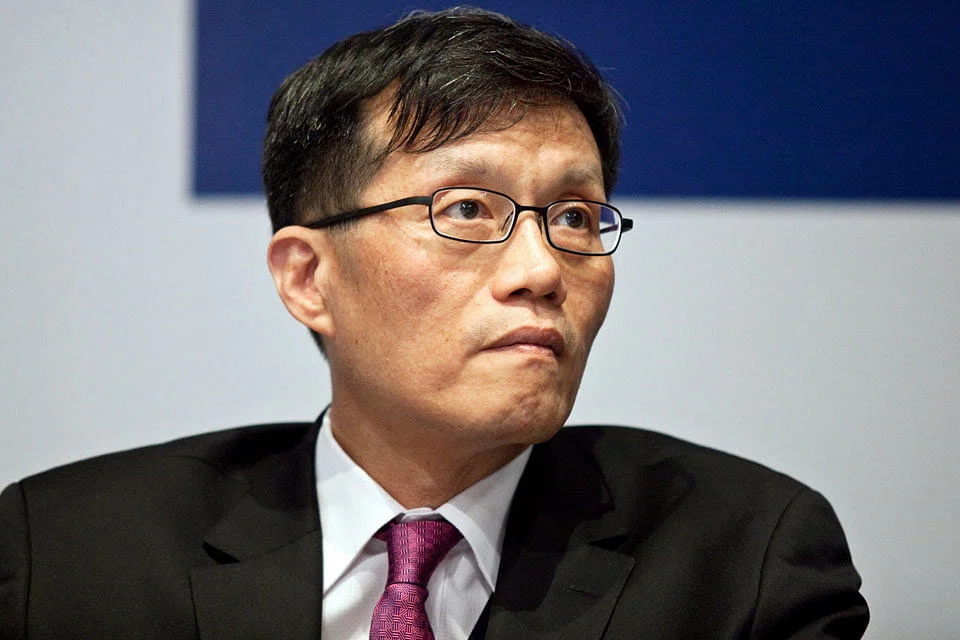
Changyong Rhee, director of the IMF's Asia and Pacific Department, discusses Asia's growth prospects, the AEC and intra-regional trade, and the challenges posed by ageing in the region.
ALTHOUGH Asia is growing at quite a robust pace of 5.6 per cent, growth is slowing. What are the reasons for the slowdown?
Asia's robust growth performance since the global financial crisis is testament to right sets of policies and structural reforms implemented during the past decade and a half. That said, Asia's growth has moderated, owing to several factors. First of all, it's because of convergence. Many Asian economies are moving from being low-income countries to being middle-income countries. And some middle-income countries are becoming high-income countries. As economic theory tells us, as a low-income country you can have many growth opportunities; you can mimic many activities of advanced economies and so on. So growth rates tend to be higher. But as countries move up the ladder, their growth rates naturally start to moderate. This is happening in Asia. China is a good example. Second, China's role in Asia's growth has been dominant. When China slows down because of convergence, it has an impact on the supply chain network, which affects many Asian economies. Third, before the global financial crisis, advanced economies were growing really fast. We now know that a lot of that was the result of bubbles and other unsustainable forces. Asia benefited a lot before the global financial crisis by exporting to advanced economies. But those unusual opportunities are gone now. So after the crisis, Asia's growth has naturally slowed. Now Asia has to find new growth momentum from within the region, including domestic expenditure-led growth.
You mentioned the slowdown in China. How confident are you that the deleveraging taking place in China will happen in an orderly fashion. Also, how long do you think it will take?
It's hard to say, but so far so good. China has managed its slowdown quite well. China's financial market is still not completely open. So even though the leverage is high, it's not so much external debt; it's mostly domestic debt. They also have many policy tools to deal with the problem if something bad happens. They have both fiscal and monetary policy room. That will help China manage a gradual adjustment.
As the economy develops, China will have to put in place many reforms, particularly reducing the heavy involvement of the government and opening the financial market to the private sector . So there are risks, but so far China has managed the transition quite well. On how long the transition will last, that really depends on the pace of the reform effort.
Turning to Japan, there is much scepticism about the so-called third arrow of Abenomics, namely structural reform. What is the International Monetary Fund's view of the prospects for structural reform in Japan?
Japan has initiated a large number of reforms - more so than previous governments. So the Abe government deserves praise for this. But we believe there is room for accelerating the pace and introducing more bold reforms. That will also reduce the burden on monetary policy. So far, monetary and fiscal policy have led Abenomics. Unless there are stronger outcomes from structural reform, monetary policy will be overburdened. So we really hope they can accelerate structural reforms. There are several initiatives we emphasise. One is labour market reform. There has already been a significant improvement in female participation in the workforce. It has risen by 3 per cent, which is no mean achievement. But we believe there must be more than that. Especially in the light of ageing, Japan really needs to introduce game-changing labour market reforms, including how to leverage foreign workers more. Second, given Japan's high debt-to-GDP ratio, a clear medium-term fiscal consolidation plan is important. There also needs to be more product market competition to improve efficiency. In that connection, concluding the Trans-Pacific Partnership (TPP) will be important.
One worrying finding in the IMF's Regional Development Report is a decline in the potential rate of growth in the region. Why is this the case?
The reasons vary by country. Take Korea. Korea is rapidly ageing, and labour shortage is a major issue. In China, there is a lot of inefficient investment. So there, the slowdown of total factor productivity is a major reason. In India, the problems include labour market rigidity, the supply of energy and infrastructural bottlenecks. The convergence factor that I mentioned earlier (countries growing more slowly as they become more developed) is another factor.
The IMF report also points out that Asia's export growth has slowed down, even after the recovery from the global financial crisis. Why has this happened?
We don't mean to suggest that the global economy has entered a period of secular stagnation. But it's unlikely that the advanced economies will move quickly back to the potential growth rates that they had during the pre-crisis period. That has implications for the export growth of the Asia-Pacific region. But if Asian economies achieve greater integration, intra-regional trade could become another source of growth eventually. But that depends on what efforts are made towards this goal.
Speaking of intra-regional trade, the Asean Economic Community (AEC) will be launched at the end of this year. How does the IMF feel about the prospects and potential impact of the AEC?
It's a great initiative - as I said, more integration would be good - but the level of ambition needs to be enhanced. Our view is that the low hanging fruit has already been picked. If you look at intra-regional trade, from 1992 to around 2005, it increased quite rapidly. But since the middle of 2005, it has plateaued. Basically the easy trade opening and tariff adjustment for non-sensitive goods have already been done. If each country can agree on greater integration that includes more sensitive areas of trade, that would increase intra-regional trade without the bold effort of the AEC. But if countries are satisfied with just reaping the low hanging fruit, this initiative won't go very much further. Whether the AEC has a large impact on the region really depends on policymakers' willingness to address the sensitive issues.
What are these sensitive issues?
They include the opening of service sectors, more financial market integration, and more labour mobility. These can create winners and losers in domestic economies, but the overall gains would be larger. The question is whether there is political willingness to address these issues. The higher the ambition, the better the results are likely to be. Mediocre ambitions will produce mediocre results.
We still have quantitative easing from Europe and Japan, and we don't know how long this will continue. Should Asian countries still be on guard against asset bubbles?
Together with the expansionary monetary policies in the EU and Japan , we expect monetary policy to normalise in the United States. So at this moment, many people are worrying more about the asynchronous nature of monetary policies in advanced economies and the dangers of abrupt capital outflows from Asia. So at this moment, it's fortunate that the advanced countries' monetary policies offset each other. That's the good news. But at the same time, it will increase volatility in currency markets and financial markets. That is something we will have to closely monitor.
You mentioned ageing. This is affecting a lot of economies around the region, including China, Japan, Korea, Taiwan and Singapore. Are Asian policymakers well prepared to deal with this problem, and are they doing enough?
They all understand the problem, but on whether they are doing enough to address it, I have some reservations. Certainly, higher female labour participation is very important, and we have been advising governments on ways to achieve this. But societies must do more, and I don't think progress has been rapid in many countries. Second is the issue of using foreign workers. Singapore has taken bold steps here although there are some issues about how to use foreign workers more efficiently. But if you look at Japan and Korea, they have a more closed market (to foreign workers). They have policies for enhancing the birth rate, but judging from the experience of European countries, unless you also have more cross-border mobility of labour and efficient use of foreign labour, it has certain limitations for the ageing problem.
It's time for Asian policymakers to be more open- minded about this. It's about a trade-off: if you're a high- income country, do you want to sacrifice growth and have a more homogenous society - or do you want to have a more dynamic economy by opening up to foreign workers? So that's the choice, and it's not just an economic choice; it's also a social and political choice. But policymakers have to address this issue.
TRENDING NOW

He built the Vingroup empire. Now South-east Asia’s richest man is handing some key roles to his sons

Floods compound Philippine growth woes from public-works scandal

Tokyo reverses baby bust with AI matchmaking and generous subsidies
More interest in ETFs, low-cost funds but Singapore still lacks pressure to further lower fund fees

